Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.
This report covers the HV ETF Master List from Thursday’s StatSheet and includes 312 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 186 (last week 148) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.
In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms. If you missed the original post about the Cutline approach, you can read it here.
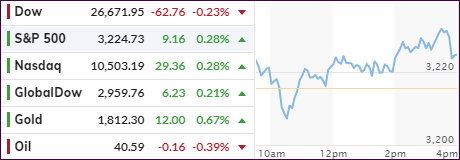
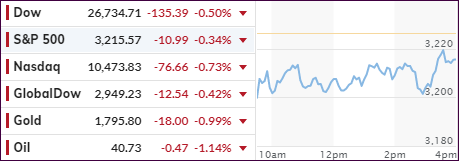
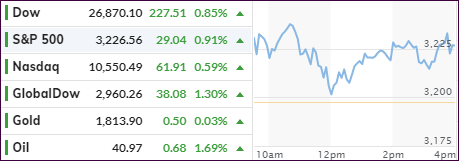
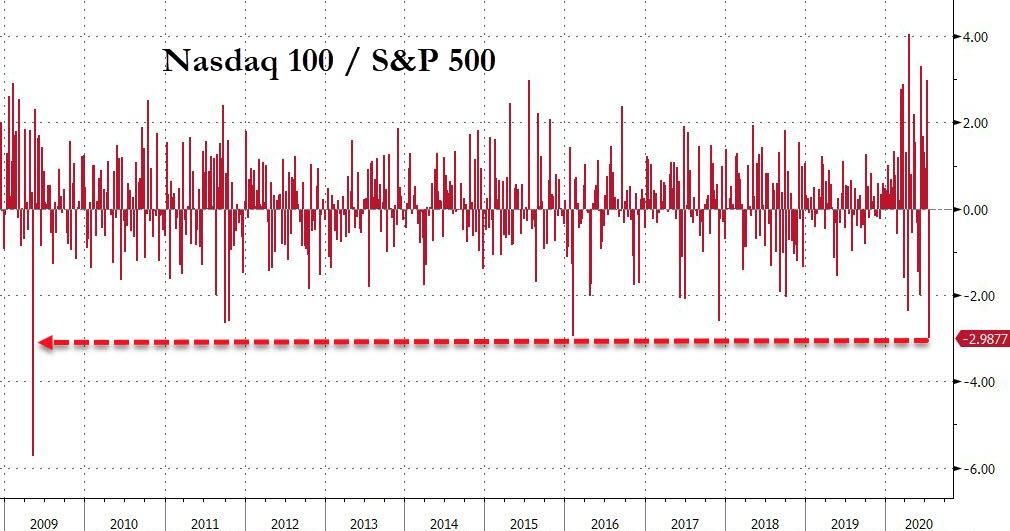
Volatility continued today, but in the end the Dow added some 2.5% for the week, the S&P 500 gained around 1%, while the Nasdaq skidded near -1.4% and suffered its worst weekly underperformance relative to the S&P 500 since 2009. This is minor when considering the Nasdaq’s YTD gain of some 22% vs. the SPY’s meager +0.99%.
The early bullish theme reversed, as the consumer sentiment index dropped to 73.2 from 78.1 vs. expectations of a rise to 78.6. Once again, the fallout from the virus continues to make itself felt, as activities are simply restricted blurring any forecasts especially those related to jobs.
For the day, the S&P 500 and Nasdaq climbed out of an early hole, while the Dow was the laggard by closing slightly in the red. It looks to me that the rise in Covid-19 cases has limited stock advances, and has overpowered optimism for further stimulus, at least for the time being.
Of course, a sudden or unexpected fiscal stimulus announcement will likely provide the bulls with more upside momentum, and I would expect such a move, should the “one-time” $600 unemployment bonus which is due to run out by the end of July, be extended.
On deck, and possibly having a far-reaching impact, is the 2-day summit of the EU’s 27 member states, which got underway this morning in Brussels. The subject will be a controversial 750 billion Euro recovery plan, which already face heavy resistance from fiscal conservatives in the bloc.
“Presumably, as is the way of Europe, they will agree to come back from more talks followed by a compromise and a watered-down deal,” Societe Generale’s Kit Juckes said of the EU discussions. “The positive though is that we are getting a recovery fund.”
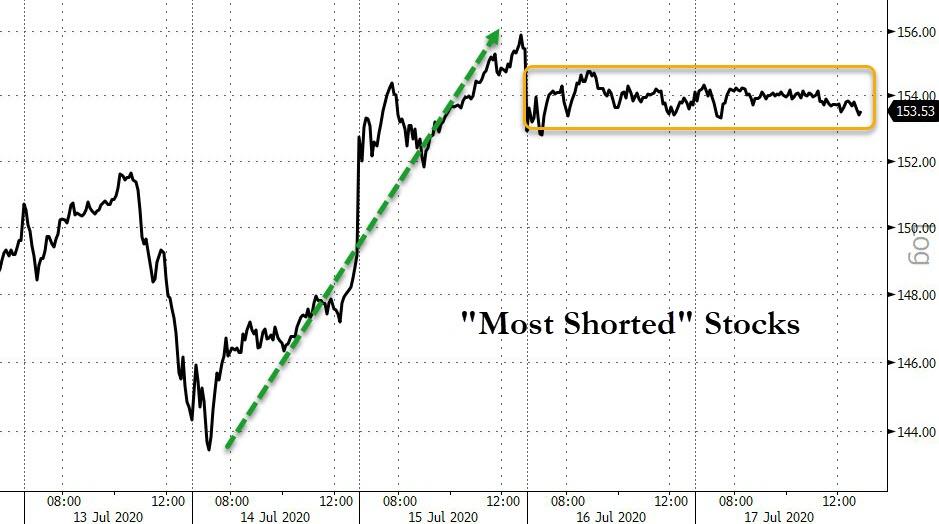
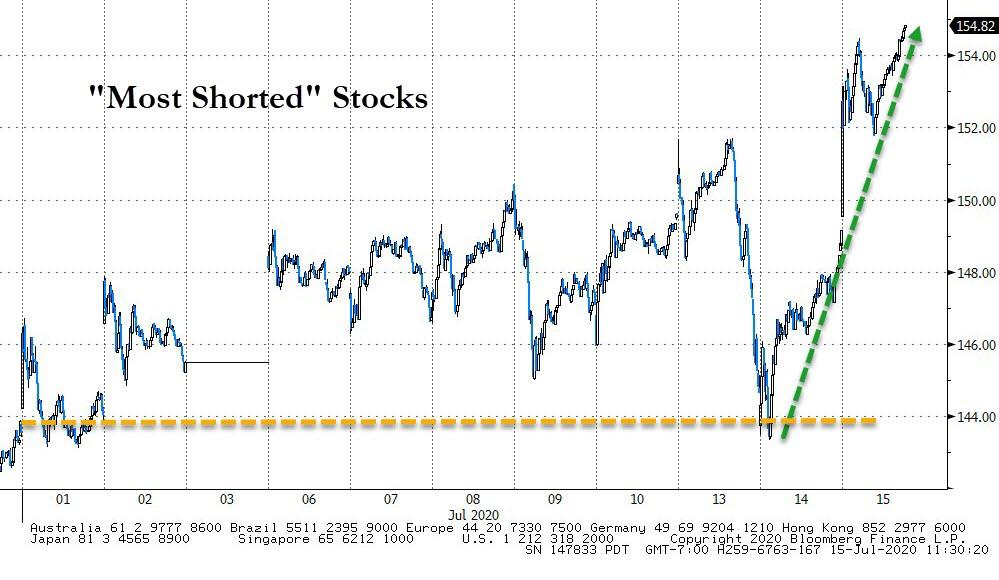
Back to the US. It’s interesting that, after being squeezed Tuesday and Wednesday, the shorts were ominously quiet, as ZH put it, and Bloomberg’s chart demonstrates. That is why the bullish moves over the past 2 days were muted and, with the Fed being quiet, caused some aimless meandering in the markets.
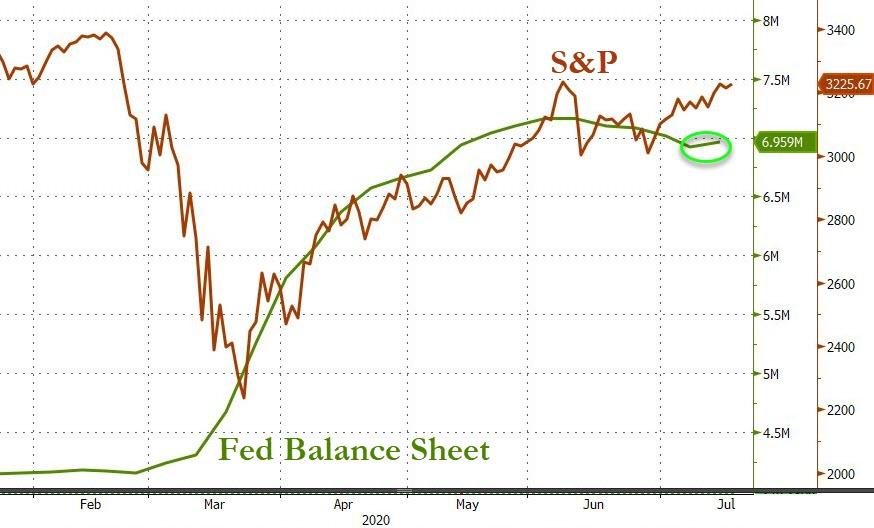
For sure, such sideways trending is bound to end, especially once the updated numbers come out again, showing that the Fed’s balance sheet has slightly reversed and is trending modestly upward again, as Bloomberg’s chart shows.
1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.
2. Trend Tracking Indexes (TTIs)
Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use a 7.5% trailing stop loss on all positions in these categories to control downside risk.
3. All other investment arenas do not have a TTI and should be traded based on the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending on your risk tolerance.
If you are unfamiliar with some of the terminology, please see Glossary of Termsand new subscriber information in section 9.
1. DOMESTIC EQUITY ETFs: SELL— since 06/25/2020
Click on chart to enlarge
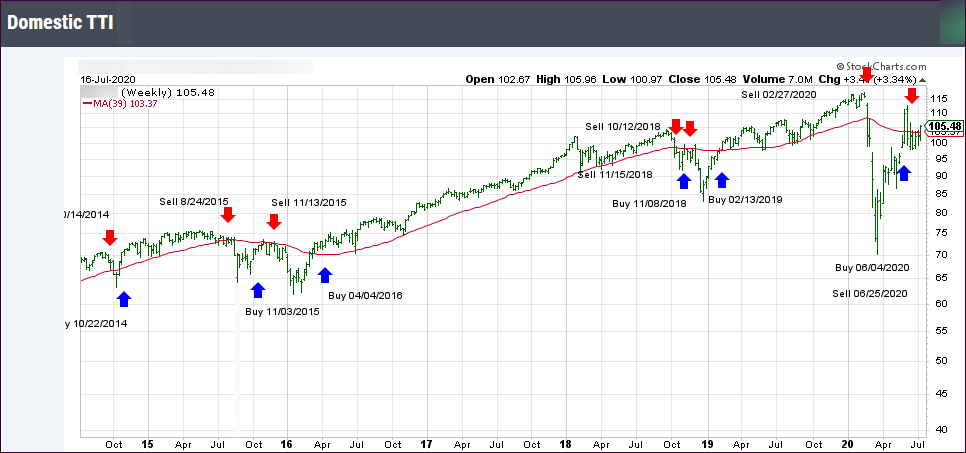
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) has now rallied above its long-term trend line (red) by +2.03% but is still in “Sell” mode until we see more upside verification.
Yesterday’s hard-fought gains vanished in a hurry with bearish sentiment taking over by pulling the major indexes off their lofty levels right after the opening bell. We ended up off the lows but still in the red.
Contributing to the drop were mixed corporate earnings and questionable econ data, as well as an early drop in the Asian markets. Chinese stocks suffered their biggest one-day loss since the beginning of the pandemic.
Domestically, tech stocks/ETFs have been on a tear YTD but are starting to look a little wobbly, yet they are not even close to triggering their respective trailing sell stops.
Big banks so far have delivered earnings in line with expectations mainly by showing outsized gains in their trading divisions, but BofA stumbled somewhat due to concerns about the boost in its loan loss provisions. However, with the bar set extremely low for second quarter earnings, it comes as no surprise that any “beat” will be cheered as a bullish event by the headline scanning computer algos.
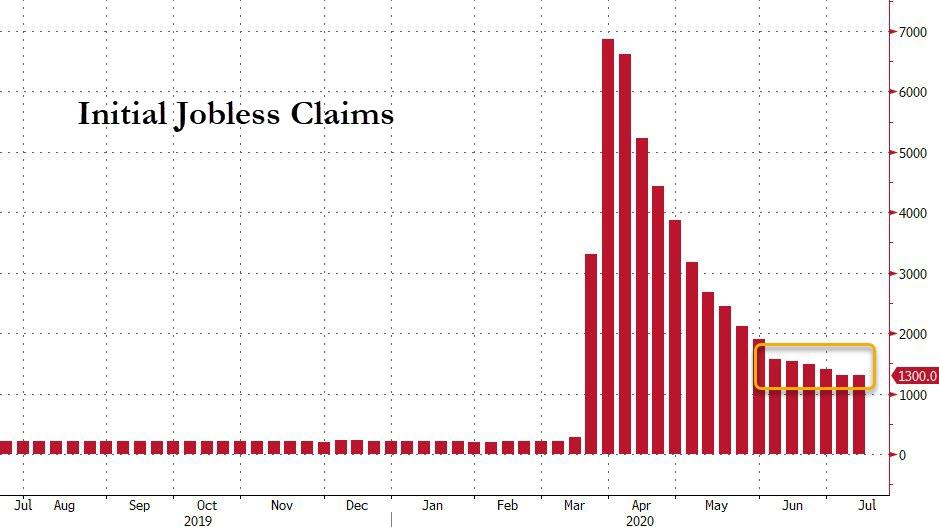
Despite hopes for a recovery, non-farm payroll data continued to paint a not so good picture, as over 50 million Americans have now filed for first-time jobless benefits since the lockdown began. Today’s data showed another 1.3 million first time filings vs. an expected 1.25 million, according to ZH, with Bloomberg adding the visual picture.
It’s no secret that the Fed is controlling the markets, and we are ever so close to face a managed economy. I grew up in one, but you probably did not, so Michael Every from Rabobank explained about an economy that could never keep supply matching consumer demand, such as the old Soviet system was famous for:
A man goes into the Soviet car showroom and asks to buy a car. The disinterested salesman doesn’t even put out his cigarette and says, “We only take 100% cash payments.” The man puts down a bag full of rubles on the table. The salesman sits up and counts them greedily.
“The only color is grey,” he informs the customer as he counts.
“No problem,” the man replies. “When will it arrive?”
The salesman slowly looks through a dog-eared book and says “Mmm…….five years from today.”
The customer nods sagely; and then asks: “Morning or afternoon?”
“What do you care morning or afternoon?” asks the salesman “It’s five years from now!”
“Well,” says the customer, “I am getting my fridge in the morning.”
It struck my funny bone and hopefully this moment of lightheartedness can bring smile on your face in this all too uncertain world.
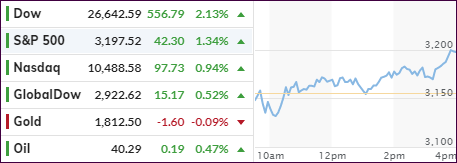
An early ramp ran into resistance with the major indexes pulling back sharply, and the Nasdaq dipping into the red, but a mid-session bounce pulled stocks out of the doldrums and into a green close. Today’s session was a lot choppier than yesterday’s rebound.
Supporting the continued bullishness was the Fed’s account of business activities in its 12 districts, which showed activity picking up, but sluggishness from the fallout of Covid-19 still being a factor. In other words, uncertainty reigns and a wave of layoff lurk on the horizon.
Given that, traders focused on some bright spots in second quarter earnings and the never-ending race for a vaccine. Moderna Inc. put itself back in the limelight and got the bulls roaring early on as its coronavirus candidate produced a “robust” immune system response in a larger group of people, according to MarketWatch.
But:
“Solicited adverse events that occurred in more than half the participants included fatigue, chills, headache, myalgia, and pain at the injection site,” the report states. Fever, joint pain, and nausea were also reported.
Helping the bullish Moderna story was a massive short squeeze, the biggest in 3 months, reported ZH, but it did not help the S&P 500 conquer critical resistance after testing it four times today.
The Nasdaq lagged in performance, but broad-based advances assisted our Trend Tracking Indexes (TTIs) to conquer their respective long-term trend lines to the upside.
While all three major indexes raced ahead and closed with solid gains, it was the Nasdaq, and to a lesser degree the S&P 500, which had to dig themselves out of a deep hole early in the session, as red numbers dominated.
The late day pump came from none other than Fed Governor Brainard, who called for a sustained large-scale asset purchase by the US Central Bank to help the economy rebound amid a “thick fog of uncertainty” brought on by Covid-19.
There you have it; how much more of a wink with a fencepost can you get? Especially, ahead of a devastating earnings season, confirming once again that fundamentals no longer matter, and we are clearly witnessing a centrally planned market environment.
Brainard also warned that the U.S. economic recovery likely “will face headwinds for some time,” and require further accommodation, while speaking during a virtual event hosted by the National Association for Business Economics.
Regarding the latest on Covid-19, ZH summed it up like this:
Spain places 160,000 under lockdown
EU drops Serbia, Montenegro from safe travel list
Arizona sees big jump with 4,273 new cases
North Carolina sees record hospitalized
Alabama reports record rise in deaths
Moderna releases latest clinical trial update
TMC releases latest Houston numbers
Philly bars all public events until Feb 2021
Florida positivity rate jumps to 15%+
Florida reports biggest jump in deaths
India places Bangalore back on lockdown
US daily cases below 60k
Global daily cases below 200k
Hong Kong imposes new restrictions
France makes mask wearing mandatory in public
Australia cases top 10k.
Iran closes mosques, schools
WHO warns: “there will be no return to normal”
For a change, we saw the Nasdaq lag again with the Dow outpacing it for the third straight day, but still trailing severely on a YTD basis.
Earnings season is on deck with JPM beating expectations despite soaring credit losses, while Wells Fargo’s CEO was “extremely disappointed” with its first quarterly loss since 2008.
More earnings reports, up and down, will be forthcoming, but to me it will be interesting to see, how much interference the Fed will run, should the markets start to get wobbly.