Dow And S&P 500 Score New Records

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

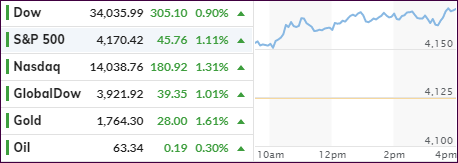
The unchanged line was nowhere near in sight, as the major indexes roared higher after the opening bell and never looked back with the Dow and S&P 500 reaching new all-time highs. Big tech surged and maintained their dominance over SmallCaps, while “growth” outperformed “value.”

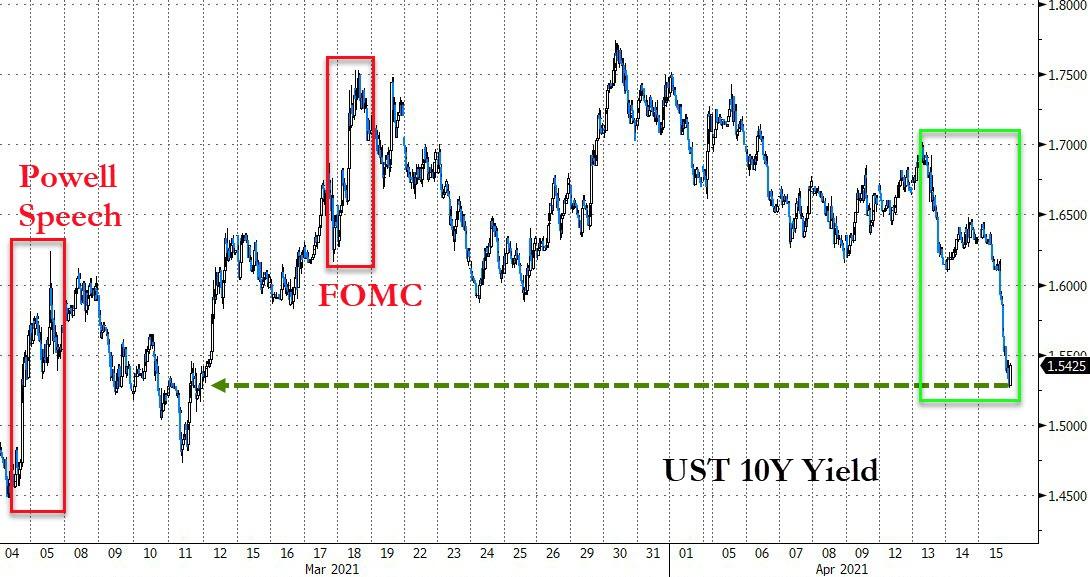
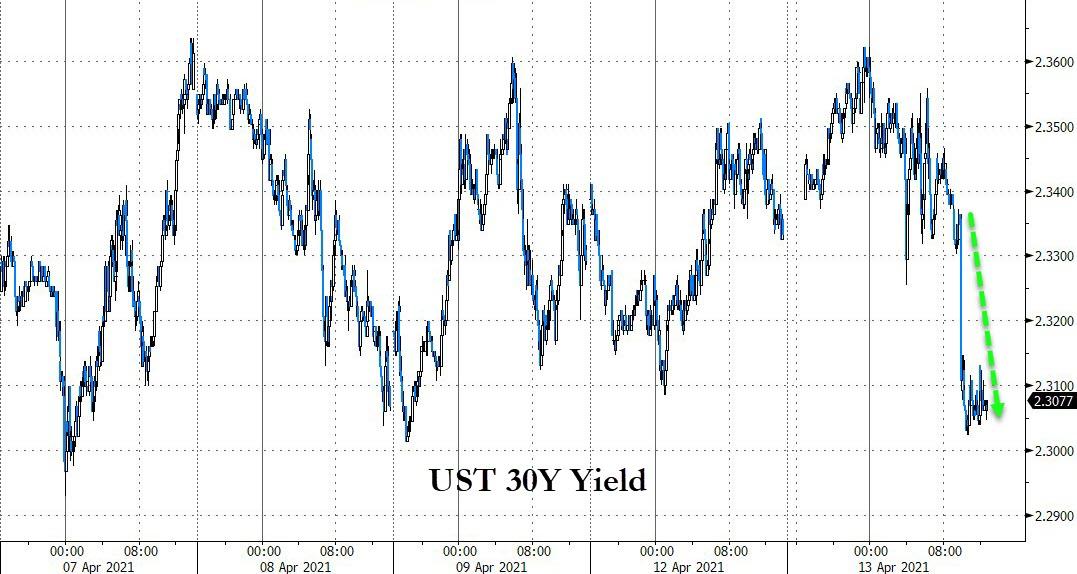
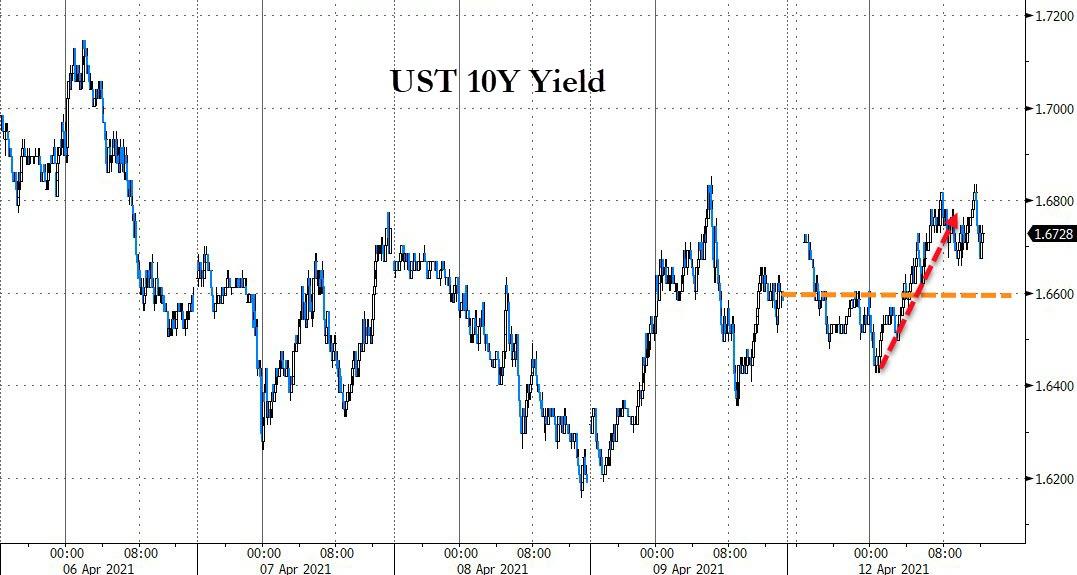
Strong earnings and some economic reports painted a rosy picture for consumer spending and the jobs market. Bond yields dropped with the 10-year sliding to 1.56%, although the US Dollar index trod water.

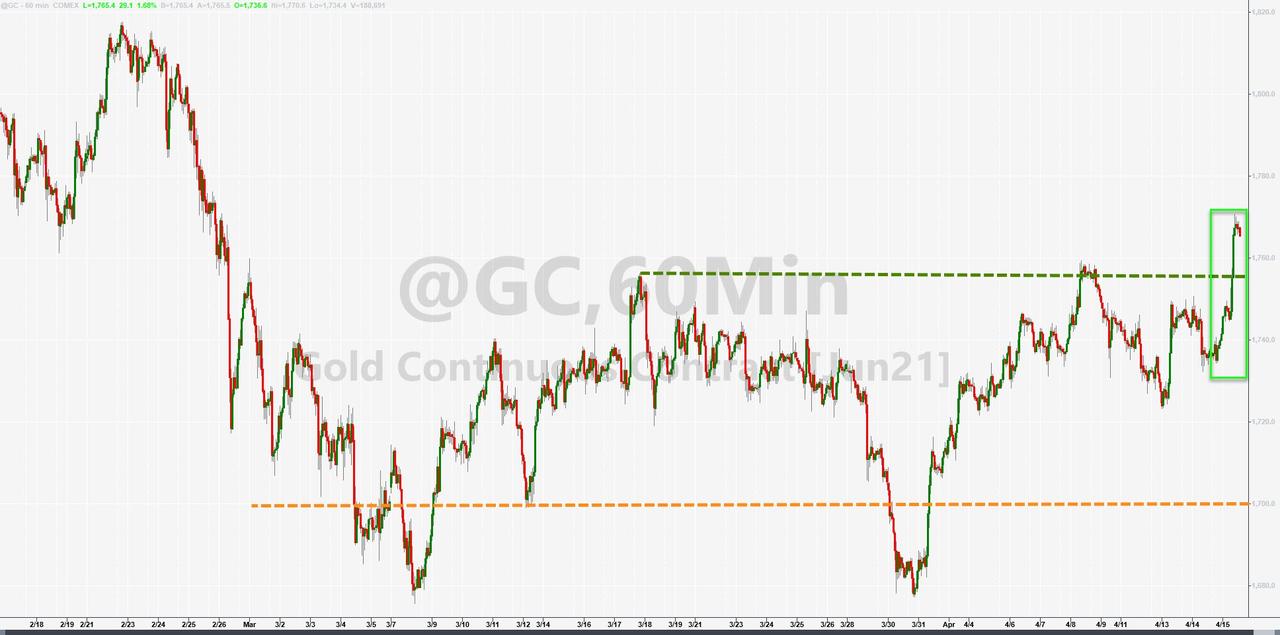
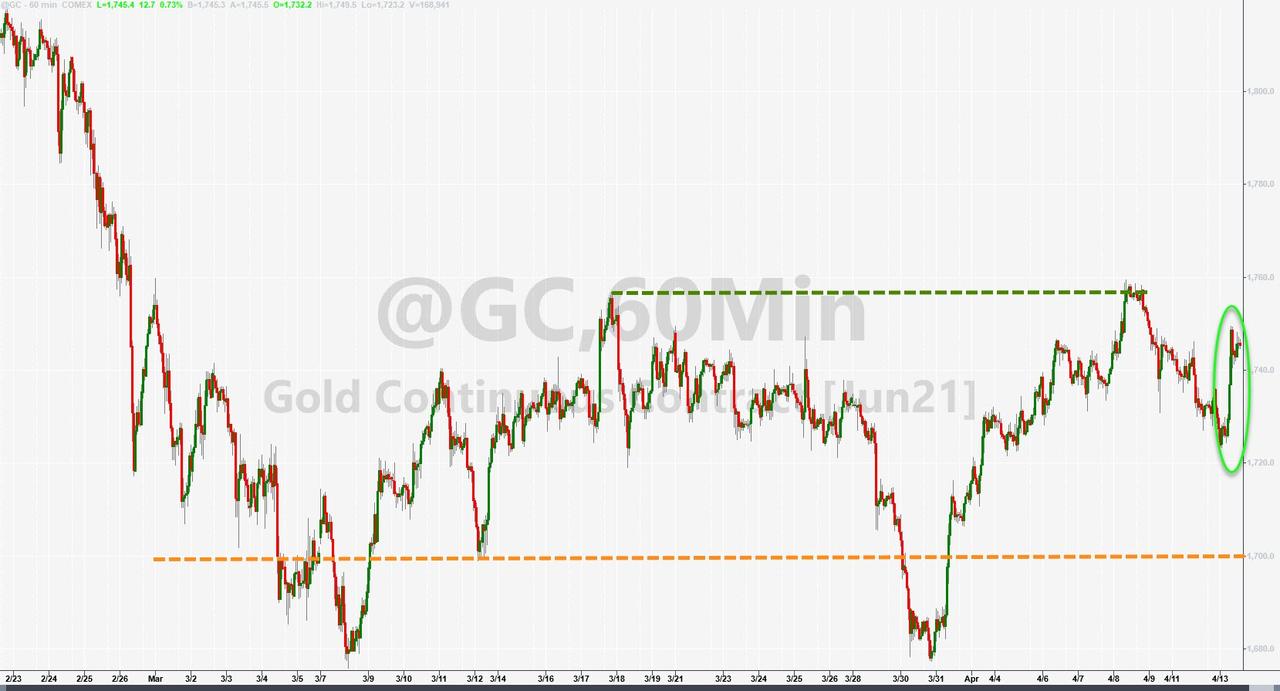
Not just were stocks the beneficiary of the bullish theme, because of lower yields, Gold had its day in the sun and finally rocketed higher by 1.68%, while nearing two-month highs and outperforming even the Nasdaq

Much ado was made about the headline announcing that initial jobless claims dropped back below 600k for the first time since early March 2020. But, as ZH pointed out, this may have been an aberration:

Notably, the drop in claims was largely driven by a 75,645 drop in California… which, as Joe Brusuelas suggests, is indicative of the problems that remain in processing claims, backlogs, and fraud in the states.

Ah yes, the devil is always in the details…

Black Rock’s CEO Larry Fink described the current scenario like this:

I am incredibly bullish on the markets, and you are right to be worried about our deficits. If we don’t have economic growth that is sustainable over the next 10 years — our deficits are going to matter, and they are going to elevate interest rates … I believe because of monetary stimulus, fiscal stimulus, cash on the sidelines, earnings, markets are okay. Markets are going to continue to be stronger.

Optimism despite deficits and consumer inflation, but for right now traders’ minds are noticing nothing but bullish momentum.

Read More
Banks Rally—Tech Cools Off

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

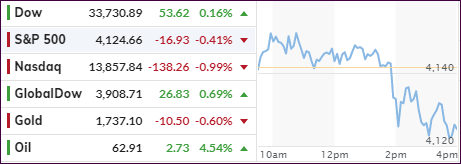
After an early pump, the major indexes lost momentum with the S&P 500 and Nasdaq ending up in the red, while the Dow managed to stay above its unchanged line.

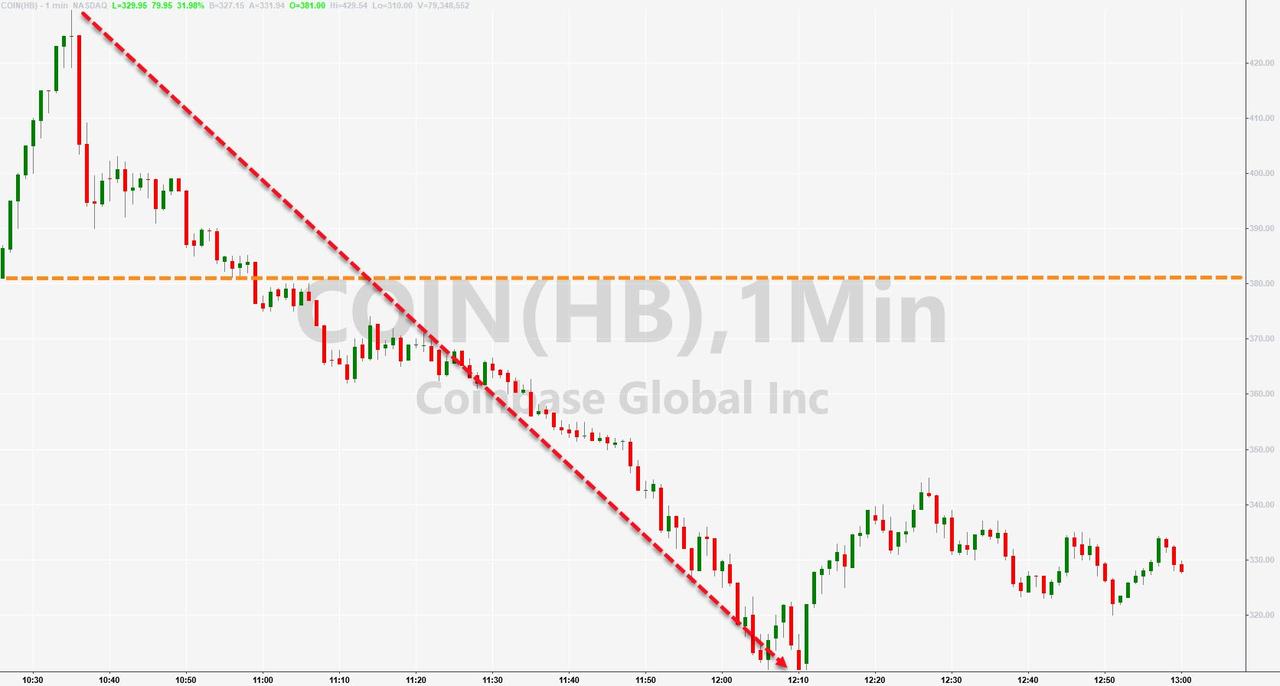
Strong bank earnings helped the financial sector with XLF gaining +0.63%, but that was offset by tech stocks tanking, despite the widely anticipated IPO of Coinbase. The stock rallied at first but then most momentum and closed below its IPO price.

Added the chief strategist of TD Ameritrade:

The first wave of Q1 big bank results look pretty much as strong as most analysts had expected – even stronger actually, it’s possible that we’re in a powerful market that’s in a forgiving mood when it comes to bad news. The path of least resistance for stocks continues to seem to be to go higher, with the market climbing a wall of worries that just doesn’t go away.

On the economic front, we learned that soaring import and export price inflation has finally been noted with the Commodity ETF DBC rocketing +2.30%. None of this was addressed by Fed head Powell speaking before the Economic Club of Washington.

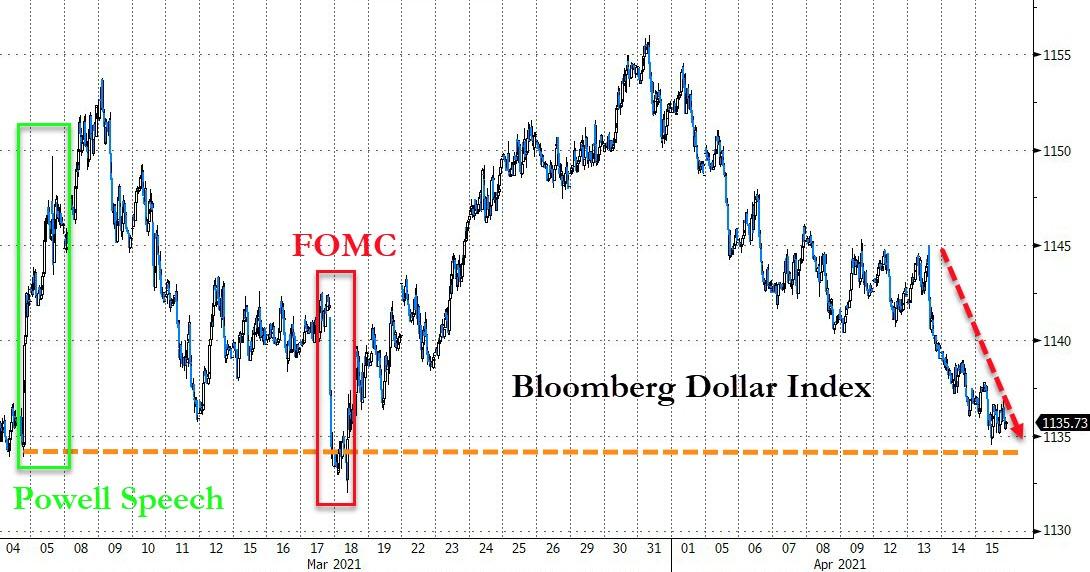
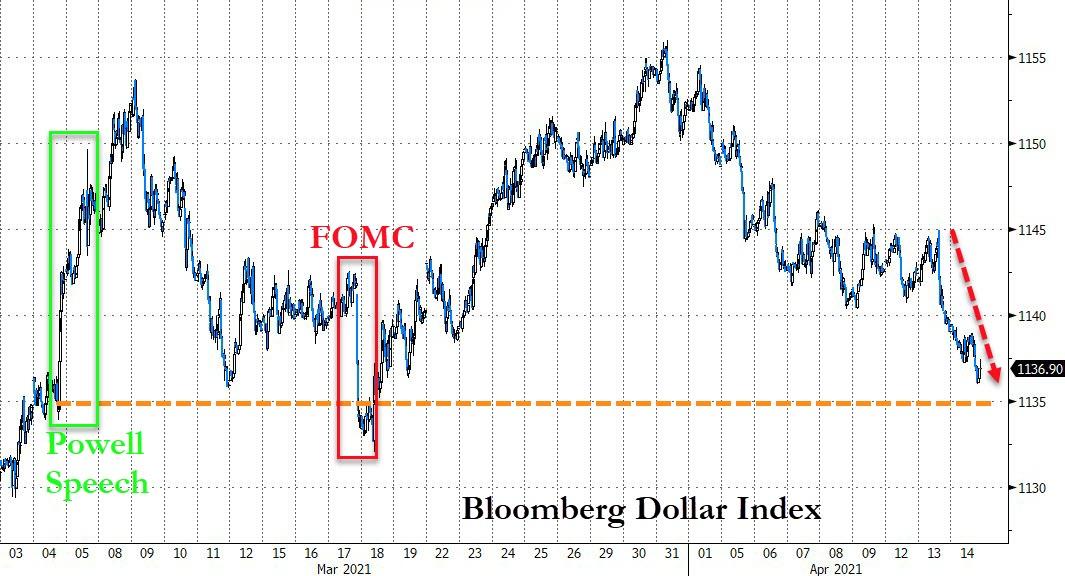
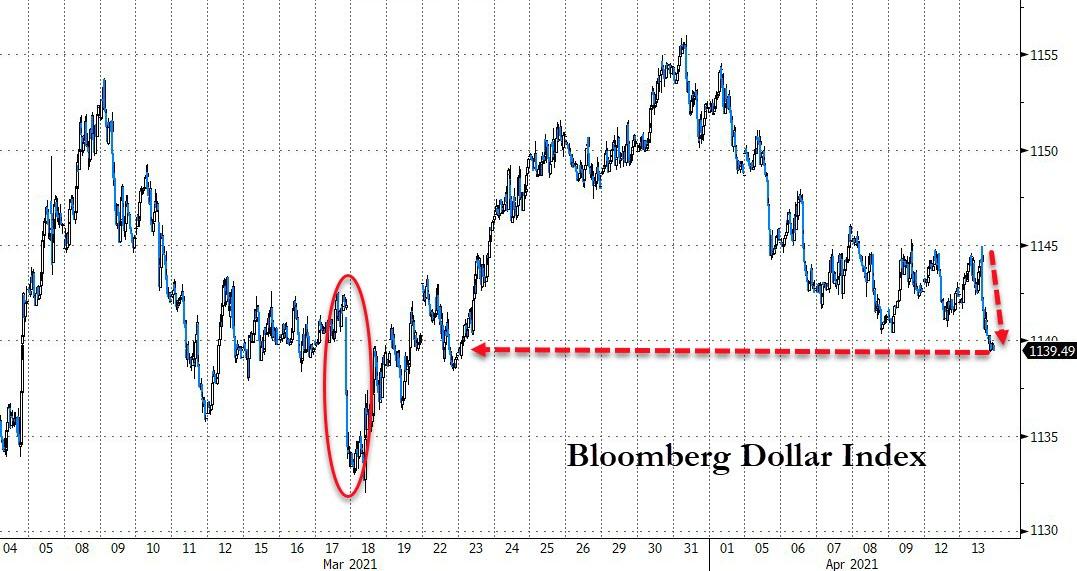
The US Dollar took a dive and approached a key support level, bond yields inched up a bit, and Gold gave back some of yesterday’s gains.

Another session where not much was gained or lost.

Read More

S&P 500 Notches Another Record High

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

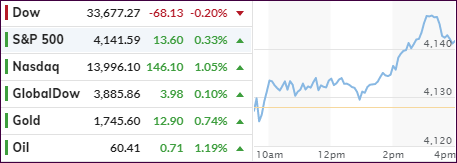
Despite a slow start, the S&P 500 and Nasdaq found some upward momentum late in the session and broke out of a sideways trend with the former scoring a new all-time high.

Anxiety about the Consumer Price Index (CPI) faded with the index rising in March by 0.6% vs. 0.5% expectations. YoY we saw a 2.6% increase, which also was a tad higher than expectations of 2.5%. Overall, traders were relieved that the outcome was not as bad as feared.

Also keeping a lid on prices early on was news that the rollout of Johnson & Johnson vaccine was halted, which kept trading activity on a subdued level. The reason for the pause were investigations of six reported cases of a rare and severe type of blood clot, the FDA stated.

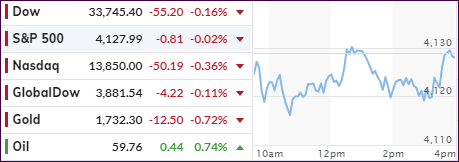
The volatility index (VIX) continued to crawl sideways and has now closed below 20 for 10 straight days, something that has not happened since February 2020, according to ZH. Bonds were bid, meaning yields drifted lower, as did the US Dollar, which allowed gold to have a day with a green close and a gain of 0.74%.

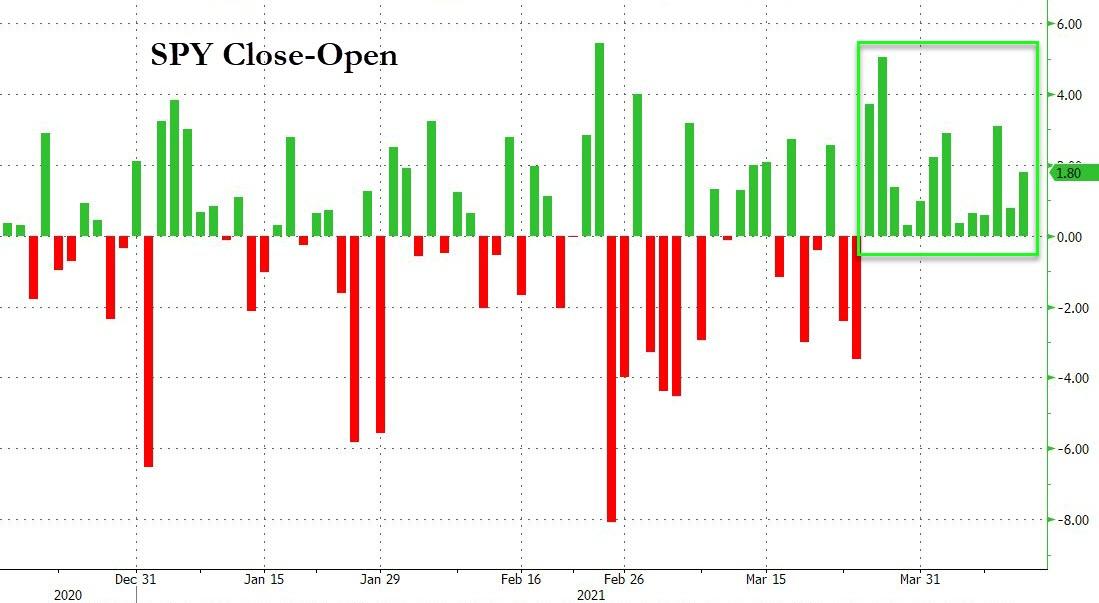
Here’s another record that ZH pointed to, namely that the S&P 500 ETF (SPY) has now closed above its opening price for the 13th day in a row. Since the SPY’s inception in 1993, this has never happened before.

This makes me go “hmm.” Could market manipulation possibly have something to do with it?

Read More

Sliding Into Earnings Season

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

Subdued trading best describes today’s session during which the major indexes operated within a tight range. Despite a red close, the losses were minor, and the activity resembled a lack of motivation due to key inflation data and first quarter earnings awaiting on deck.

Market volatility continued to decline, as seen by the S&P 500 having now traded within a 1% range for the fifth session in a row. Reopening optimism was a major contributor with the VIX “fear” gauge trading below 18, a level last seen over a year ago.

The current focus is on tomorrow’s CPI release, which is considered the benchmark for measuring inflation, although the index is faulty in that it does not include day-to-day items that we all know have increased in price.  

Fed chair Powell made an appearance on “60 Minutes” last night and had the following to say:

We want to see inflation move up to 2% — and we mean that on a sustainable basis, we don’t mean just tap the base once, but then we’d also like to see it on track to move moderately above 2% for some time.

And then what? I disagree with his statement, because it makes you think that inflation can be controlled or simply turned off, once it exceeds or reaches a desired number. Unfortunately, history is riddled with evidence showing that once the genie, aka inflation, is out of the bottle, you can’t put it back in.

For the day, we saw 10-year bond yields treading water, the US Dollar meandering aimlessly, while gold slipped 0.72%.

Read More

ETFs On The Cutline – Updated Through 04/09/2021

Ulli ETFs on the Cutline Contact

Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.

This report covers the HV ETF Master List from Thursday’s StatSheet and includes 312 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 245 (last week 246) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.

Take a look:                                                                   

The HV ETF Master Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms. If you missed the original post about the Cutline approach, you can read it here.      

ETF Tracker Newsletter For April 9, 2021

Ulli ETF Tracker Contact

ETF Tracker StatSheet          

You can view the latest version here.

LEAPING INTO THE CLOSE

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

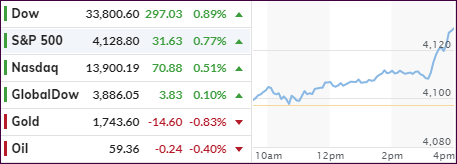
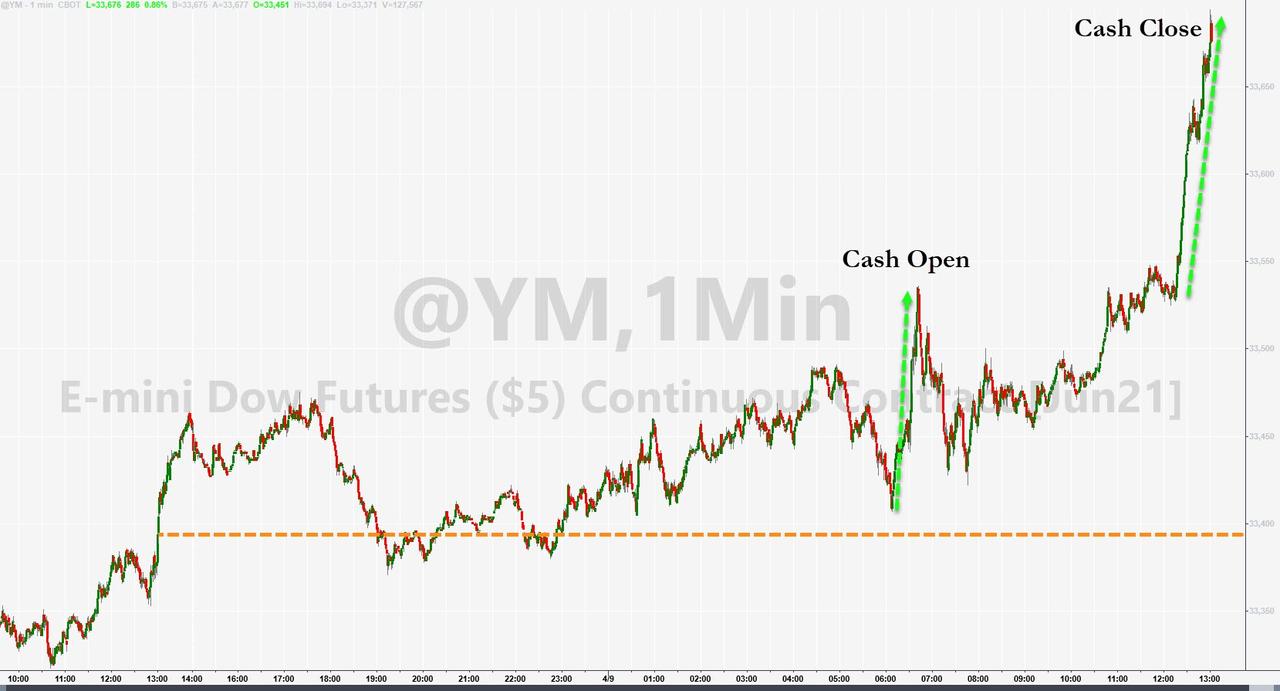
A last hour ramp pulled the major indexes out their sideways pattern and pushed them into a solid green close.

For a change, the Dow led the pack by scoring another record high with the Nasdaq only in 3rd place, while SmallCaps rose moderately.  

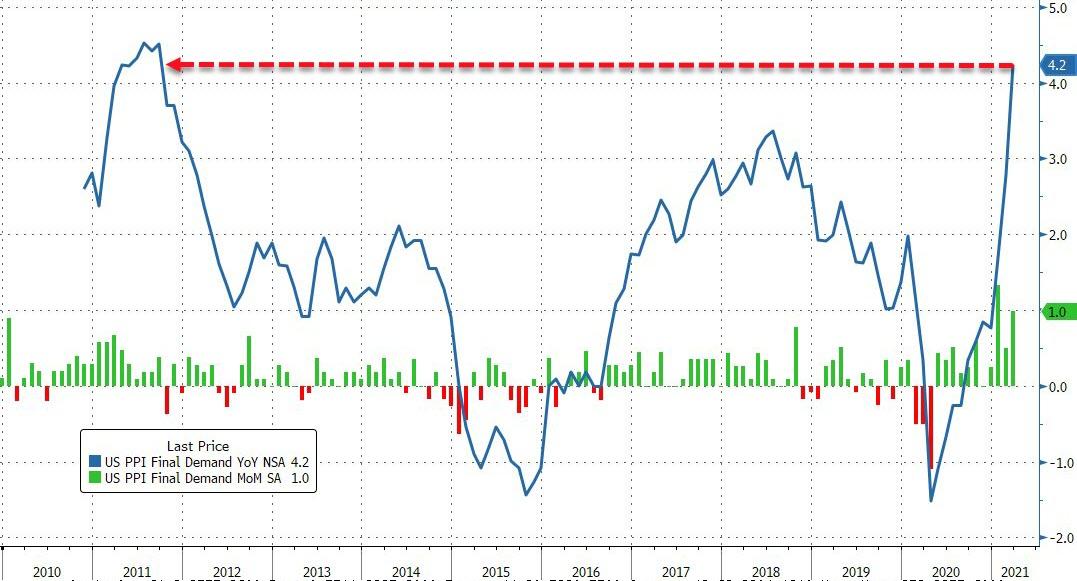
In economic data, and after an unprecedented delay, the BLS finally disclosed a huge jump in March Producer Prices, up 1% MoM vs an expected 0.5%. Far worse was the YoY number, which amounted to a stunning rise of 4.2% vs. 3.8% expected. As ZH pointed out, this is the 11th month in a row of rising PPI.

Inflation keeps heating up, and I believe it will accelerate, while the Fed has not acknowledged any of it, but they will have to once it is passed on to consumers.

We’ll need to wait till next week to see if the next CPI reading is already signaling this process. However, the CPI is a number that does not truly reflect price increases for everyday items.  

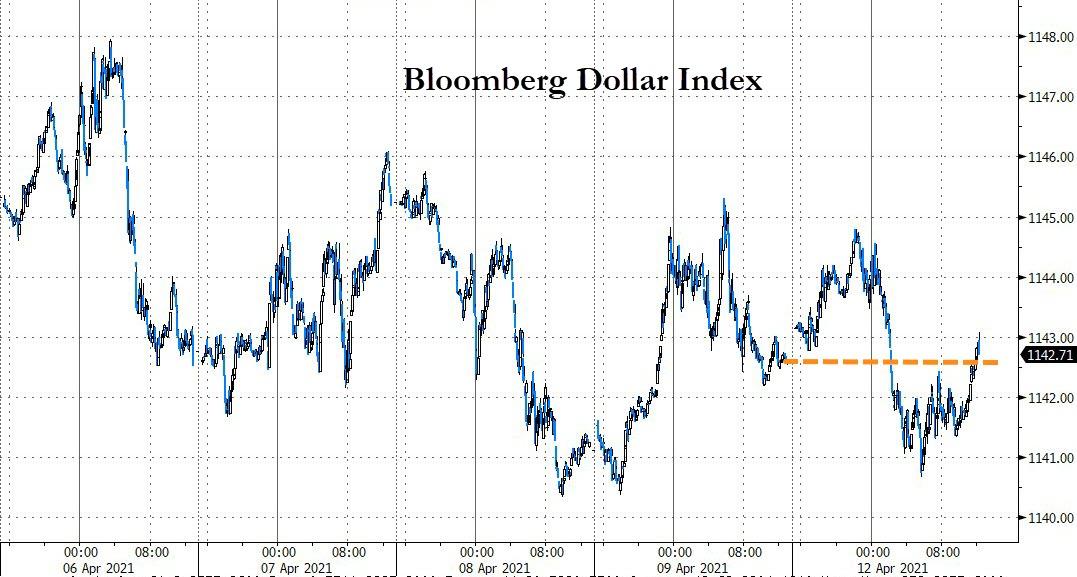
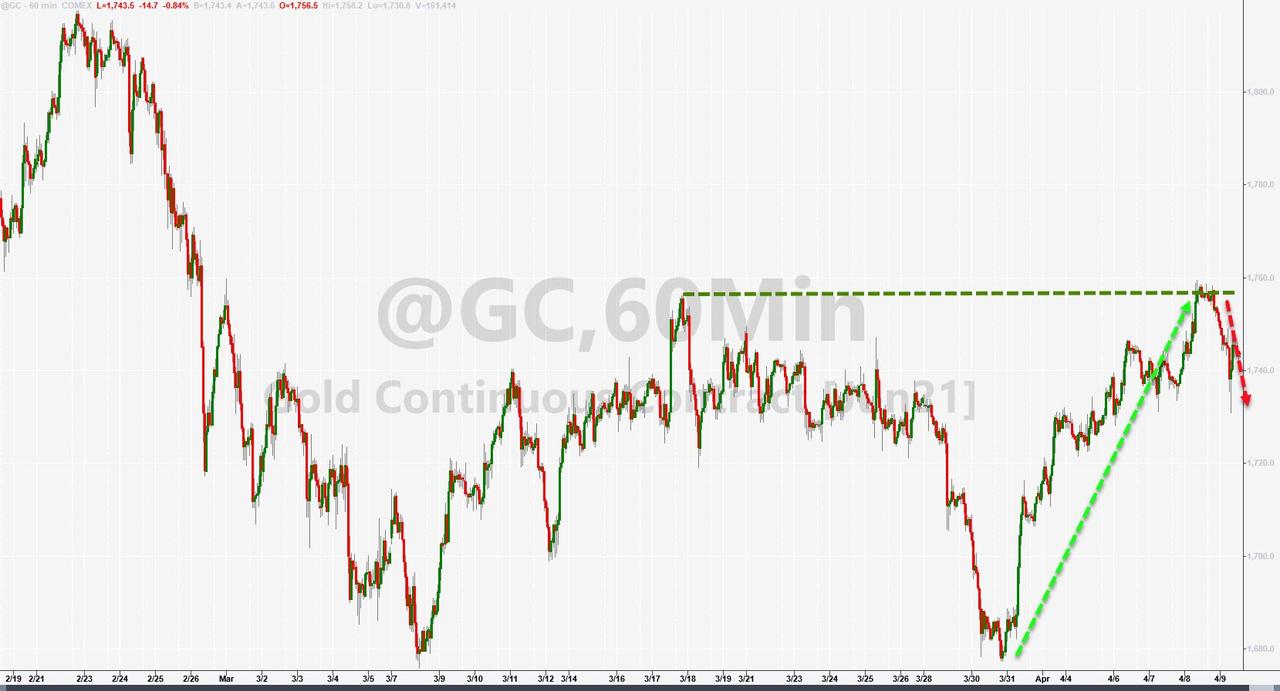
The 10-year bond yield rose slightly to the 1.65% level, while the US Dollar bounced off yesterday’s lows, keeping Gold in check with the precious metal slipping -0.84%.

Hope reigns supreme that the markets can handle inflation and rising bond yields, as the chief investment officer at Raymond James noted:

Contrary to headlines, rising interest rates, healthy levels of inflation, and an eventual Fed rate hike are not necessarily market negatives.

That is until inflation rears its ugly head, a result of reckless money printing, and the bond market starts to puke as yields roar.  

Read More