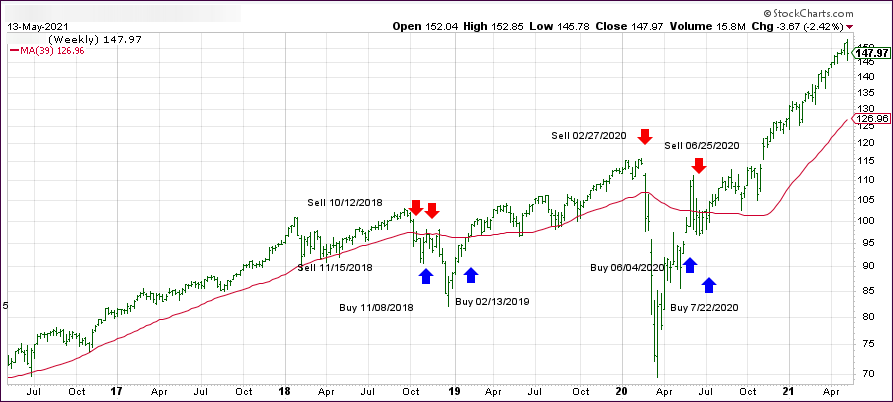
[Chart courtesy of MarketWatch.com]
- Moving the markets
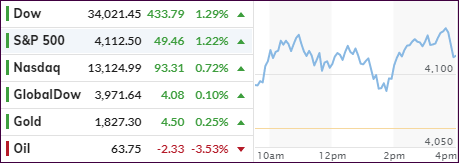
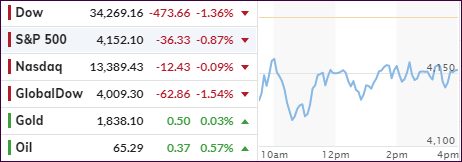
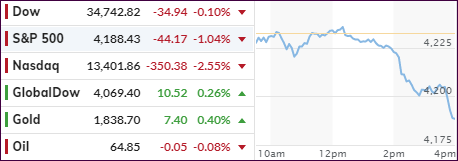
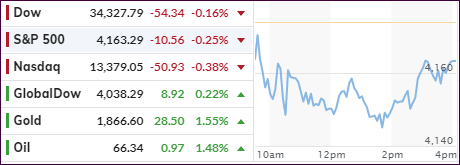
Last week was a roller coaster ride with the S&P 500 dropping some 4% in the first three trading days but making up most of it during the last two and ending down only 1.4%.
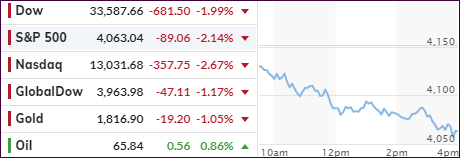
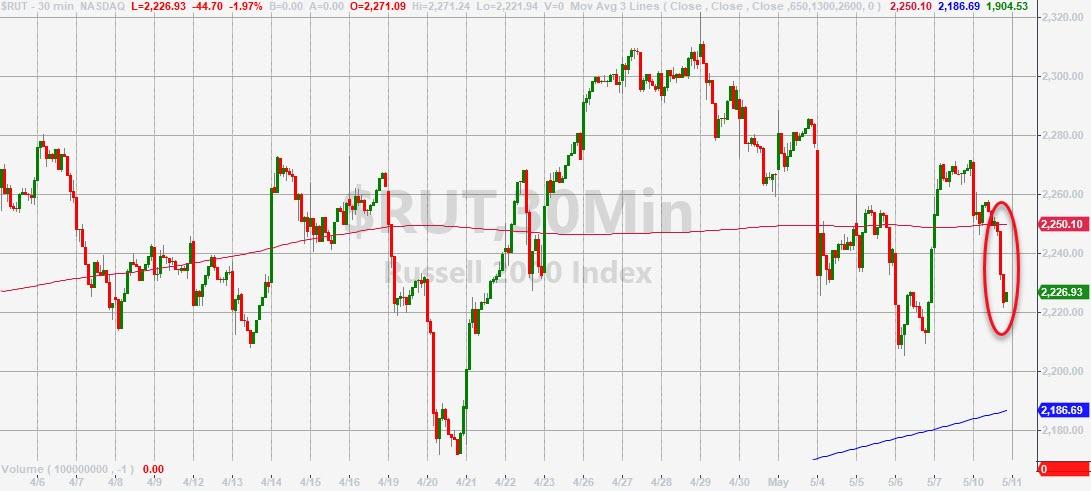
The Nasdaq fared the worst and continued this trend this morning by leading the other two major indexes to the downside, as an early drop put traders on edge. The rotation out of growth stocks kept punishing the tech sector while benefiting the cyclical and value arenas.
Today’s action showed that Small Caps and QQQs were on the selling block, losing 0.64% and 0.61% respectively, whereas the value ETF RPV eked out a 0.52% gain, along with the Small Cap Value fund IJS, which added 0.58%.
In the end, however, this afternoon’s bounce-back severely reduced the early morning losses, making the red numbers appear less daunting.
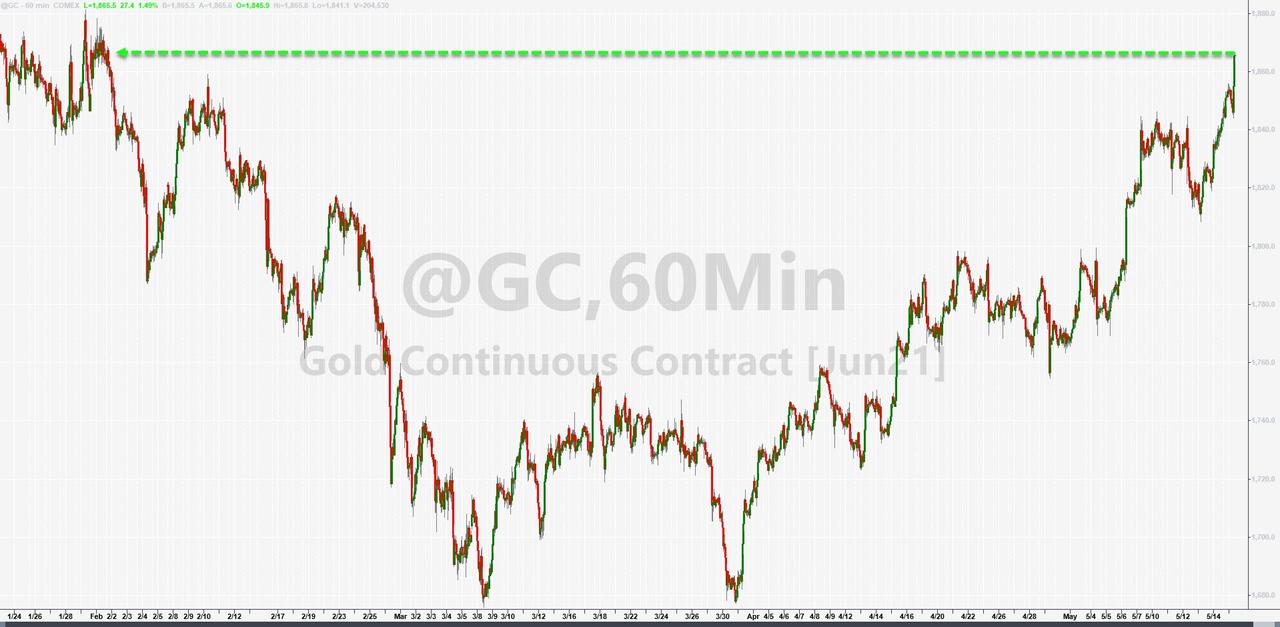
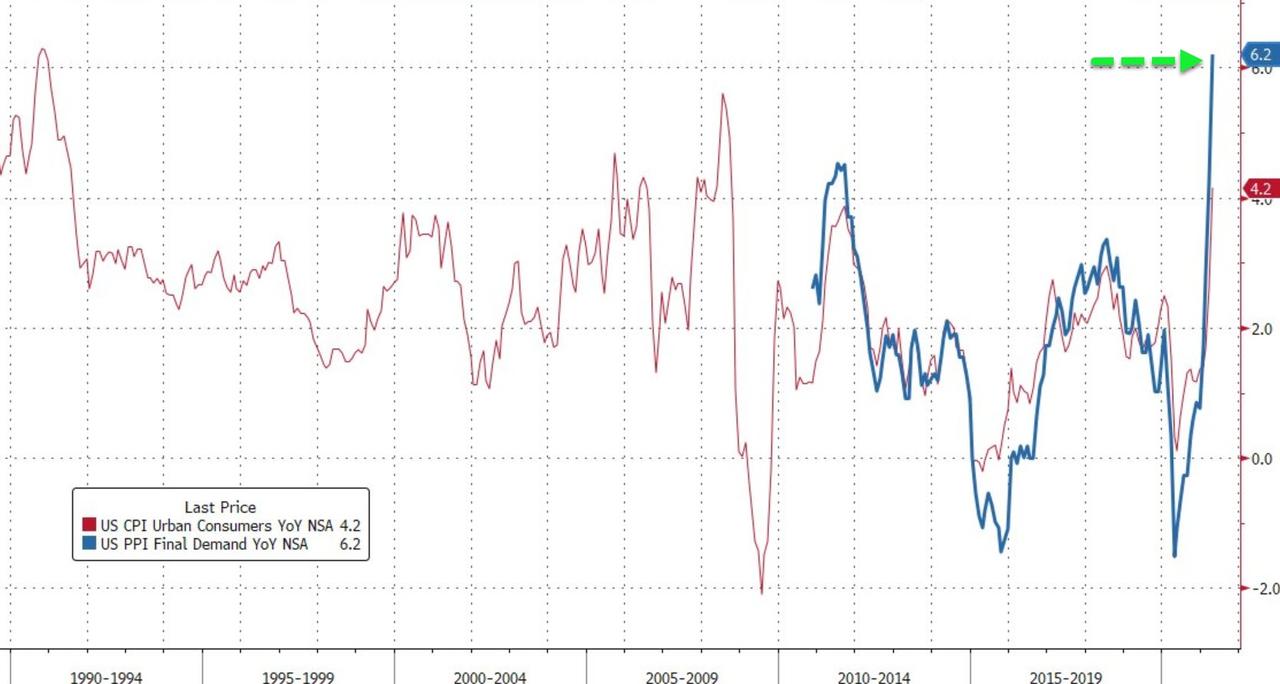
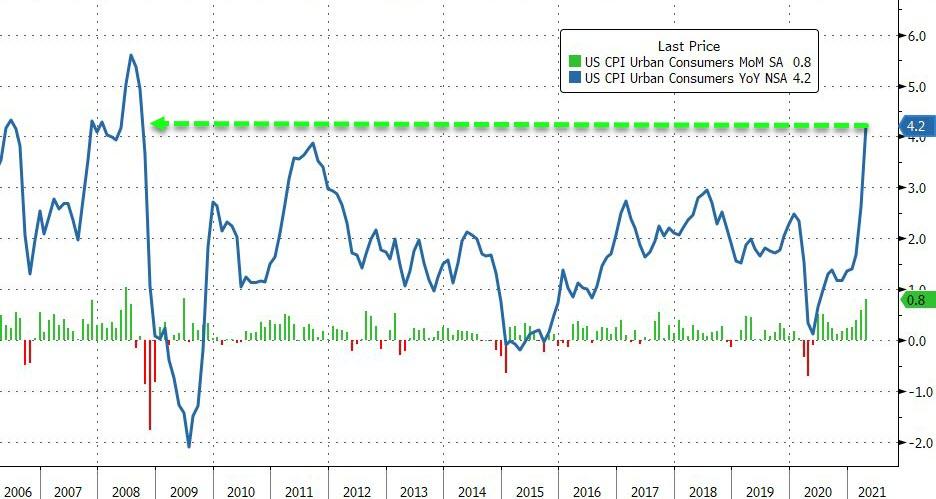
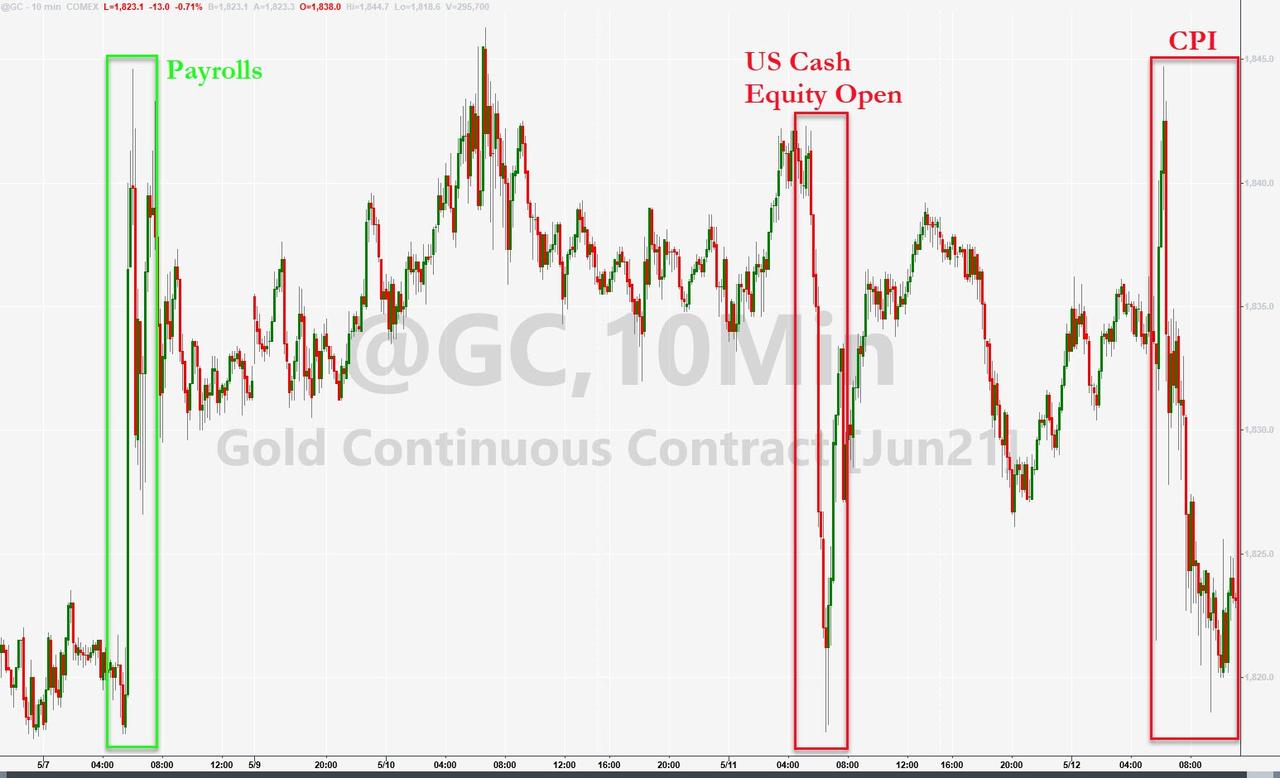
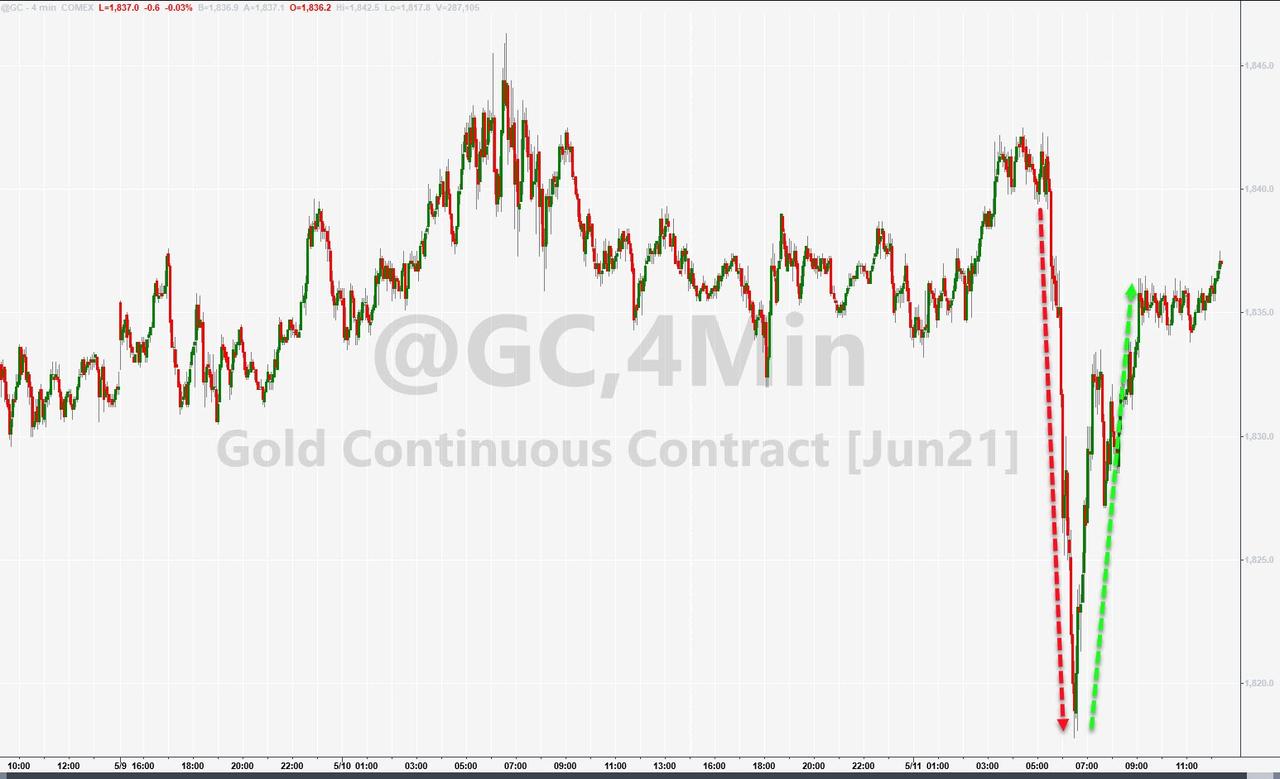
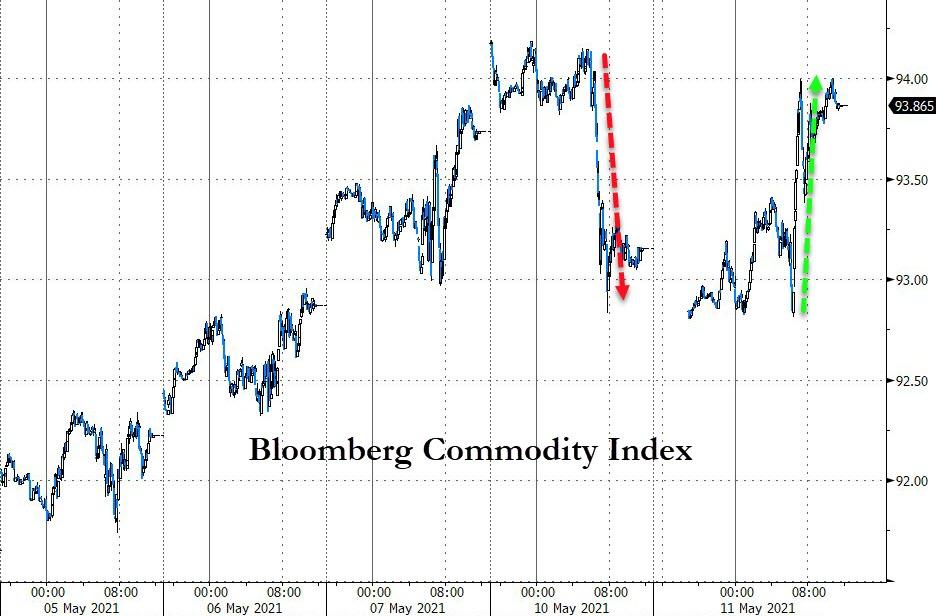
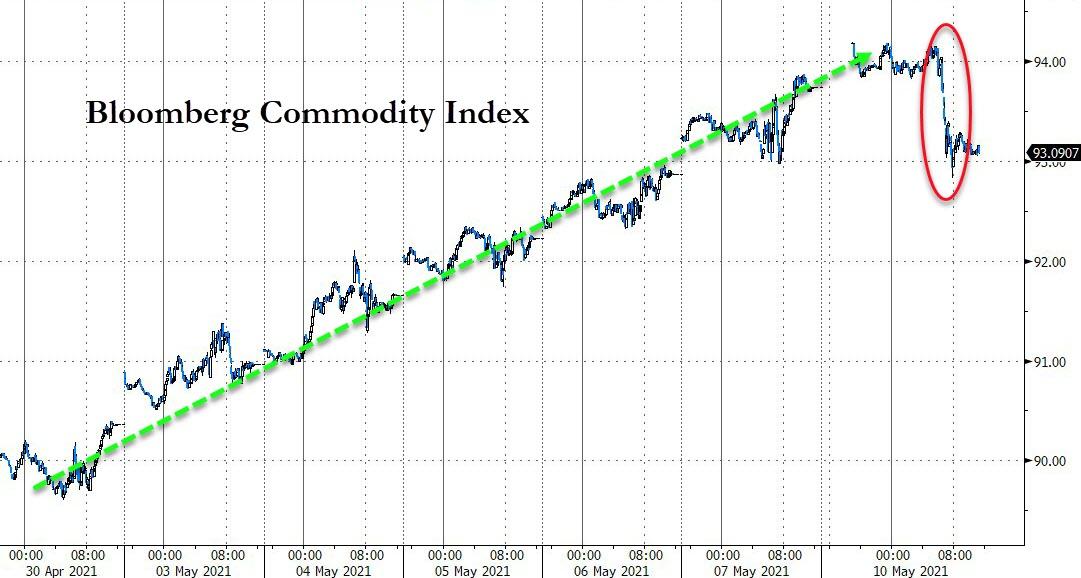
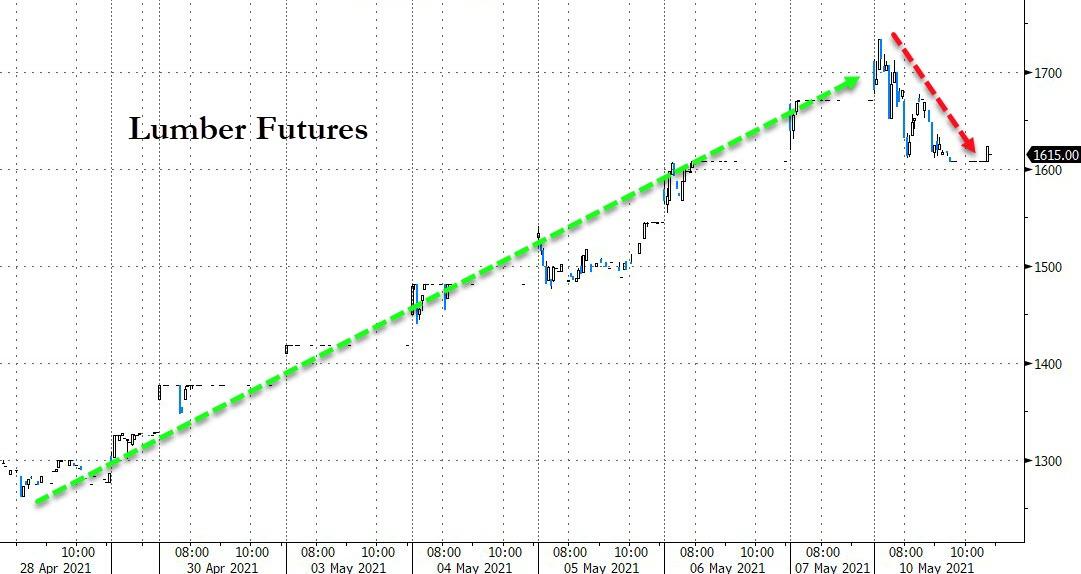
Last week’s inflationary numbers of the CPI/PPI releases finally caused some discomfort, which explains not only the above rotations, but also that Gold may after all still have validity in investors’ portfolios. That meme was on everybody’s mind today, as the Gold ETF GLD rallied not only 1.18% but also recaptured its long lost $1,800 level and closed at its highest point since January.
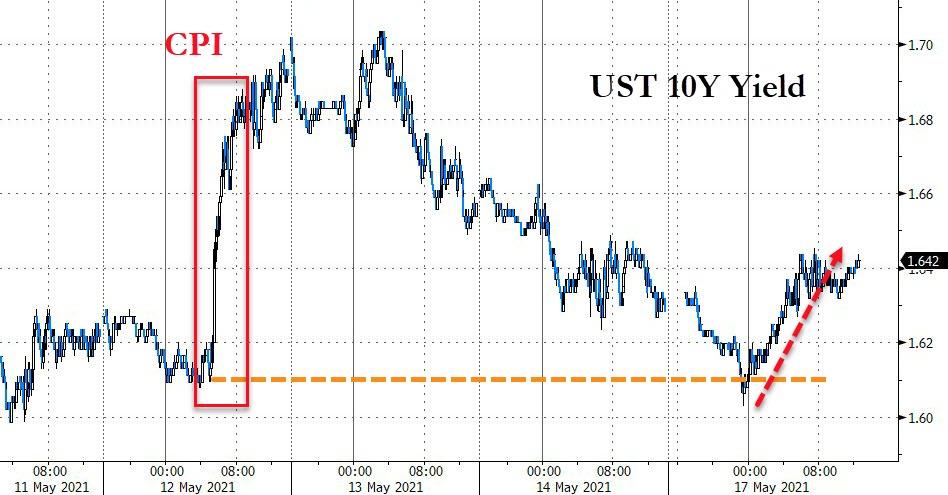
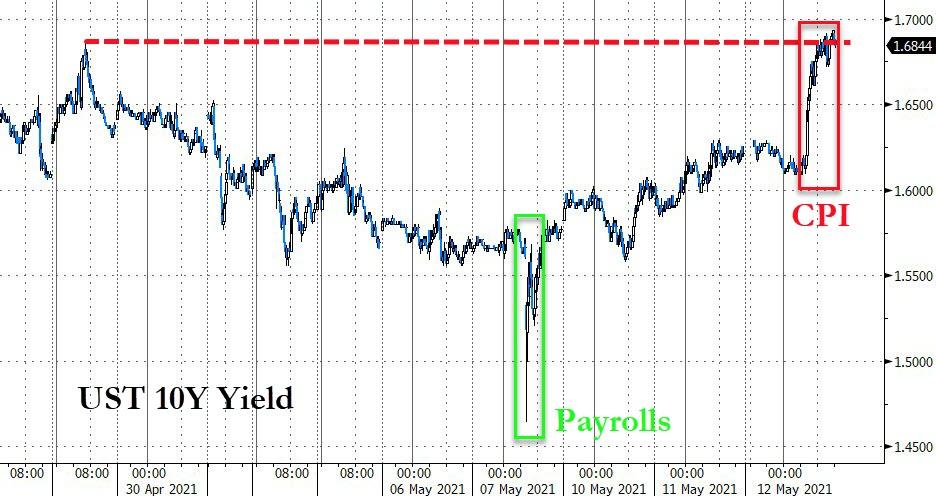
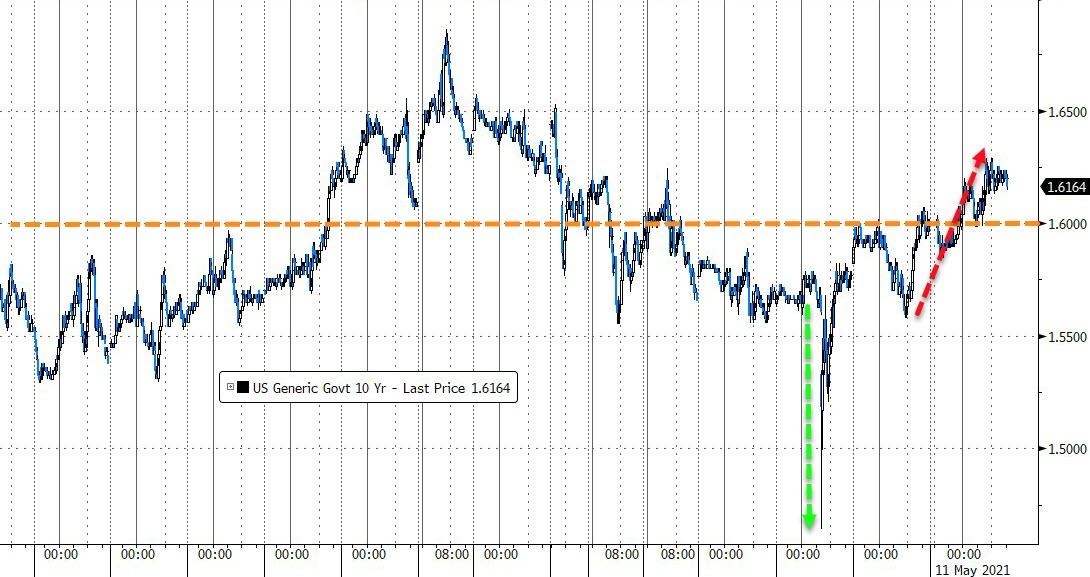
The 10-year bond yield roundtripped and inched higher into the close after an early morning drop. However, we’re still below the highs of last week, which exceeded the 1.7% level when the CPI number was released.
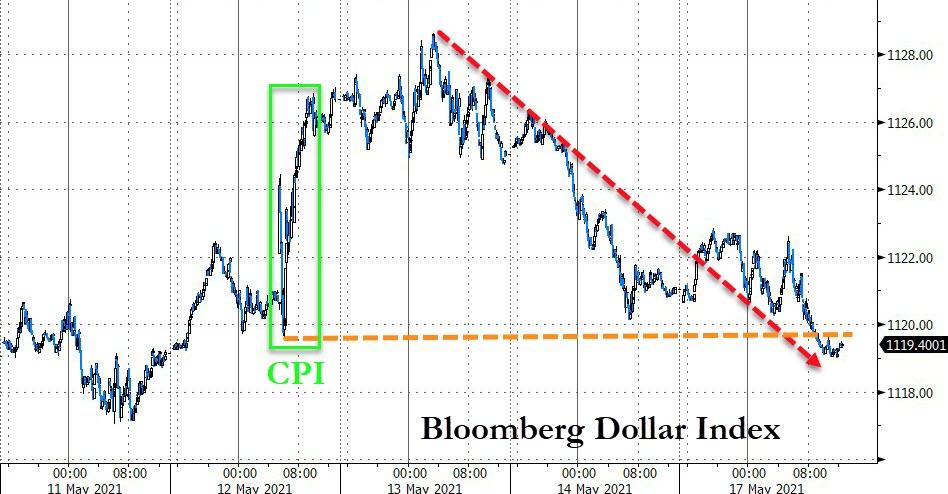
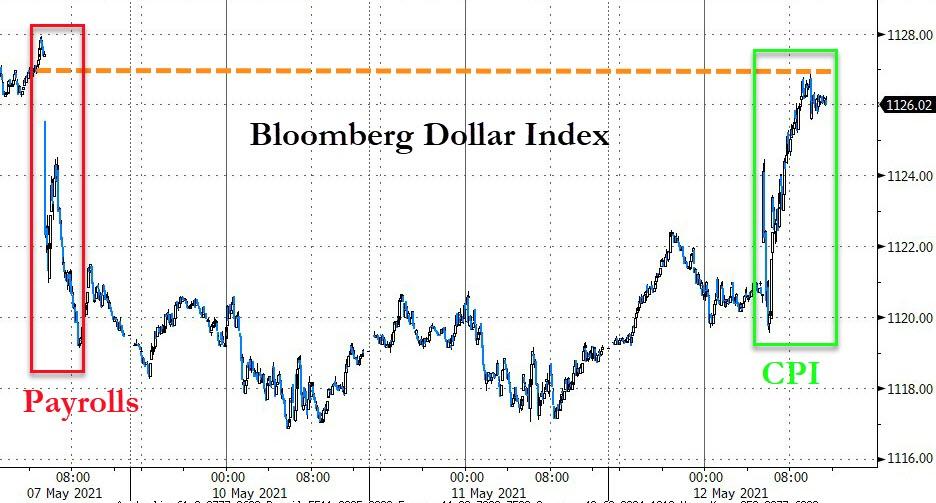
The US Dollar Index eased up after last week’s rally and settled at a level that is close to where it was before bond yields ramped higher last Wednesday.
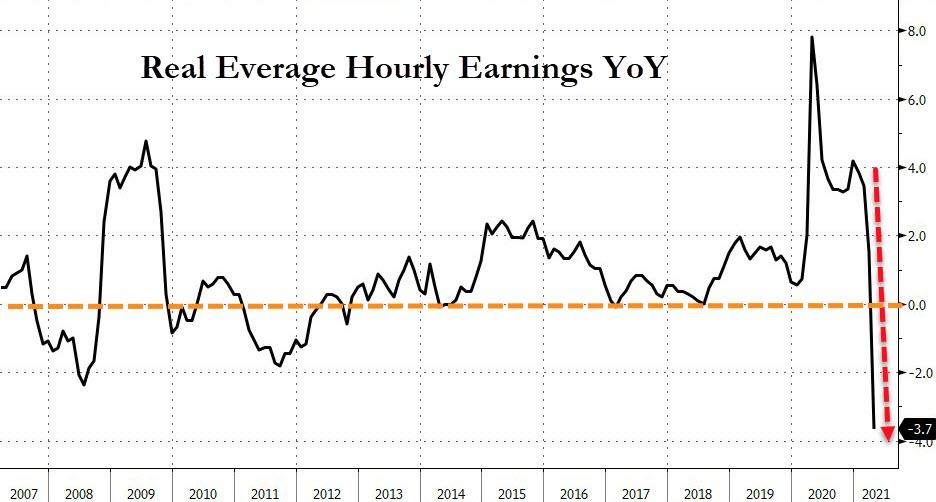
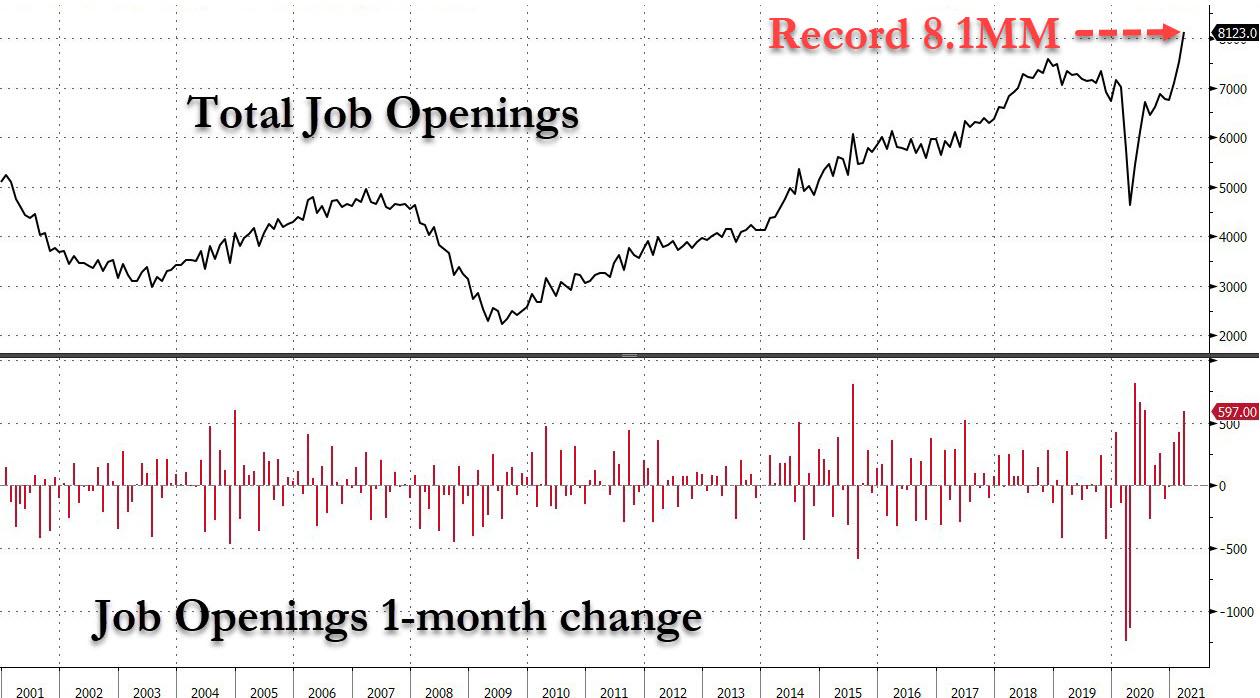
With inflationary forces (CPI/PPI) being opposed by an economic slowdown (disappointing job creations), it will be just a matter of time before the dreaded “S” word, as in Stagflation, will be uttered by the mainstream media.
That leaves me pondering: “how will equities react?”
Read More