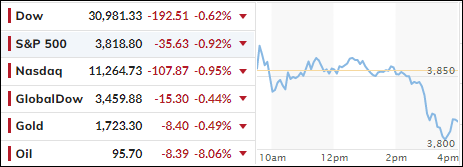
[Chart courtesy of MarketWatch.com]
- Moving the markets
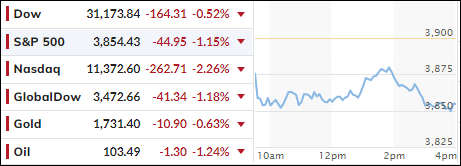
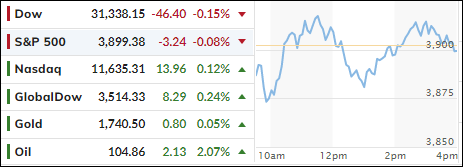
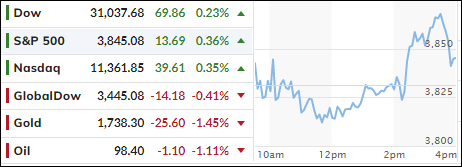
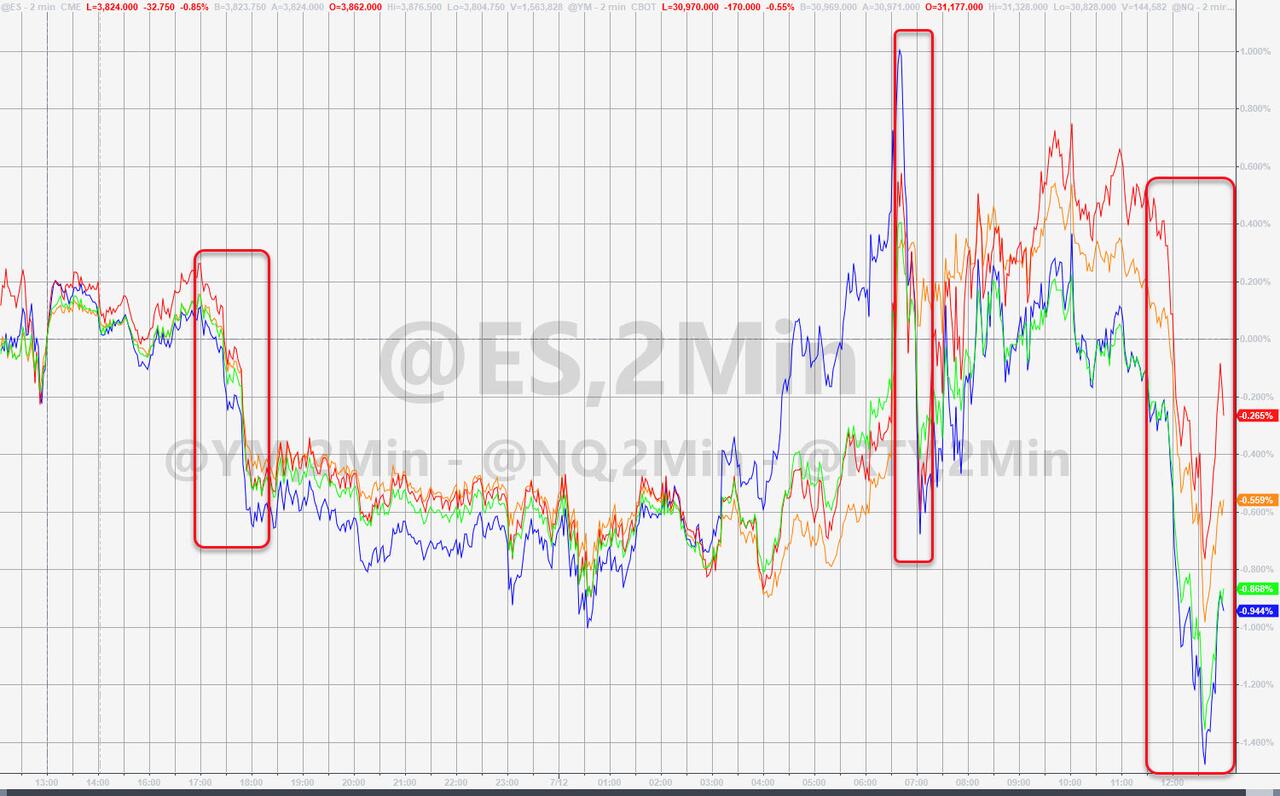
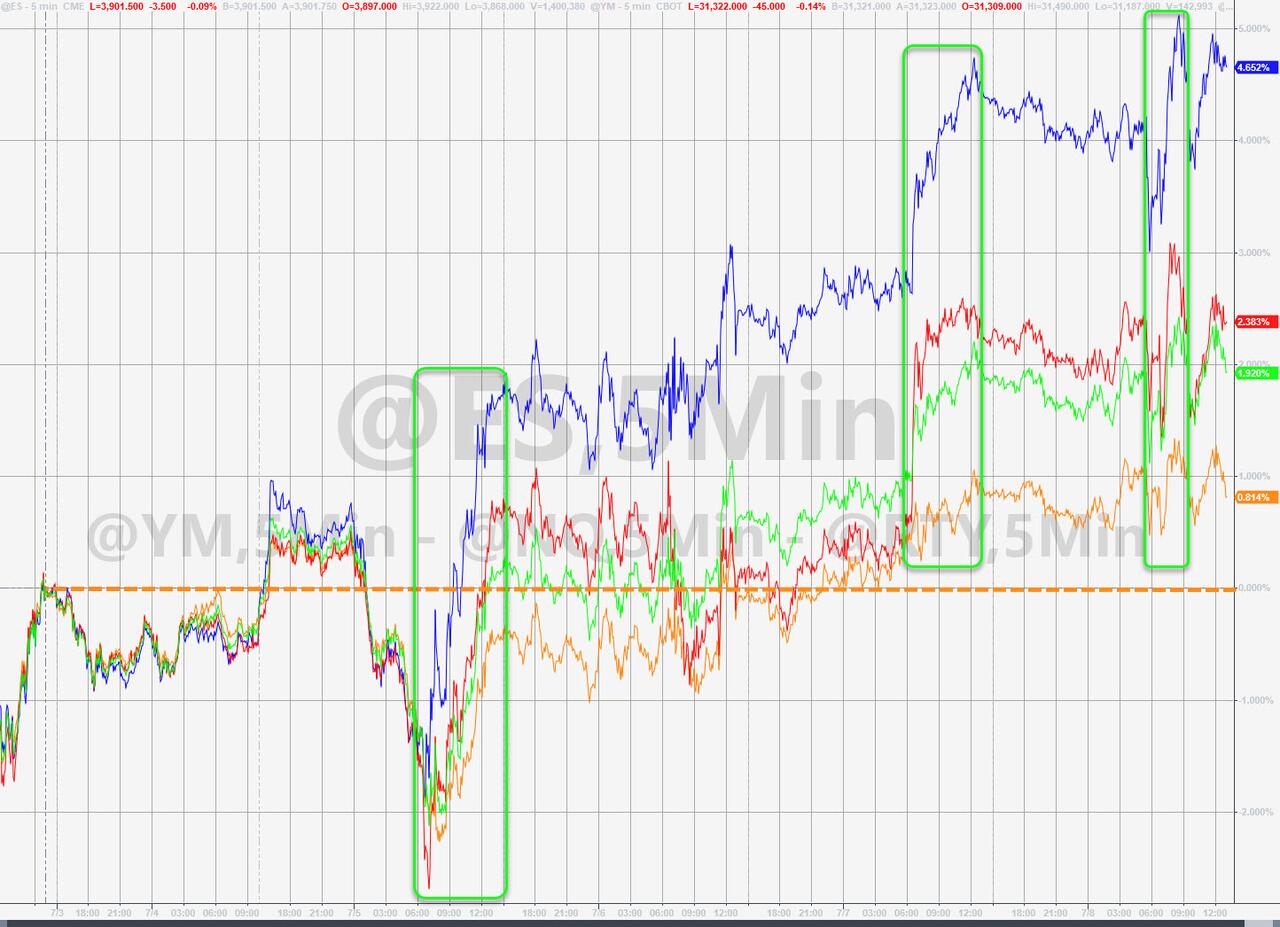
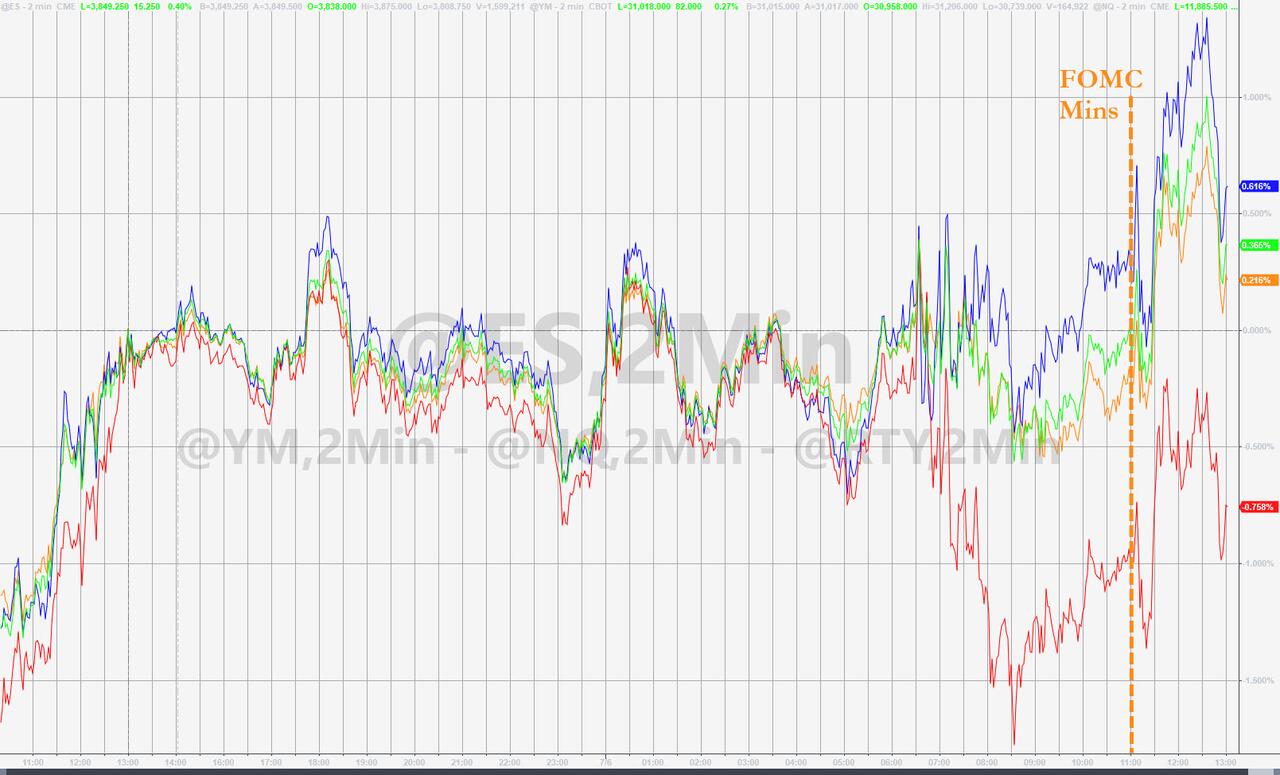
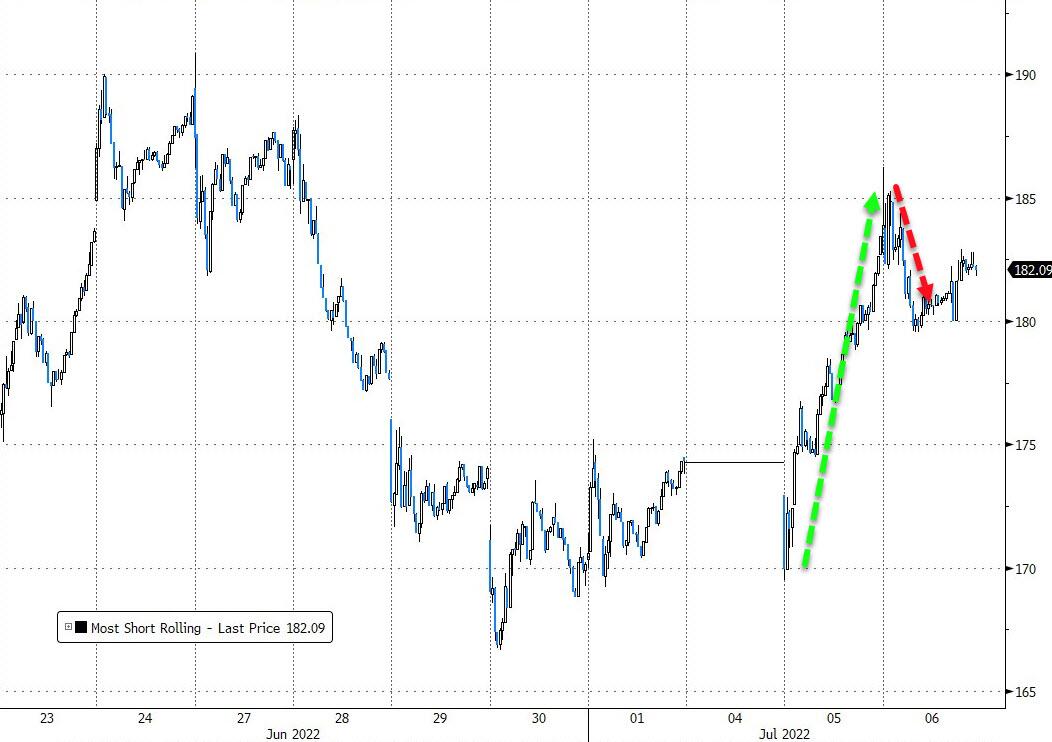
After hesitantly spending some time above their respective unchanged lines, bullish momentum, as insignificant as it was, disappeared, and the major indexes staged a turnaround and dumped into the close.
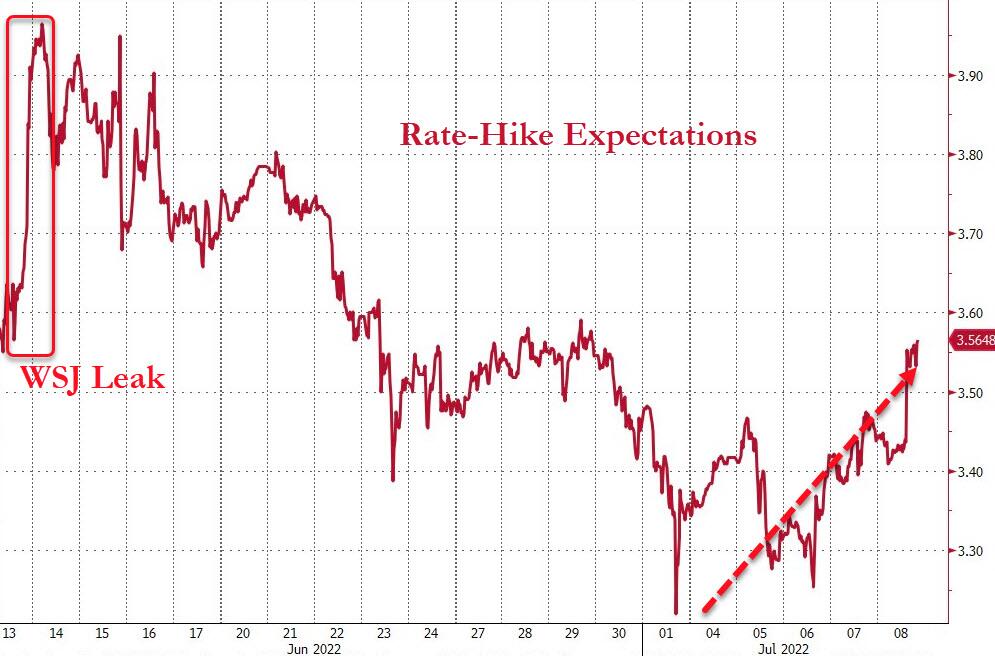
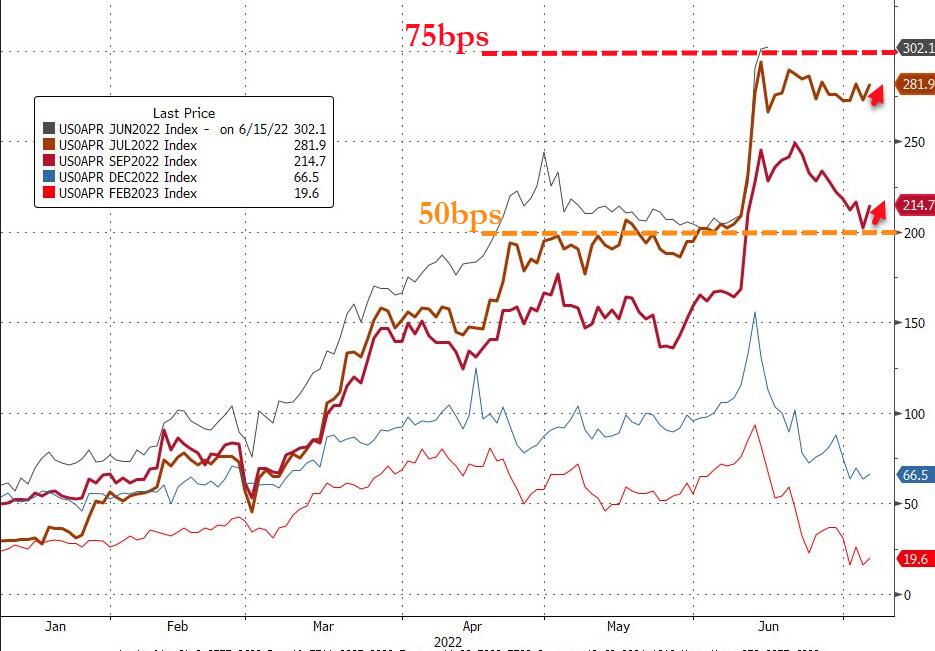
It was a lackluster session with the same old standby worry, namely economic growth, as Wall Street braced itself for tomorrows key inflation data via the release of the CPI. It’s no secret that growth is slowing, and Central Banks remain in inflation-fighting mode, which means more rate hikes.
The earnings season started well with PepsiCo’s report card and forward guidance turning out better than expected. Keep in mind though, that those businesses which do not pass on their higher input costs will have deal with squeezed profit margins, which will negatively affect their stock prices.
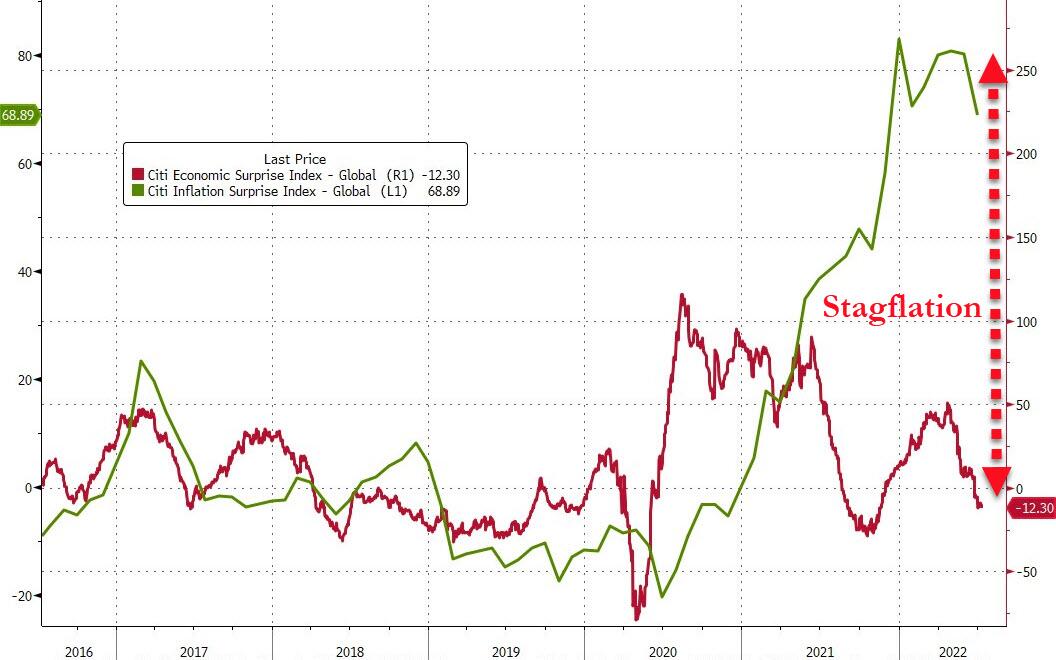
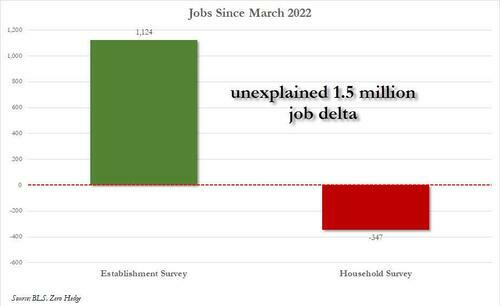
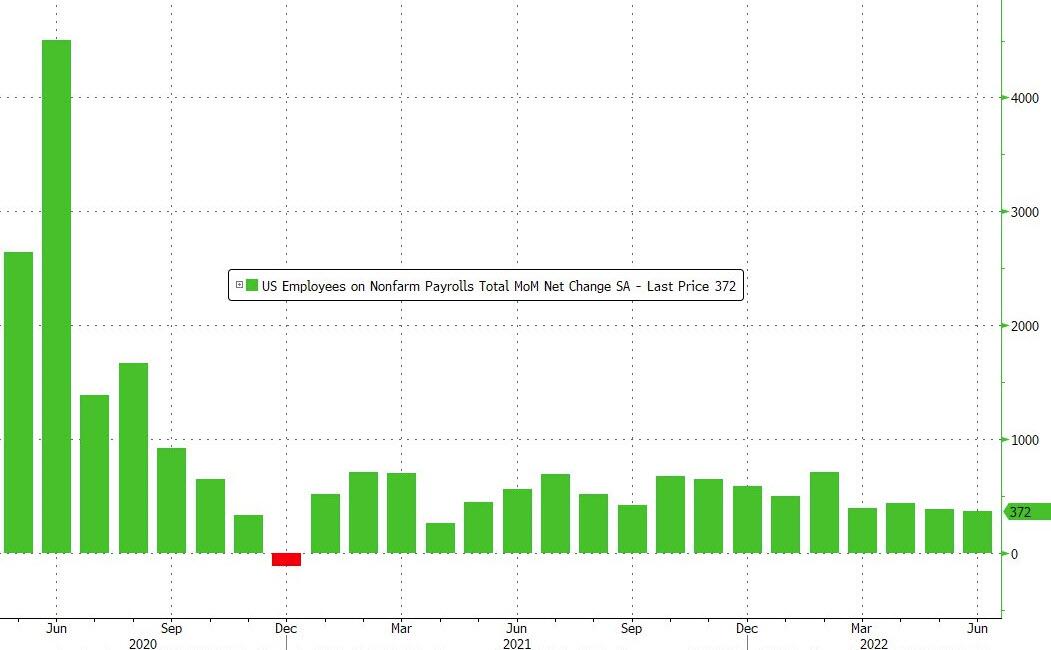
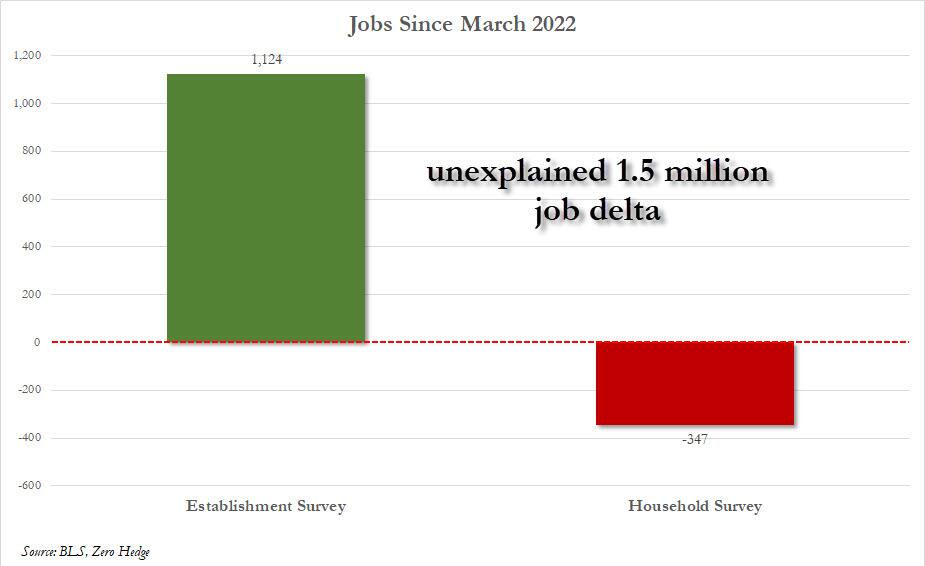
So far, the case for Stagflation remains on deck, as inflation is consistently hotter than expected and economic growth weaker than expected, according to ZeroHedge.
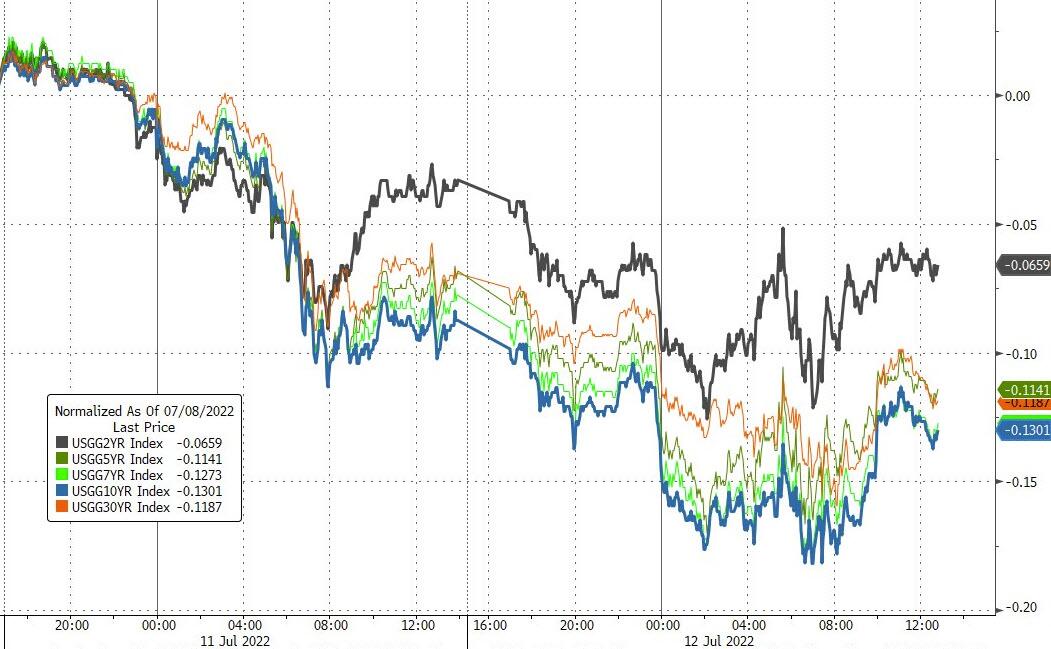
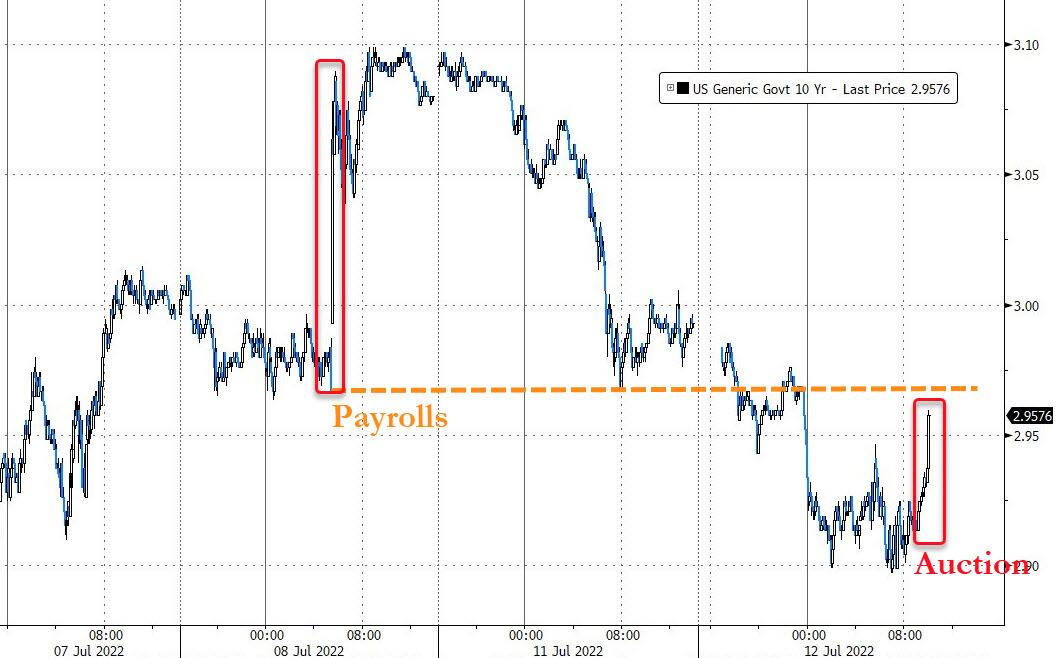
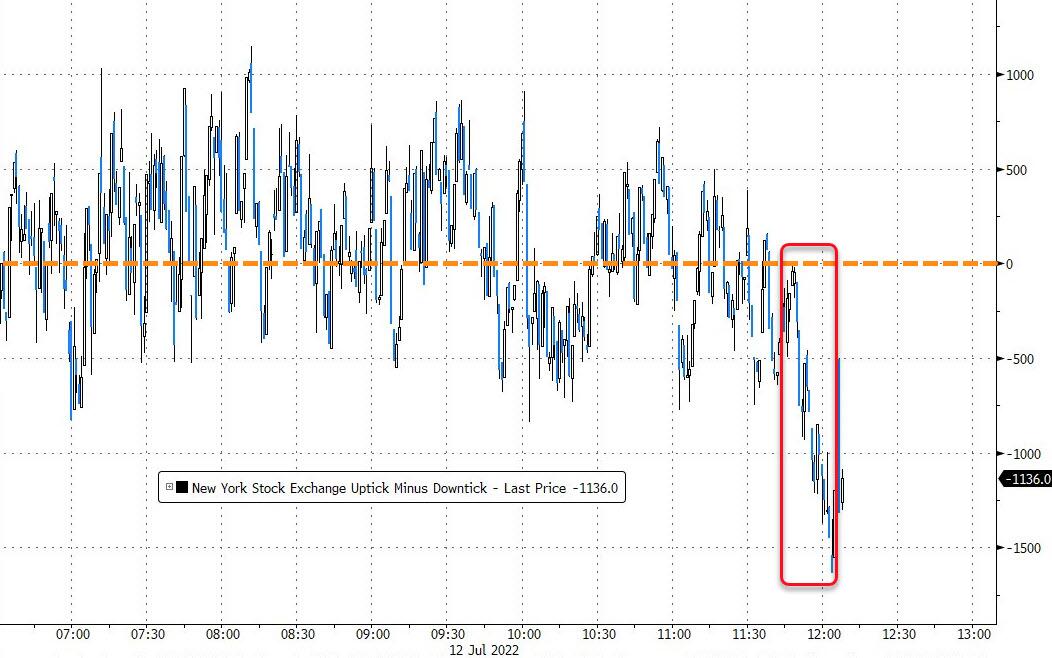
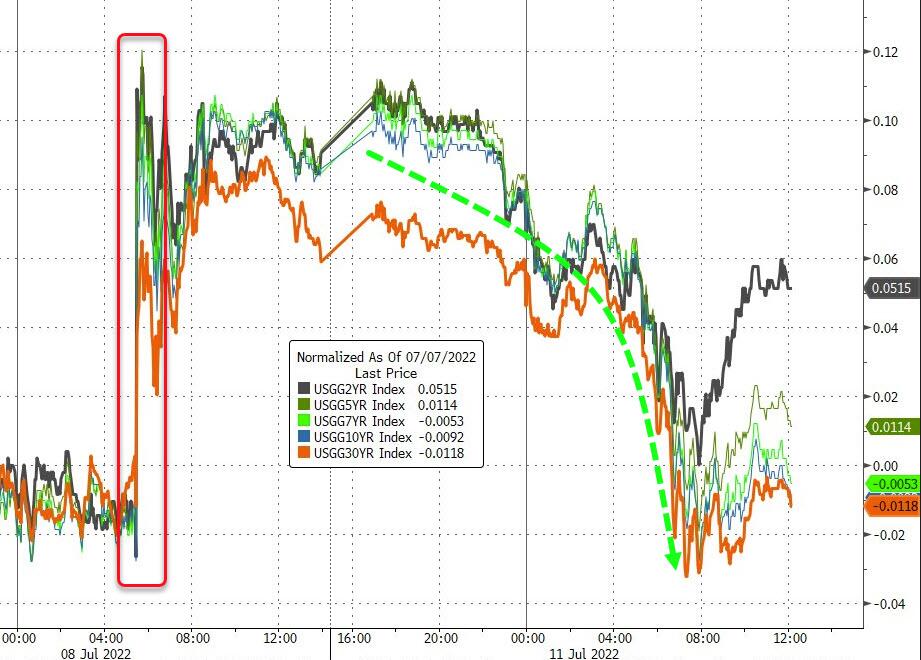
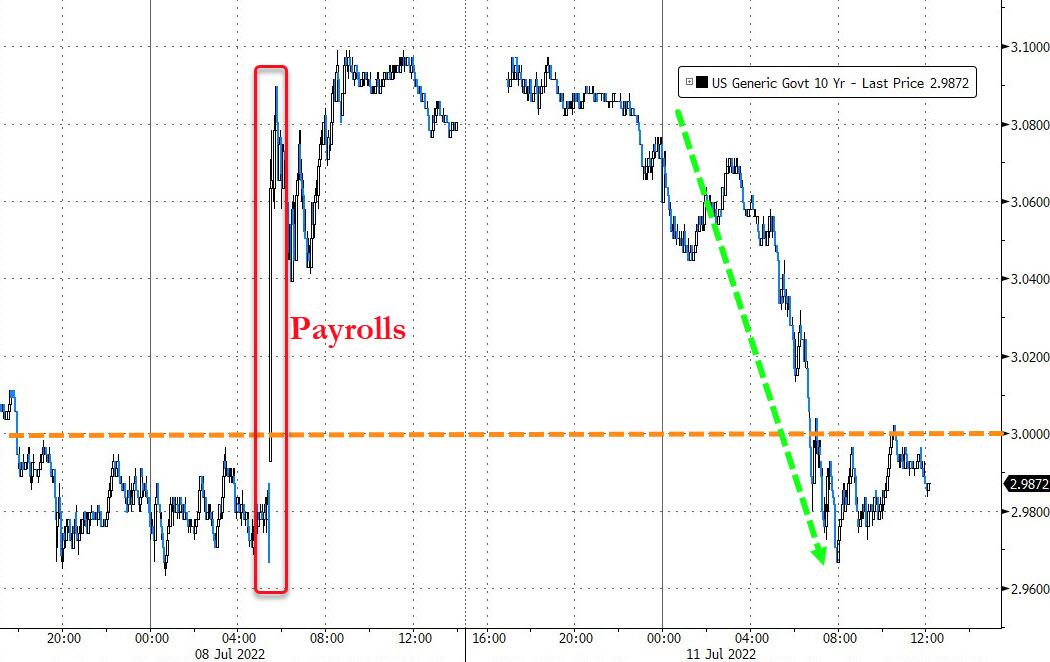
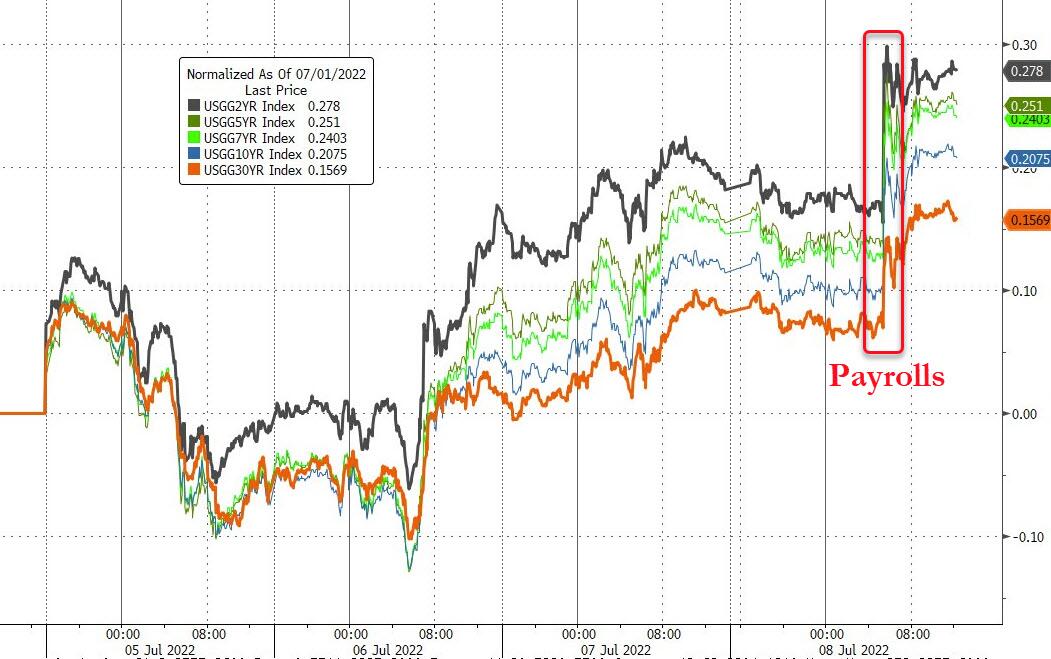
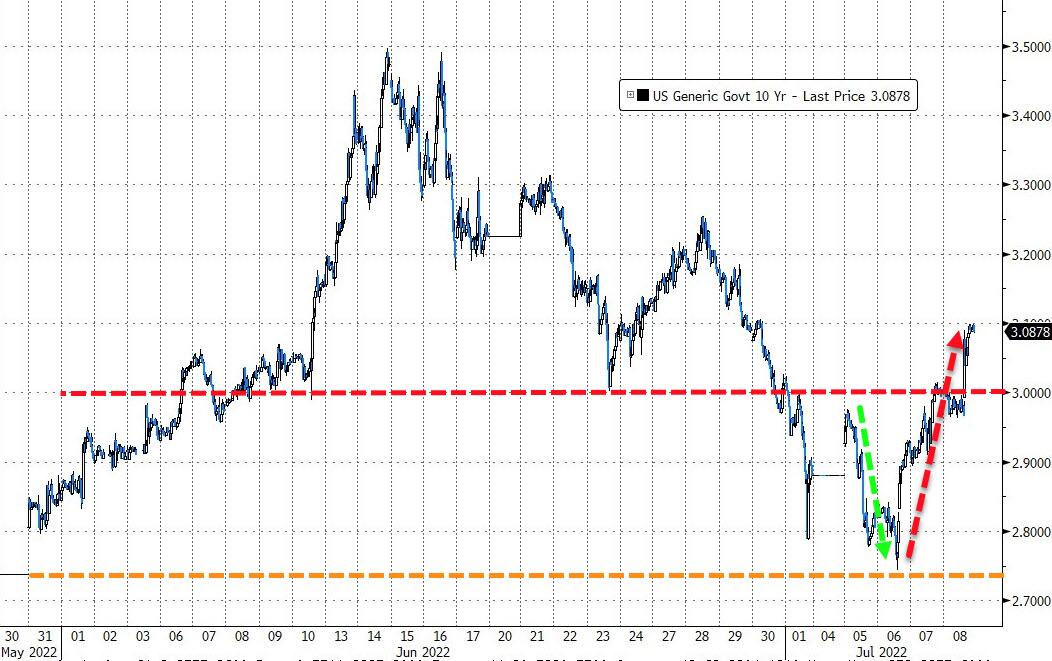
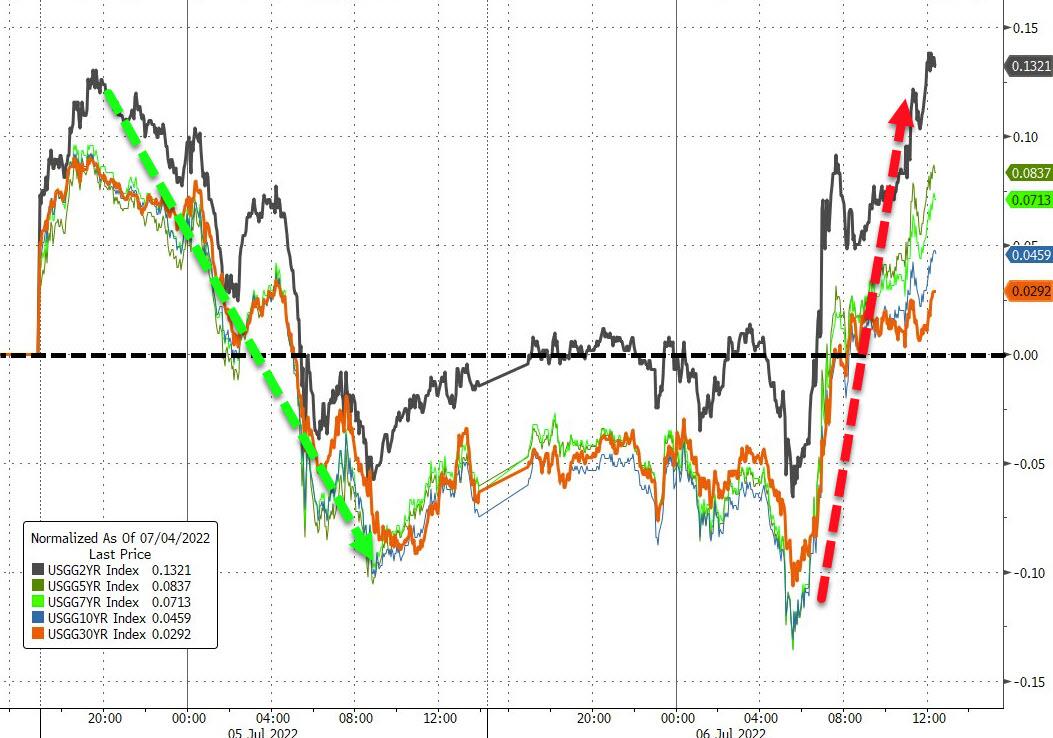
Bond yields dumped and pumped, but the 10-year remained below its 3% level. The biggest sell program in 2 weeks kicked in today, and those already were among the biggest in history.
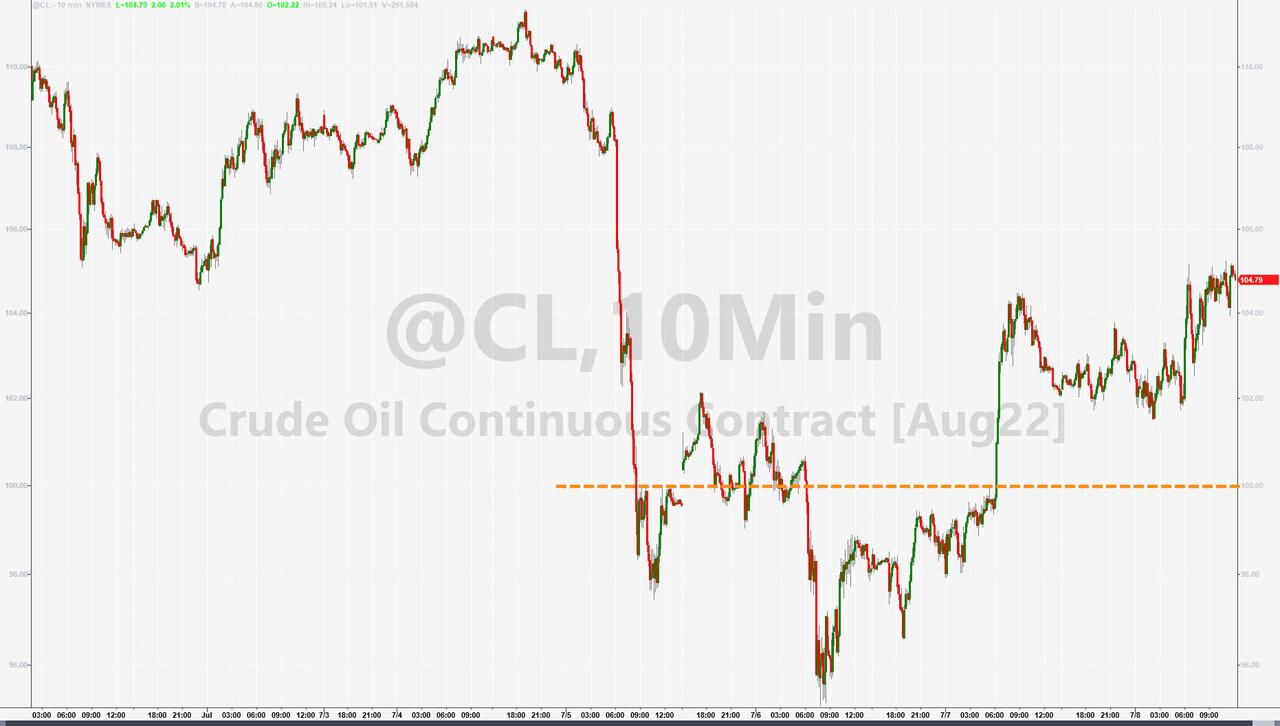
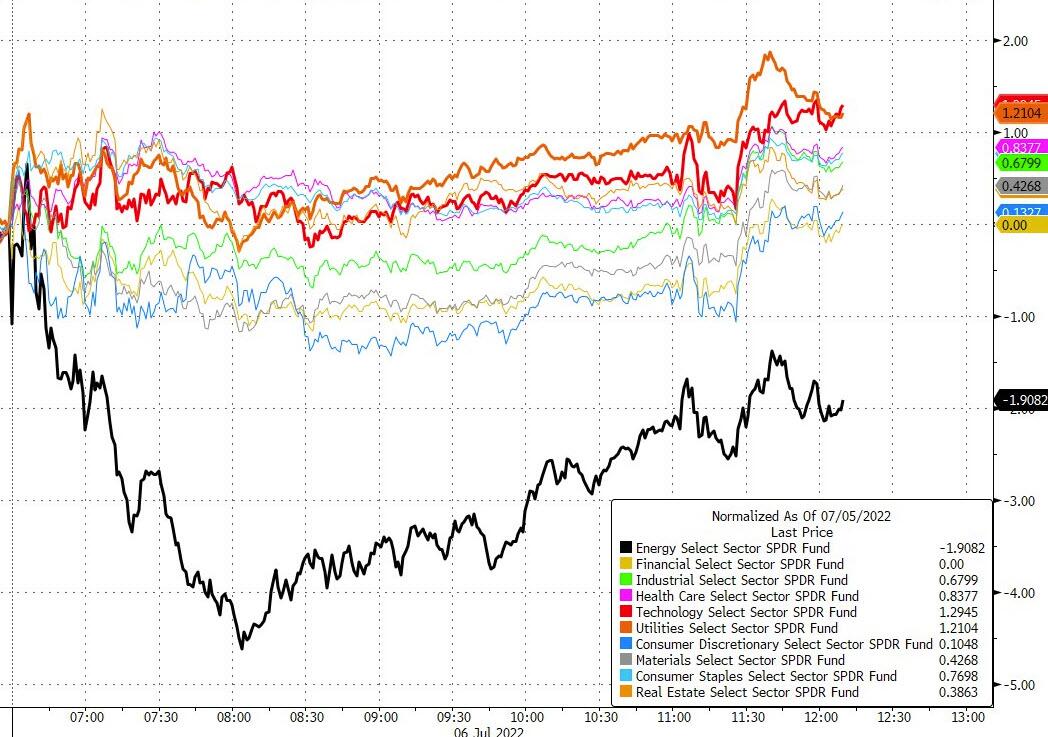
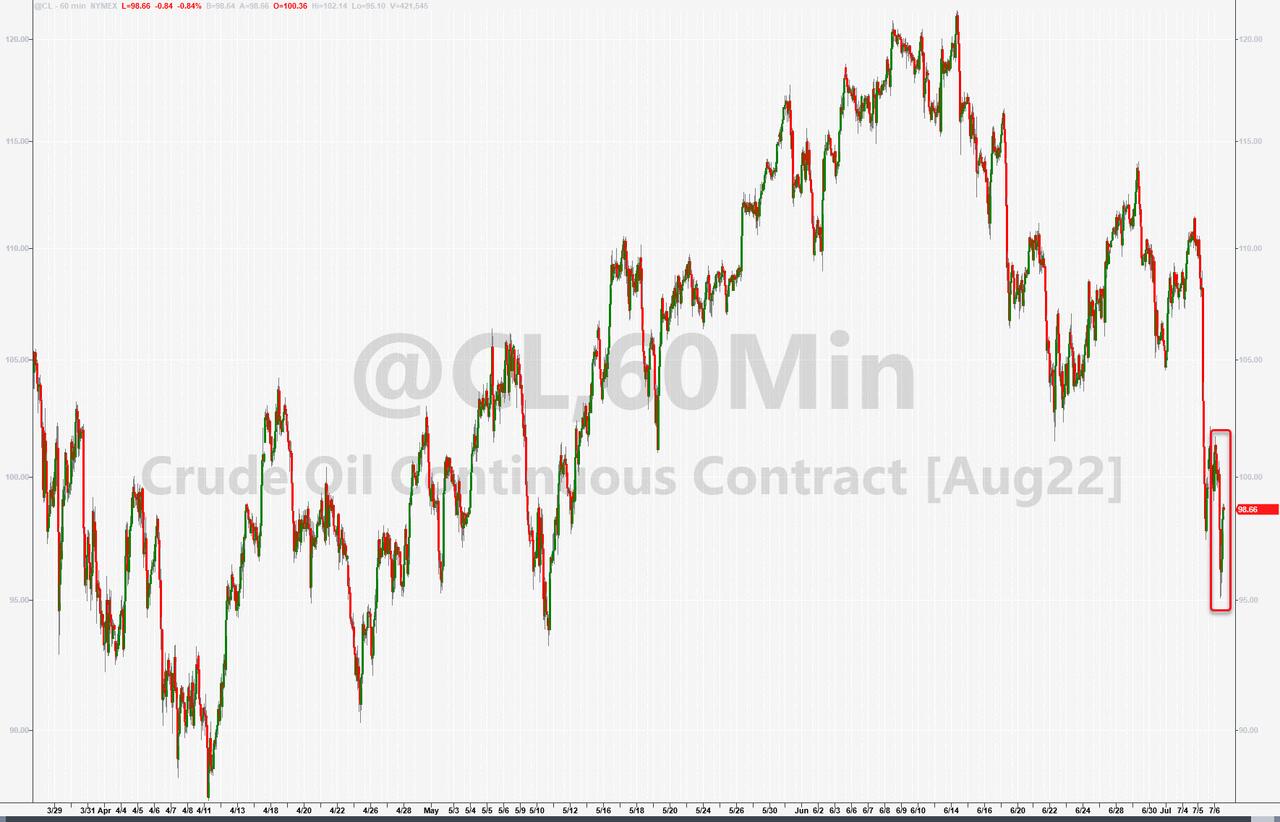
The loser of the day was Crude Oil, which tumbled over 8% to close at under $96.
All eyes are on tomorrow’s CPI report, which has exceeded expectations for the past 5 months, with the S&P 500 having fallen by an average of -0.78% on CPI-day, as ZH reported.
Will tomorrow be different?
Read More