Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 03/19/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, March 19, 2015
TOC021915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


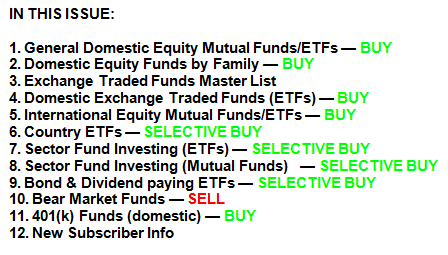
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/22/2014
TTI

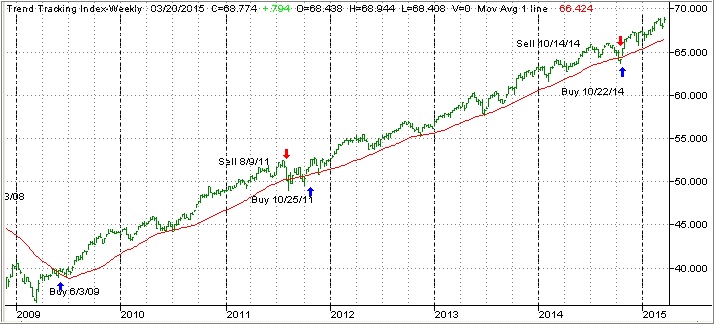
Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a “Sell” for this arena effective 10/14/2014, which was followed by a violent break back above the line on 10/22/14 generating a new “Buy.” It was a classic whipsaw signal, and you can read more on my blog as to the events as they were unfolding.

As of today, our TTI (green line in above chart) is positioned above its long term trend line (red) by +3.67% keeping us in the market with our established positions.
Read More

Sliding Oil Prices Take The Starch Out Of Markets

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

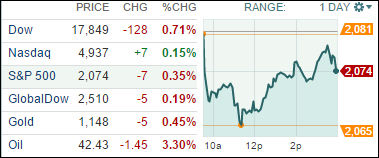
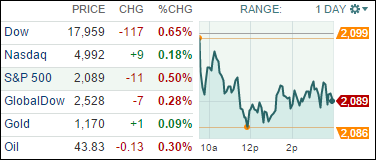
Markets were all peachy yesterday upon the Fed’s sentiment of keeping interest rates low for the near future. However, today was a new day and, as you know, market sentiment can change on a dime daily. Of the three major indexes, only the Nasdaq composite gained slightly.

Oil seemed to be the major driver pushing index prices lower. In oil, the benchmark index slid today to close at $43.96 a barrel, which extended the previous week’s decline. Amongst the biggest losers were Chevron (CVX) and Exxon Mobil (XOM). The general sentiment is that producers have not been eager to cut production, regardless of dropping prices over the past six months and prices will remain low until they intend to do so.

Big tech news of late is that Apple (AAPL) replaced AT&T as a Dow component. The move to the new index will take some time for settling in, so don’t fret that on its first day of trading in its new home did not result in major gains. The stock fell 0.8% on the day, but overall investors remain bullish that the company will continue pushing to record highs.

All of our 10 ETFs in the Spotlight headed south with yesterday’s winner, IOO, leading the decliners with a loss of -1.01%. Bucking the negative trend was healthcare (XLV), which managed to gain +0.58% in the face of adversity and made a new yearly high at the same time.

Read More

Markets Bullish On Fed Sentiment; Windows 10 This Summer?

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

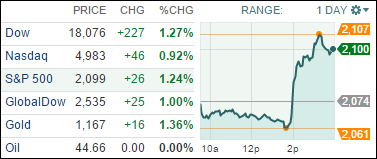
In a statement, the Fed, as expected, did drop its promise to be “patient” as it weighs interest rate hikes. Still, investors reacted bullishly to the suggestion that rate hikes were not baked in for June either, as feared, which potentially pushes out the first rate hike even later in the year. The Fed last hiked interest rates in 2006 mind you.

In commodities, Oil initially extended losses following the U.S. Energy Information Administration report that oil inventories rose by 9.6 million barrels. The much loved fossil fuel closed the day at $46.65 a barrel on the New York Mercantile Exchange.

In other news, Alibaba (BABA)’s share lock-up expires on Wednesday, allowing the Chinese e-commerce and web conglomerate to sell up to 437 million shares. And all you Microsoft (MSFT) junkies out there probably heard the announcement today that Windows 10 will hit the shelves of U.S. retailers this summer. It will be interesting to see the updates the company has incorporated and how it will impact the stock price moving forward.

All of our 10 ETFs in the Spotlight headed higher with solid gains. The Global 100 (IOO) was the leader with +1.71%, while the Financials (IYF) lagged with +0.65%. Healthcare (XLV) was the only one in the group to make new highs for the year as section 2 below shows.

Read More

Markets Lower Anticipating Fed Meeting

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The Fed kicked off their two-day meeting today. Of course, the hot topic of late is whether or not they will raise interest rates in the near future. The general consensus around the news today is that the Fed is likely to announce that they will remain patient over the next couple of months through June.

It’s been a few days since I mentioned oil. The black gold has been teetering back and forth between $40-50 a barrel for the past couple of months, and there was no new major update today, apart from the fact that the price of U.S. benchmark crude dropped 1.6% to $43.18 a barrel and that the commodity has been on a 3-day losing streak ahead of official data that is supposed to be released within the next week.

For all you tech enthusiast, you will be pleased to here today that Adobe (ADBE) reported Q1 earnings that topped analysts’ expectations. The company said it had a first quarter earnings of $84.9 million. You may not, however, be pleased to hear that Microsoft (MSFT) has decided to scrap the beloved browser Internet Explorer. Apparently, Microsoft is putting its chips on its new and speedier browser named Project Spartan. We shall stay tuned to see what the new browser will entail.

All of our 10 ETFs in the Spotlight reversed direction from yesterday and slipped with Consumer Staples (XLP) leading to the downside with -0.72%, while Global 100 (IOO) managed to hold up the best at -0.17%.

Read More

Markets Fly High On Fed Speculation

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

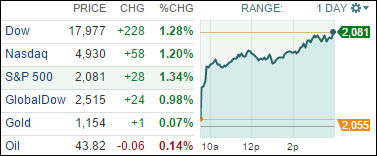
Markets soared higher today ahead of a two-day Federal Reserve meeting beginning tomorrow that may set the stage for the first U.S. interest rate hike since the global financial crisis.

In economic news, a growing number of investors expect the U.S. central bank to raise its benchmark interest rate sooner than anticipated and will be watching to see whether officials signal that’s the case. Many speculate that low interest rates have been boosting the stock market for the past couple of years and that a rise in interest rates could end the bull market in the near future but—no one really knows so we remain in rally mode leading up to the Fed announcement.

In the world of online advertising, Pinterest, a privately held company, has raised $367 million of late. The capital infusion has landed a valuation for the company around $11 billion, which makes the company one of the world’s most highly valued early stage companies. Prior to this funding round, Pinterest had raised $764 million.

All of our 10 ETFs in the Spotlight recovered and surged higher with healthcare (XLV) not only leading the pack with a +2.21% but also making new yearly highs. Mid-Caps (IWS) were lagging with “only” a +1.10% gain.

Read More

ETFs/Mutual Funds On The Cutline – Updated Through 03/13/2015

Ulli ETFs on the Cutline Contact

Below are the latest ETF Cutline reports, which show how far above or below their respective long-term trend lines (39 week SMA) my currently tracked ETFs/MFs are positioned.

The first report covers the ETF Master List from Thursday’s StatSheet and includes 410 ETFs, of which currently 237 (last week 246) are hovering in bullish territory.

The second report includes only High Volume ETFs. To clarify, High Volume (HV) ETFs are defined as those with an average daily volume of $10 million or higher.

These ETFs are generated from my selected list of some 97 that I use in my advisor practice. It cuts out the “noise,” which simply means it eliminates those ETFs that I would never buy because of their volume limitations. 37 ETFs (last week 41) have managed to remain in bullish territory after the recent market volatility.

The third report covers Mutual Funds on the Cutline. There are currently 352 (last week 281) above the line and 468 below it out of the 820 that I follow.

Take a look:

1. ETF Master Cutline Report

2. ETF High Volume Cutline Report

3. MF Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.