
[Chart courtesy of MarketWatch.com]
- Moving the market
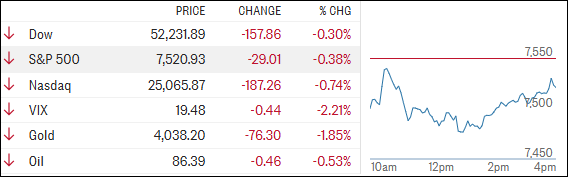
After yesterday’s euphoric rally, the market got a sharp reminder that gravity still exists.
A hotter-than-expected CPI report and some decidedly hawkish comments from the Fed reignited rate fears, sending stocks, bonds, gold, and crypto lower in one swift move.
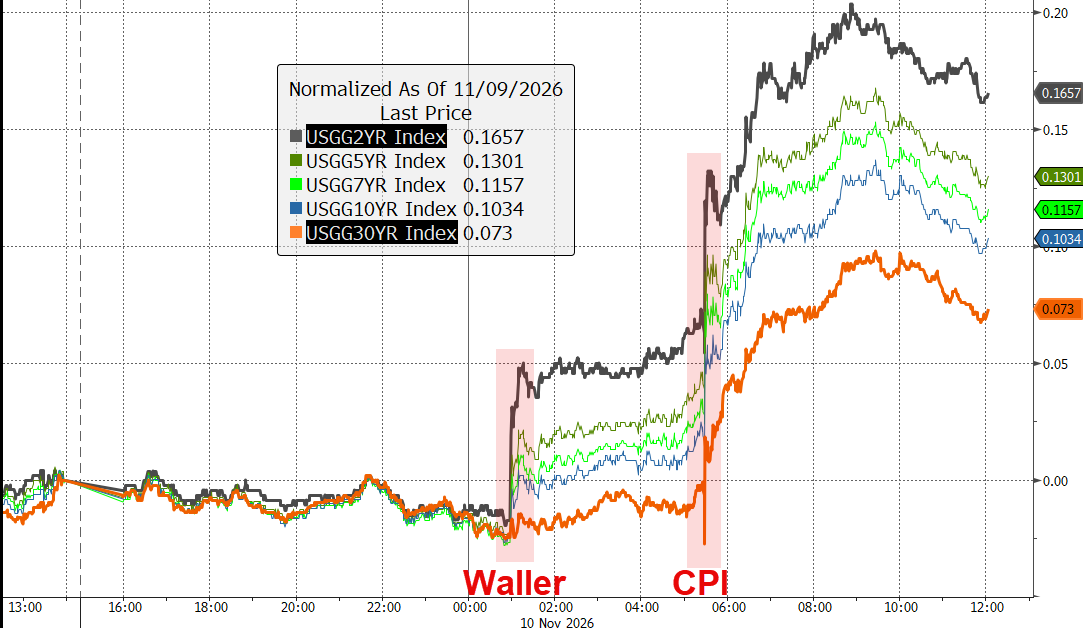
The CPI came in above expectations, while Fed Governor Christopher Waller signaled that another December rate hike is likely and even left the door open for a larger half-point move.
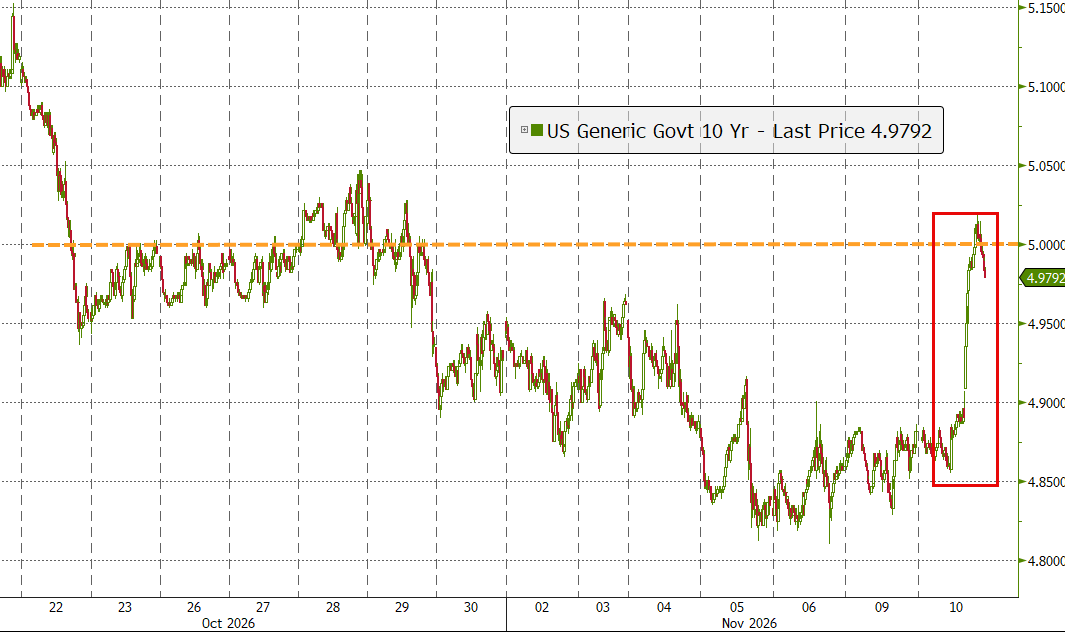
Bond yields responded in a hurry, with the 10-year Treasury vaulting back above 5%, its biggest one-day jump in months.
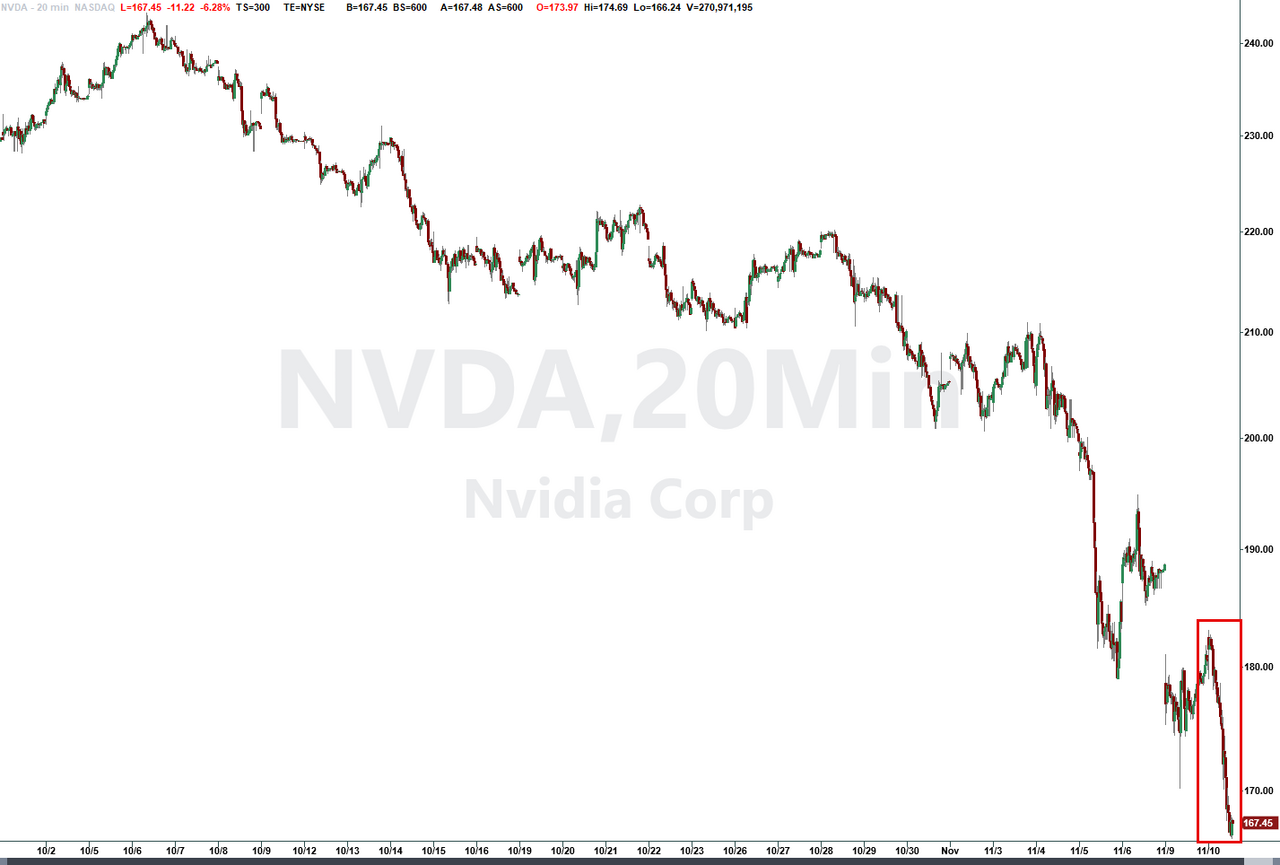
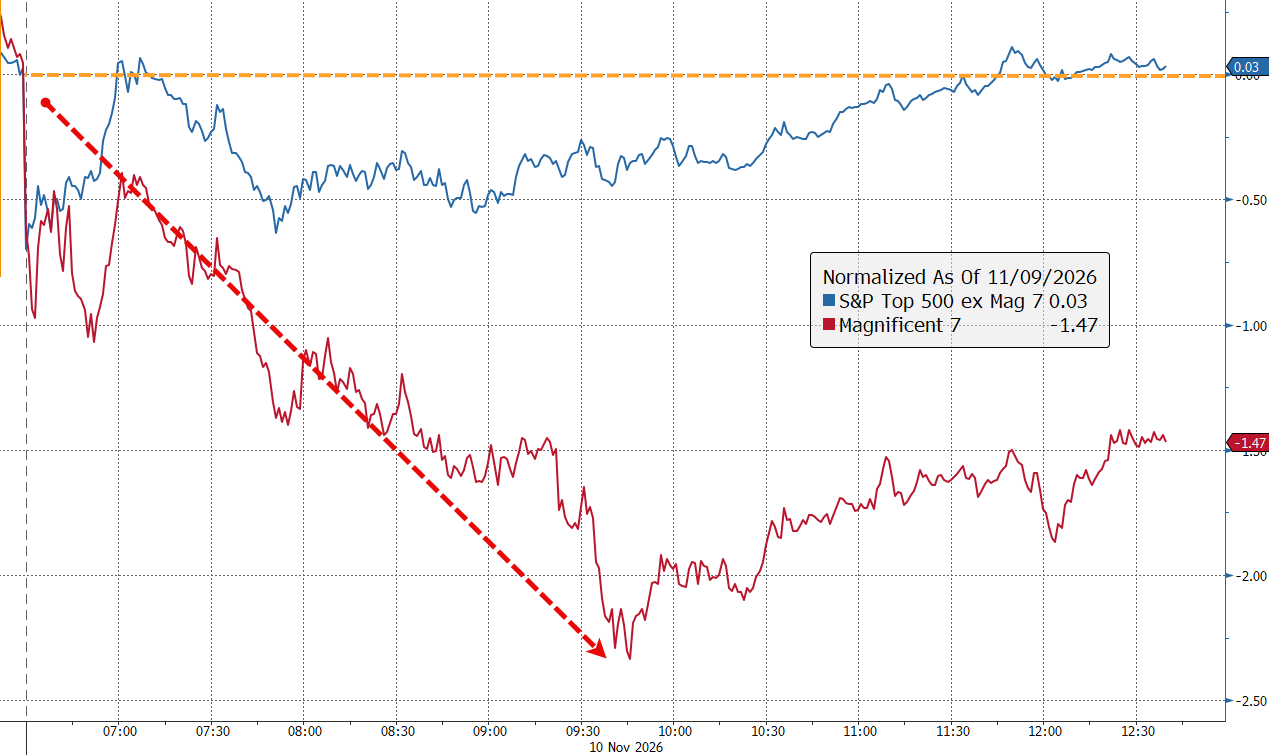
Adding to the pressure, Nvidia took another beating, helping drag down the Magnificent 7. Interestingly, the other 493 stocks in the S&P 500 held up much better, finishing roughly flat.
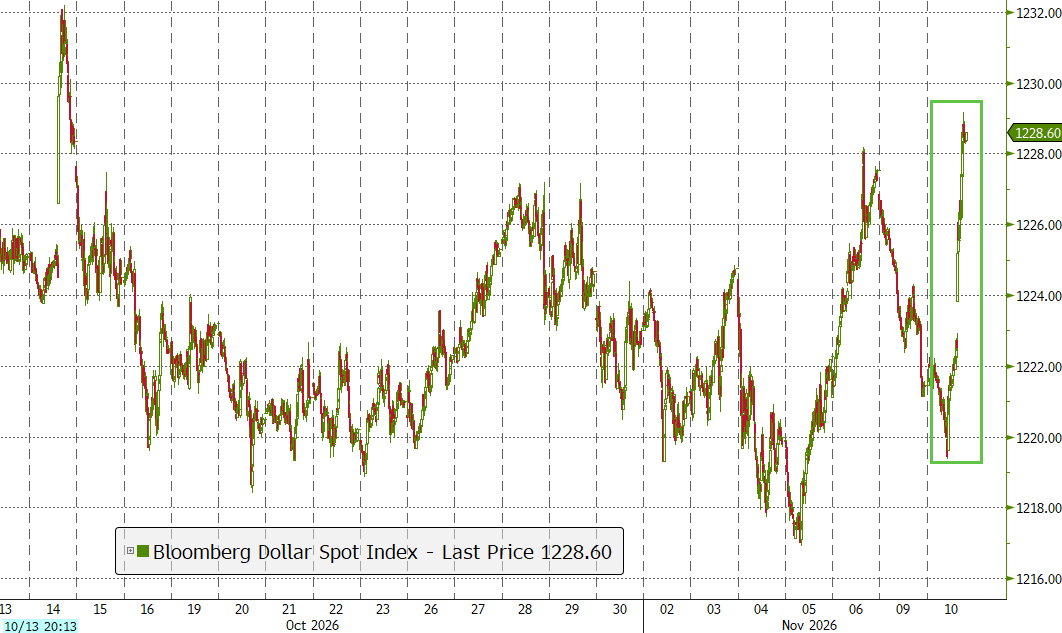
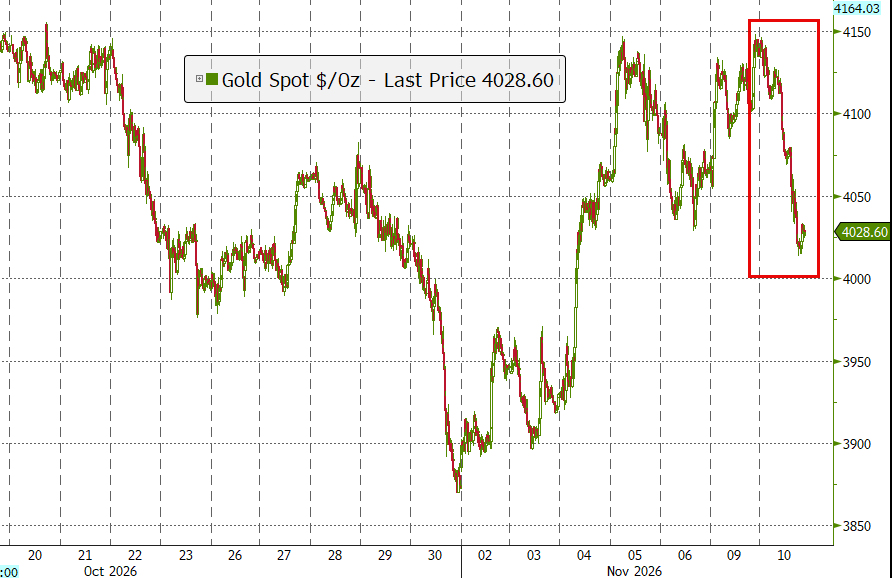
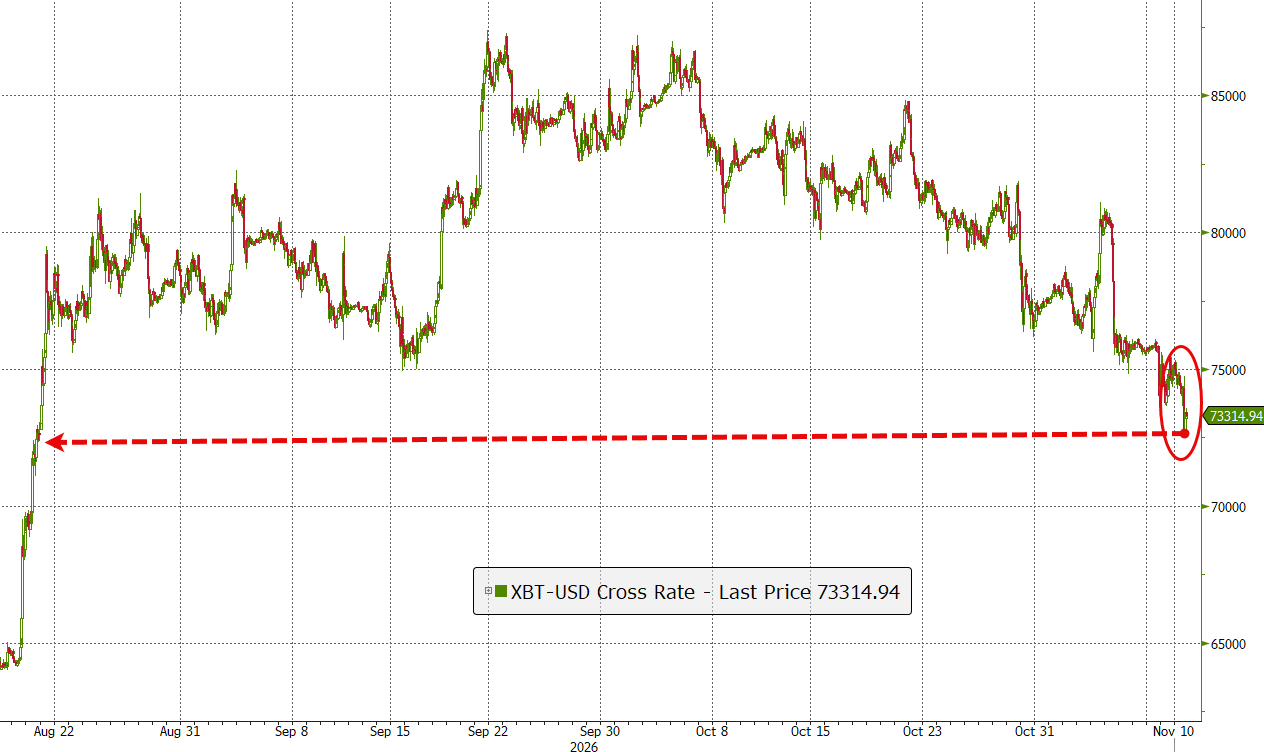
The dollar was the day’s clear winner, climbing to multi-month highs and knocking both gold and bitcoin firmly onto the defensive.
In the end, yesterday’s celebration turned into today’s hangover.
The real question now is whether this was just a one-day reality check or the start of a more meaningful repricing of rate expectations?
2. Current domestic “Buy” Cycle (effective 5/20/2025); International “Buy” Cycle (effective 5/8/25)
Our domestic bullish cycle that began on November 21, 2023, concluded on April 3, 2025, following a market downturn triggered by President Trump’s tariff policy announcement.
This development caused significant declines across major indexes and broader market indices. However, markets subsequently rebounded, culminating in a new domestic “Buy” signal taking effect May 20, 2025.
Concurrently, our International Trend Tracking Index (TTI) experienced parallel volatility. On April 4, 2025, it breached critical thresholds, prompting a “Sell” recommendation. This position reversed as global markets recovered, with the International TTI regaining sufficient momentum to issue a new “Buy” signal effective May 8, 2025.
3. Trend Tracking Indexes (TTIs)
Yesterday’s optimism got hit with a reality check today. A hotter-than-expected CPI report, followed by a Fed that sounded in no rush to cut rates, was enough to send the major indexes south.
Stocks did manage to climb off their intraday lows, but the metals couldn’t find their footing and spent the day stuck in reverse.
The good news? Our TTIs showed a bit more resilience than the broader market, with the international model even sneaking out a small gain.
Not every day can be a rally day. Sometimes the market’s job is simply to remind us that the Fed still has a seat at the table… and occasionally likes to pull up a chair.
This is how we closed 11/10/2026:
Domestic TTI: +6.44% above its M/A (prior close +6.46%)—Buy signal effective 5/20/25.
International TTI: +3.91% above its M/A (prior close +3.83%)—Buy signal effective 5/8/25.
All linked charts above are courtesy of Bloomberg via ZeroHedge.
———————————————————-
WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?
Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly to get more details.
Contact Ulli