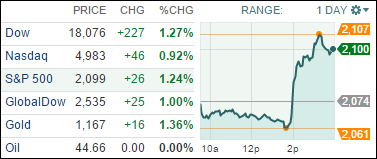
1. Moving the Markets
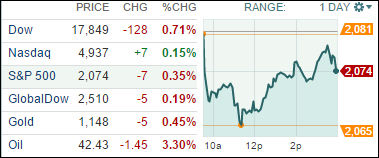
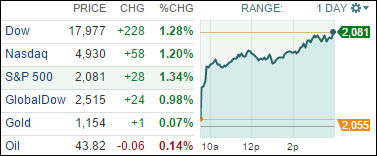
In a statement, the Fed, as expected, did drop its promise to be “patient” as it weighs interest rate hikes. Still, investors reacted bullishly to the suggestion that rate hikes were not baked in for June either, as feared, which potentially pushes out the first rate hike even later in the year. The Fed last hiked interest rates in 2006 mind you.
In commodities, Oil initially extended losses following the U.S. Energy Information Administration report that oil inventories rose by 9.6 million barrels. The much loved fossil fuel closed the day at $46.65 a barrel on the New York Mercantile Exchange.
In other news, Alibaba (BABA)’s share lock-up expires on Wednesday, allowing the Chinese e-commerce and web conglomerate to sell up to 437 million shares. And all you Microsoft (MSFT) junkies out there probably heard the announcement today that Windows 10 will hit the shelves of U.S. retailers this summer. It will be interesting to see the updates the company has incorporated and how it will impact the stock price moving forward.
All of our 10 ETFs in the Spotlight headed higher with solid gains. The Global 100 (IOO) was the leader with +1.71%, while the Financials (IYF) lagged with +0.65%. Healthcare (XLV) was the only one in the group to make new highs for the year as section 2 below shows.