1. Moving the Markets
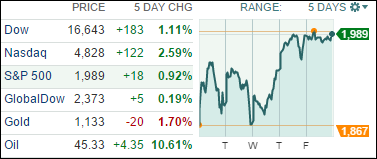
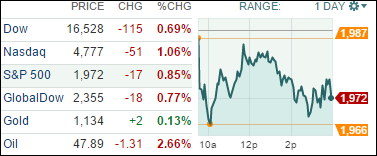
Uncertainty about the timing of Federal Reserve rate hikes and persistent fears about a China slowdown continued to weigh on financial markets after last week’s wild ride. Investors thought stocks may have stabilized by the end of last week, however, indexes tumbled and oil prices surged Monday as Wall Street closed out a volatile August with hefty losses that gave the S&P 500 its worst monthly performance since May 2012.
The losses were broad-based with nine out of the ten S&P sectors falling. Energy stocks were the only gainers as oil prices surged for a third straight day after the OPEC indicated they are prepared to discuss production levels. As a side note, Crude has jumped 27% in three days.
As for real estate, the sudden collapse in the Shanghai Composite and the devaluation of the yuan in the past month have led some to worry that it could cause trouble for the U.S. real estate. The reality is that potential capital flows from the turmoil in China can find safety in U.S. properties and the data speaks to it. Over the last 12 months, nearly $5.1 billion of $21.1 billion in commercial real estate investments coming from China has been allocated to the U.S market.
There were no green numbers to be found in our 10 ETFs in the Spotlight with all of them heading south. Faring the best was the Mid-Cap Value ETF (IWS) with a loss of -0.44%, while Healthcare (XLV) gave back the most by surrendering -1.82%.
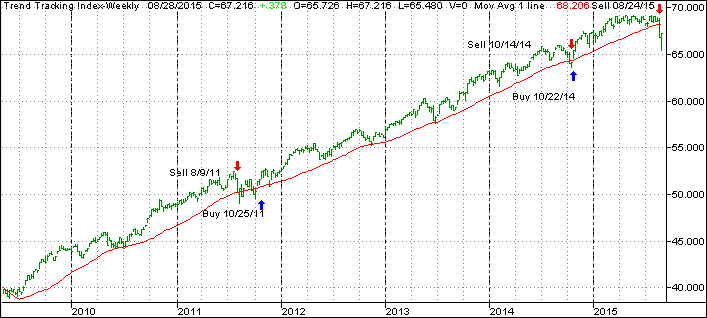
Our Trend Tracking Indexes (TTIs) remain in bear market territory.