[Chart courtesy of MarketWatch.com]
1. Moving the Markets
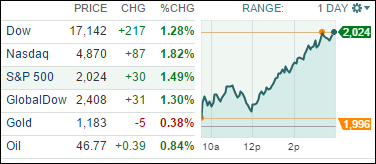
Stocks jumped Thursday, the Nasdaq gaining 1.8% and the Dow climbing 217 points amid mixed profit results from major banks and as less-than-stellar incoming economic data lowered chances of Federal Reserve interest rate hike later this year.
The rebound came a day after shares tumbled sharply after giant retailer Walmart (WMT) warned of a big drop in earnings in its 2017 fiscal year.
Driving the stock action Thursday was an earnings beat by banking giant Citigroup (C), which topped analyst expectations by 3 cents, and a minor miss from Wall Street titan Goldman Sachs (GS), whose earnings came in a penny shy of expectations. Both Citigroup and Goldman Sachs fell shy on revenue.
Wall Street also digested fresh economic data. First-time jobless claims fell 7,000 to 255,000 to a pre-recession low in the latest weekly report, signaling once again that the employment picture is improving. On the inflation front, inflation at the consumer level, or the CPI, fell 0.2% in September, in line with economists’ expectations. The continued low inflation also gives credence to Wall Street’s theory that the Fed will hold off on rate hikes this year.
The question now is will there be enough follow through momentum to generate a new domestic Buy signal? As you can see in section 3, we’re getting close but are not there yet.
In a reversal from yesterday, all of our 10 ETFs in the Spotlight joined the party and closed higher. The leader was Healthcare (XLV) with +2.17%, while Consumer Staples (XLP) and the Dividend ETF (DVY) lagged a little with +0.90%.
Read More

 Another market sell-off depends on the Fed’s next move, because the current situation very strongly echoes the conditions of 1998, said Jonathan Wilmot, head of macro investments at Credit Suisse Asset Management.