New ETFs On The Block: JP Morgan Diversified Return US Equity ETF (JPUS)

Ulli Equity ETFs Contact

CandleStickChartJP Morgan Asset Management, the exchange-traded fund issuing arm of the investment bank JP Morgan, recently joined hands with FTSE Russell to leverage their respective capabilities in investment science and index designing.

The outcome was the launch of JP Morgan’s fourth “smart beta” ETF that bolsters the money manager’s offerings in that niche and attempts to exploit the domestic US growth story.

The JPMorgan Diversified Return US Equity ETF (JPUS) joins the ranks of JP Morgan’s so-called smart/strategic beta funds that employ a rules-based multi-factor approach to reduce volatility compared to market cap-weighted indices over the long term.

Read More

ETF/No Load Fund Tracker Newsletter For November 27, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/11/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-11252015/

————————————————————

Market Commentary

A NON-EVENTFUL WEEK WITH A VOLATILE ONE AHEAD
Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

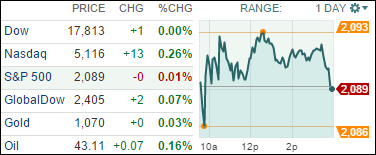
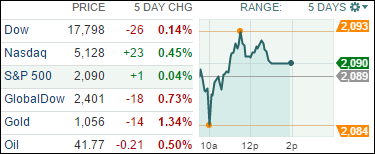
It was a slow week with no market moving events as the Thanksgiving Day and the short session on Friday combined to reduce momentum in either direction causing the S&P 500 a 1 point gain since last Friday.

However, next week could be a different story. There may be some fallout from the Chinese stock market, which took a beating at the tune of -5.5% in one day as authorities cracked down on big brokers and pretty much anyone that dared to short the market.

Next Thursday, the ECB is having another powwow with investors hoping for more monetary easing to keep the stock markets hopping. On Friday, the OPECers will decide as to whether they will hold the supply levels firm or make adjustments to control the current weak prices.

Then we’re on to the monthly jobs report, which may be one of the most eagerly awaited pieces of economic news as it is the last one before the Fed meets to decide the future fate of interest rates. It could be a volatile week and may very well push our Domestic Trend Tracking Index (TTI) out of its tight trading range either further back into bearish territory or may with renewed vigor generate a new “Buy” signal.

8 of our 10 ETFs in the Spotlight closed up today to end this Holiday shortened week about unchanged. Leading the group were the Consumer Staples (XLP) with +0.38%; on the downside, Consumer Discretionaries (XLY) gave back the most by losing -0.37%.

Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 11/25/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Wednesday, November 25, 2015

TOC 111915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


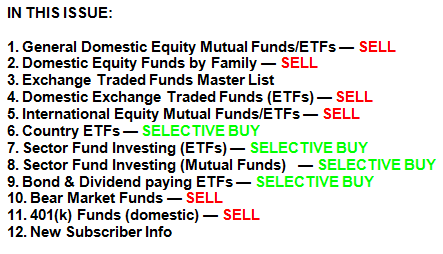
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: SELL— since 11/13/2015

TTI

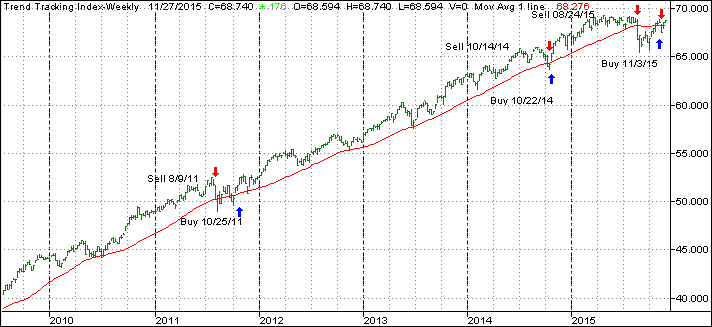
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in above chart) has recently crawled above its long term trend line (red) and finally generated a new “Buy” signal effective 11/3/15. The market subsequently dropped, and we exited again on 11/13/15. As of today, the TTI has crawled back above its trend line by +0.67%, which is not enough of a breakout to generate a new “Buy” signal. Stay tuned for daily blog updates.

Read More

Going Nowhere

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

It was a slow pre-Holiday session with the major indexes trending to the upside intraday but ending just about unchanged. Volume was extremely low.

Economic data were mixed but Wall Street still believes that the Fed remains on track to raise rates. All eyes are on next week’s jobs report which, should it come in better than expected (200,000), may turn out to be the final nail in the interest rate coffin.

The markets will be open this Friday for a half-day session.

6 of our 10 ETFs in the Spotlight squeezed out a gain in this non-directional session. Leading to the upside was Healthcare (XLV) with +0.54%, while the Global 100 (IOO) slipped -0.09%.

Read More

Major Indexes Stay Afloat Amidst Terrorism

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The 3 major u.s. benchmarks eked out small gains today by the closing bell, as geopolitical risk weighed on financial markets. The shooting of a Russian fighter jet by turkey entrenched the post-paris terrorism threat and coming interest rate hikes on wall street’s worry list today.

The latest geopolitical flash drove stock prices down in Europe and in early trading in the U.S. and sparked a rally in oil, which set off a flight to safe-haven assets, such as U.S. and German government bonds. The sharp drop early on did not last, and the indexes slowly climbed out of a deep hole; in my view only because of seasonal tendencies as economic data was questionable to say the least.

In the tech world, we heard from Hewlett Packard (HPQ) today that revenue for the two-tiered organization in Q4 was down, year over year, and profits were at the low end of analysts’ estimates, which may reaffirm the necessity for the 76-year-old computing pioneer’s recent split. The combined company has reported a revenue decline in 16 of the past 17 quarters. Since the official split more than three weeks ago, HPE shares have tumbled 8% to $13.85. Shares of (HPQ), which sells PCs and printers, have surged 16% to $14.23.

7 of our 10 ETFs in the Spotlight edged higher and 3 closed down. Leading on the plus side was the Mid-Cap Value (IWS) with +0.42%. Slipping the most was the Low Volatility S&P (SPLV) with -0.28%.

Read More

Markets Quiet After Booming Week

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Wall Street, coming off its best weekly gain of the year, which was preceded by its worst one, kicked off the Holiday-shortened week in a cautious mood, as investors digested a record deal in the pharmaceutical space and kept a close eye on Europe, where the terrorism threat remains real.

It seems to me that Wall Street is in a tug of war at the moment, with the market benefiting from what has historically been a good seasonal period for stocks, but being held back by a market driven by just a handful of stocks, geopolitical risks and continued price pressures in the commodities space. At the same time, we are close to reaching the upper end of the trading range for he S&P 500 and need to see whether this glass ceiling will be broken or not.

U.S. Crude Oil dropped about 2.84% today to close at just under $40 a barrel. This means that prices could remain under $2 a gallon throughout most of the country this week.

In M&A news today, pharmaceutical giants Pfizer (PFE) and Allergan (AGN) are on the verge of announcing the largest healthcare merger in history. The merger would allow Pfizer to transfer its headquarters from the U.S.A. to Ireland. The $160 billion deal has raised eyebrows about the tax-saving strategy it entails, but it appears at present that the deal will reach the finish line.

6 of our 10 ETFs in the Spotlight closed up led by Consumer Staples (XLP) with +0.88%, while the downside leader was the Global 100 (IOO) sporting a loss of -0.60%.

Read More