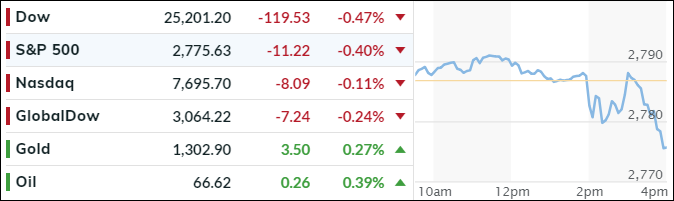
- Moving the markets
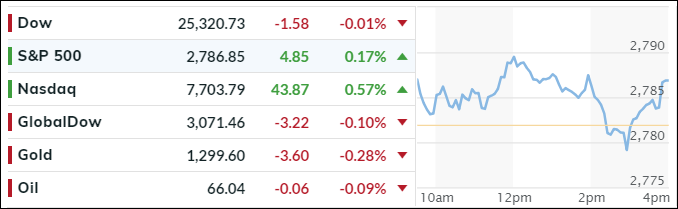
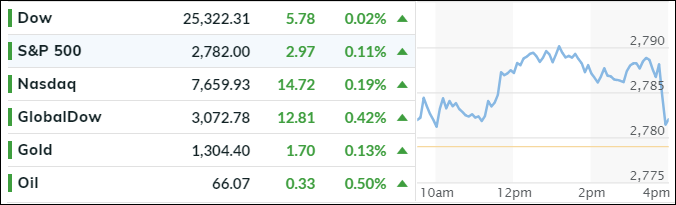
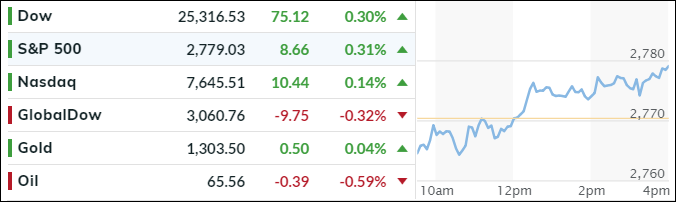
The major indexes hovered above the unchanged line for most of the session, but some volatility set in after the Fed’s (expected) announcement of a 25-bps increase in interest rates, while assuring the Wall Street crowd that the economy is not yet overheating. Yet, at the same time, Fed head Powell signaled that two more hikes would be on the table for 2018, rather than the expected hoped for one.
His exact words were “there is no sense in our forecasts that inflation will take off. If we thought inflation would take off, we would be showing higher rates.” You should feel much better now knowing that the CPI inflation you experience day-to-day, is non-existent.
In the end, equities dove into the close with the major indexes suffering mild losses. While the “most shorted stocks” were flat today, this chart demonstrates the tremendous impact of the short squeeze we’ve seen over the past few weeks.
As could be expected, bond yields rallied at first, with the 10-year yield touching the 3% level, before turning around and ending just about unchanged. The US Dollar rode his own roller coaster by heading higher at first, then dropping into the red, recovering into the green and closing below the unchanged line.
On the calendar for tomorrow is the widely anticipated ECB meeting, during which they are supposed to unveil the timing of their bond purchases. Translated, it simply means whether they will unwind at a faster or slower pace, the former of which translates to the equivalent of a tightening effect as far as monetary policy is concerned.