[Chart courtesy of MarketWatch.com]
- Moving the markets
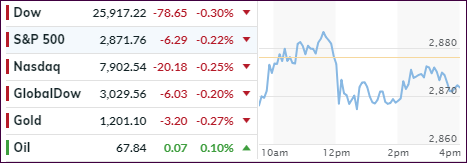
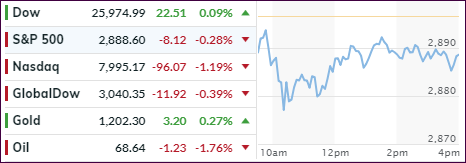
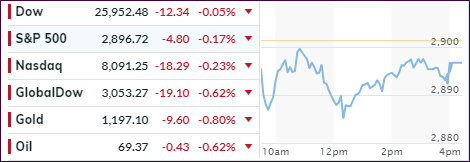
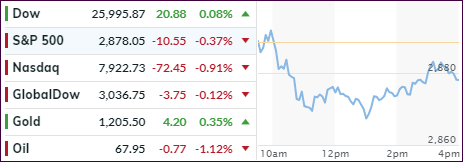
The major indexes headed south again led by continuing weakness in the tech sector. However, the Dow managed to buck the trend by ending in the green by a small margin. The S&P’s attempts to conquer the unchanged line were rebuffed, while the Nasdaq didn’t even come close to stage any kind of lasting rally and dropped -0.91%.
Not helping matters was softness in global markets with indexes in Europe and Asia heading south over mounting concerns that some of the struggling emerging markets may affect the economies of healthier EMs as well.
In focus today were Turkey and Argentina, whose currency followed the law of gravity, as confidence waned and spillover fears worsened. As I posted before, this drag will get worse, since no viable economic solutions appear to be on the horizon.
On the trade front, the jawboning with Canada intensified a notch, as Trump threw down the gauntlet by declaring that he is ready to move forward without Canada. Then there is the issue of the $200 billion in Chinese tariffs, which could be imposed as soon as this week.
Domestically, the FANG stocks headed south again for the 4th day in a row, its longest losing streak in 7 months.
I have talked much about the disconnect of various indicators. Here’s the latest update charting the S&P vs. the 30-year bond yield. As you can see, right now it appears that both are heading towards each other, and we may see a syncing soon. To be clear, this means that yields continue their path higher, with bond investors losing out. Why? When yields are rising, bond prices are falling.
On deck, and certainly capable of moving markets, is tomorrow’s jobs report. This promises to be an interesting event and, judging by today’s weak ADP numbers, expectations for 200k new jobs added in August, may be a little too optimistic.
Read More