Fed Keeps Rates Unchanged; Markets Mixed

Ulli Market Commentary Contact

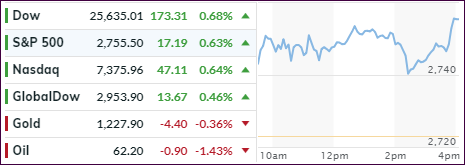
[Chart courtesy of MarketWatch.com]
  1. Moving the markets

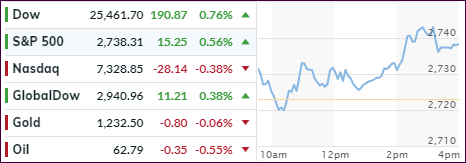
There was not much follow through from yesterday’s massive rally, but there was not much of a sell-off either, meaning that our new domestic “Buy” took effect today. We got our feet wet with some conservative exposure to “broadly diversified domestic ETFs,” while acknowledging that at any time momentum could turn around and head back the other way.

The danger of a such a head fake is always the greatest at the beginning of a new cycle where bulls and bears are still engaged in a tug-of-war. Such was the case today, as the Dow ventured above the unchanged line, although not very convincingly, while the S&P 500 and Nasdaq hovered below theirs leaving us with a mixed picture at the end of the session.

The Fed came out and did what was expected, namely not hiking rates this month but indicating that an increase will likely be in the cards for December. Market reaction was muted but some analysts, dissecting the Fed’s statement, saw hawkishness in their remarks, which contributed to the major indexes slumping.

The US dollar index was the beneficiary and popped while continuing its rise off yesterday’s bottom. Crude oil sank for the 9th day in a row and is now entrenched in a bear market, down -21.25% from October highs to 7-month lows. If it drops another day to 10 in a row, it will a dubious record in that this would represent the first time in 33 years of futures trading. Ouch!
Read More

The Morning After: Political Gridlock Is Good For Equities; New Domestic “Buy” Signal Is Generated

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

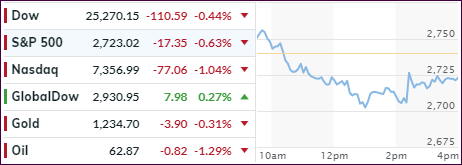
Right out of the starting gates, bullish momentum ruled, and the major indexes staged an impressive come-back rally. With the results of the elections confirming a political gridlock, you may be wondering why that would be a good thing for stocks.

The Daily Bell provided this answer:

Republicans expanded their majority in the Senate, and Democrats took the House.

Surely this will cause more gridlock. Less will get done. Fewer bills will pass. Each side’s agenda will be watered down.

And that is about the best results we could hope for.

The less that gets done the better. For everyone.

Calvin Coolidge was the last President to understand this… or at least to care.

Every President tries to leave his mark on the country. But usually, it is a blemish.

President from 1923-1929, Calvin Coolidge said, “It is much more important to kill bad bills than to pass good ones.”

Apparently, the computer algos were programmed this way and pushed the markets out of their doldrums, however, on low volume. Whether this will turn into the anticipated year-end rally remains to be seen.

However, this morning, during the early stages of the rebound, our Domestic Trend Tracking Index (TTI) crossed above its long-term trend line into bullish territory. I took the opportunity to start moving a portion of clients’ assets back into equities. Usually, my action point is generated after the close, but the handwriting of a huge move was apparent. This gave us a head start on what might be a return to the bullish theme.

By the end of the day, this turned out to be the correct decision, as our Domestic TTI raced ahead and triggered a new “Buy” effective tomorrow, unless a huge correction is in the making. Absent of that, I will cautiously proceed with adding to our current holdings.

The Fed is due out tomorrow to give a verdict on interest rates. While a hike is assumed for December, none is expected tomorrow. Should that expectation turn out to be false hope, markets will likely head south and give back today’s gains.

Read More

Waiting For The Election Outcome

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

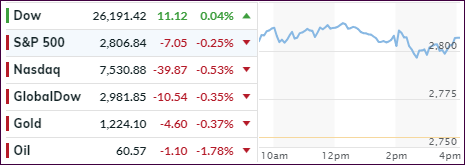
With most of the mid-term election results being on deck later tonight, it came as no surprise that the markets meandered, but with a bullish bias, as all 3 major indexes closed in the green with last minute buying helping the bullish cause, although on ultra-low volume (60% below average).

Polls and forecasts occupied the headlines where opinions varied widely ranging from “what happened to equities after every midterm” to “a healthy 30%-plus correction headed for stocks.” Of course, someone is bound to be dead wrong when you consider totally opposing views.

One investment firm summed the current scenario up this way:

“It is definitely not the time to buy the dip,” said London & Capital’s CIO Pau Morilla-Giner. “Everything that could go well for U.S. consumers in the last couple of years has gone well, but now the tide is turning… At the moment, you are running out of drivers of growth in the U.S.”

I agree with this assessment but will add that momentum can turn quickly even in the face of slowing fundamentals. There could be a relief rally in store, so we need to be prepared to jump back in should our Domestic TTI (section 3) crosses back above its long-term trend line. As of today, we are only -0.41% away from a new “Buy” Signal.

On the other hand, the Fed will make his announcement regarding interest rates tomorrow around noon which, depending on the outcome, could wreak havoc with the markets. It promises to be an interesting next few days.

Read More

Heading Higher Despite A Slumping Nasdaq

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

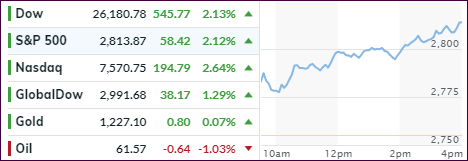
In view of tomorrow’s mid-term elections, the markets meandered with a slight upward bias in hopes that Tuesday’s outcome will not shift the balance of power, which could be key in terms of future market direction.

Two of the three major indexes gained moderately on news that a Rasmussen poll showed hopeful signs for the GOP. Of course, poll results can vary wildly and are better disregarded until the final count is completed. The Nasdaq was the laggard, as Apple still proved to be the anchor after announcing that they no longer have plans to disclose unit sales for some of their key products.

On Wednesday, we will find out if the Fed will hike rates again, which could spark a whirlwind on Wall Street. Should the GOP, which traders consider market positive, come out ahead, a rally may ensue, which, however, could be ruined by the Fed announcing an interest rate increase.

If they don’t, we may see the markets take off and, depending on the magnitude, we may see our Domestic Trend Tracking Index (TTI) break back above its long-term trend line into bullish territory, thereby signaling a new “Buy.”

Right now, we must be patient and see how things play out.

Read More

ETFs On The Cutline – Updated Through 11/02/2018

Ulli ETFs on the Cutline Contact

Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.

This report covers the HV ETF Master List from Thursday’s StatSheet and includes 366 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 45 (last week 40) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.

Take a look:

The HV ETF Master Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms.

If you missed the original post about the Cutline approach, you can read it here.

ETF Tracker Newsletter For November 2, 2018

Ulli ETF Tracker Contact

ETF Tracker StatSheet

https://theetfbully.com/2018/11/weekly-statsheet-for-the-etf-tracker-newsletter-updated-through-11-01-2018/

Trump Saves The Day For The Bulls

[Chart courtesy of MarketWatch.com]
  1. Moving the markets

Sometimes you just have to laugh. The markets were in a downswing for most of the day mainly as a result of two events.

First, Apple’s earnings report card, while not bad, disappointed with especially their forward guidance not being very encouraging despite the upcoming Christmas season. The immediate punishment was a drop in the stock price of some 7%, which pulled the entire tech sector down over 1%.

Second, October payrolls surged by 250k and exceeded expectations. While that should have been good news, it wasn’t. On the contrary. This appears to be the nail in the interest rate coffin with a December hike now being virtually assured, as the report showed that wages rose at the fastest pace in nine years, which indicates that inflationary pressures are in our future. The unemployment rate remained at 3.7%, its lowest since 1969.

This caused the markets to pick up downward momentum with the Dow being down 250 points at one time. Then, Trump started to talk China trade. First, there were denials from three While House officials off the record and Larry Kudlow on the record that trade talks were progressing. Suddenly, during the last hour, Trump stepped up and told reporters that “China talks are going well,” “the US will reach a trade deal with China,” and “getting closer to doing something with China.”

That was enough to shift the computer algos not only into reverse but also into overdrive and mysterious buying pressure appeared out of nowhere, stocks recovered, and cut the mid-day losses in half. Looking at the entire week, it has become clear, that a giant short squeeze helped the bulls to climb out of a deep hole, but falling short of reversing the technical damage done in red October.

Bond yields surged by 8 basis points today with the 10-year closing at 3.22%. That clobbered the widely held 20-year bond ETF (TLT) by -1.24% to a level last seen in March of 2017.

We remain on the sidelines until our Domestic Trend Tracking Indexes (section 3) move back into bullish territory.

Read More