ETF Tracker Newsletter For August 16, 2019

Ulli ETF Tracker Contact

ETF Tracker StatSheet          

You can view the latest version here.

REBOUNDING INTO THE WEEKEND
[Chart courtesy of MarketWatch.com]

  1. Moving the markets

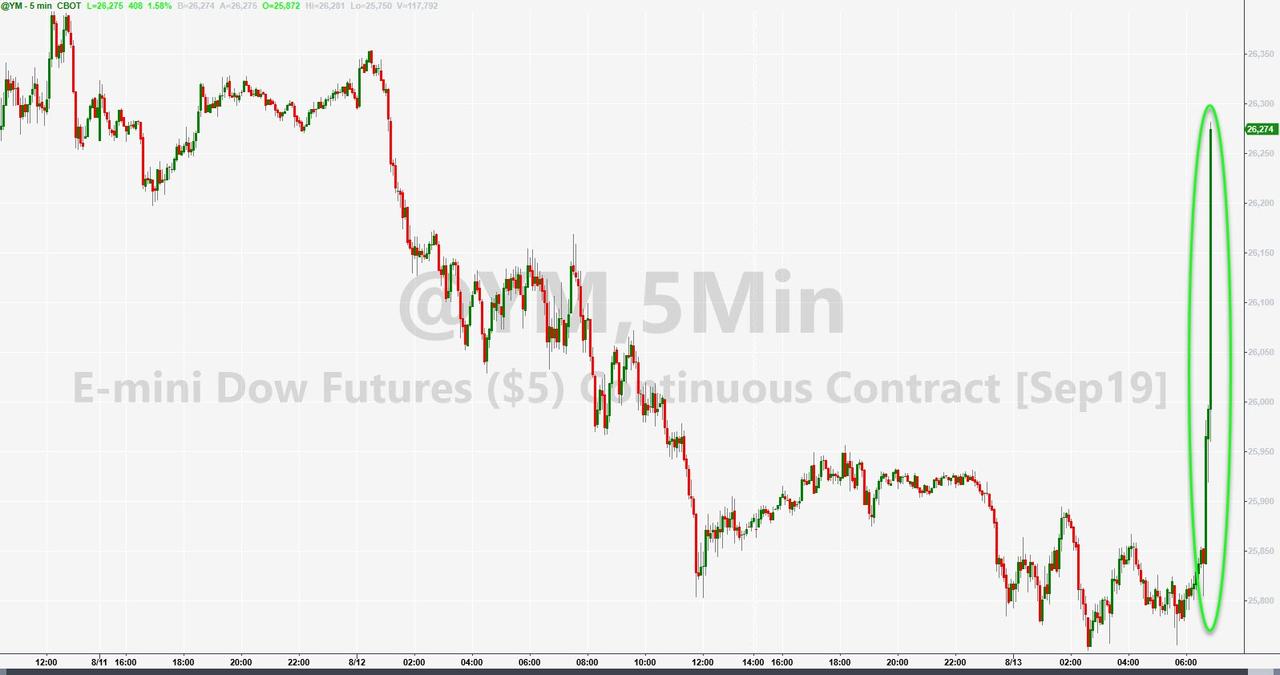
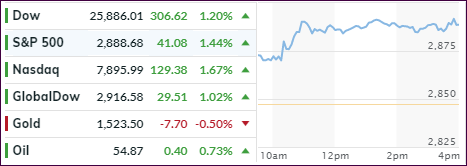
After yesterday’s lackluster session to nowhere, the markets found some upside momentum, with the ensuing relief rally reducing some of the losses sustained on Wednesday.

Trying to calm matters was St. Louis Fed President Bullard’s remarks that inter-meeting action would not be necessary, referring to the fact that there is no Fed meeting in August, and that a couple of weeks one way or the other won’t matter.

Then this gag order hit the wires: Fed Chair Powell has banned any public appearances by any Fed Board member, noting that “appearances at conferences have been canceled, all scheduled interviews have been abandoned and any comments on or off the record are outlawed.”

One analyst interpreted this unprecedented action as a reflection of two pressures:

First, economic indicators increasingly suggest the US is heading into a recession with the Dow plunging 800 points on Wednesday.

Second, relations with the White House have reached a new low, with president Trump pinning the success of his presidency upon a strong economy as a recession – Trump believes – would destroy his reputation and kill his reelection chances. As a result, Trump has – correctly – blamed the current woeful state of the global economy on the Fed. The problem is that Trump also “owned” the same state of both the economy and the market for the past two years, so any recession will be entirely his, just as Yellen (and Bernanke) intended, and shift attention away from the Fed.

On the economic side, data was dire, maybe that’s why markets rallied, as Consumer Confidence crashed in August to 92.1 from 98.4 missing all forecasts as per Bloomberg’s survey of economists. Then Housing Starts plunged by a whopping 4.0% MoM and missing expectations for a 0.2% rise. And that despite tumbling interest rates and rising mortgage applications

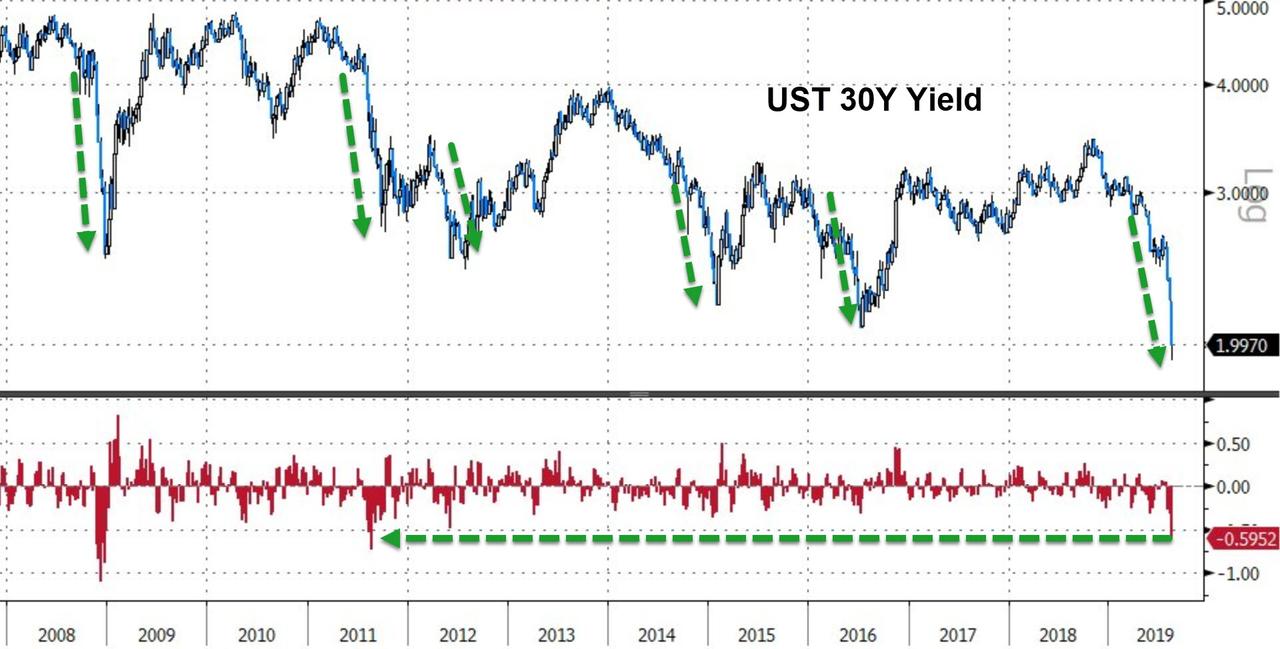
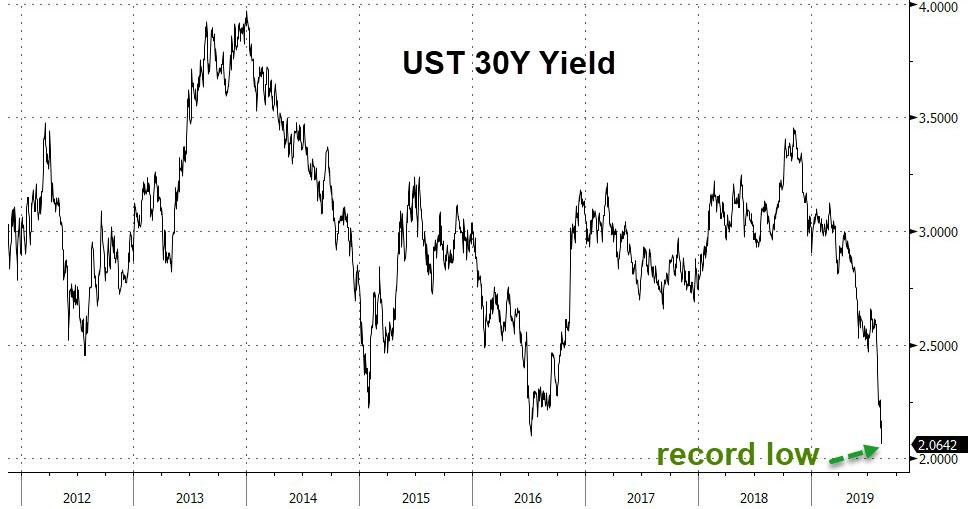
But the story of the week was bond yields, with the 30-year seeing its biggest crash since August 2011, as it fell to a record low and crossed the 2% level to the downside. As I posted before, the race to the bottom is on, and lower rates appear to be on the menu, with now $17 trillion of global bonds being negative. It’s only a matter of time until we get there as well.

That is, unless a Black Swan event suddenly reverses that trend and catapults yields considerably higher. It looks to me that volatility and uncertainty will be with us in the foreseeable future.

Read More
Weekly StatSheet For The ETF Tracker Newsletter – Updated Through 08/15/2019

Ulli ETF StatSheet Contact

ETF Data updated through Thursday, August 15, 2019

Methodology/Use of this StatSheet:

1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.

2. Trend Tracking Indexes (TTIs)

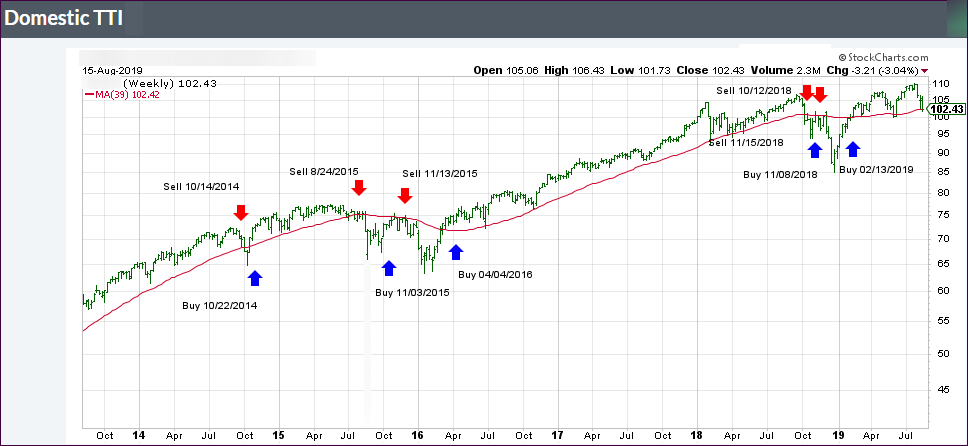
Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use a 7.5% trailing stop loss on all positions in these categories to control downside risk.

3. All other investment arenas do not have a TTI and should be traded based on  the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending on your risk tolerance.

If you are unfamiliar with some of the terminology, please see Glossary of Terms and new subscriber information in section 9.     

1. DOMESTIC EQUITY ETFs: BUY — since 02/13/2019

Click on chart to enlarge

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is now positioned above its long-term trend line (red) by +0.08% after having generated a new Domestic “Buy” signal effective 2/13/19 as posted.

Read More

Markets Find Some Footing; Retail Sales And Walmart Throw An Assist; Bond Yields Crash

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

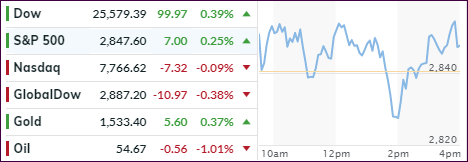
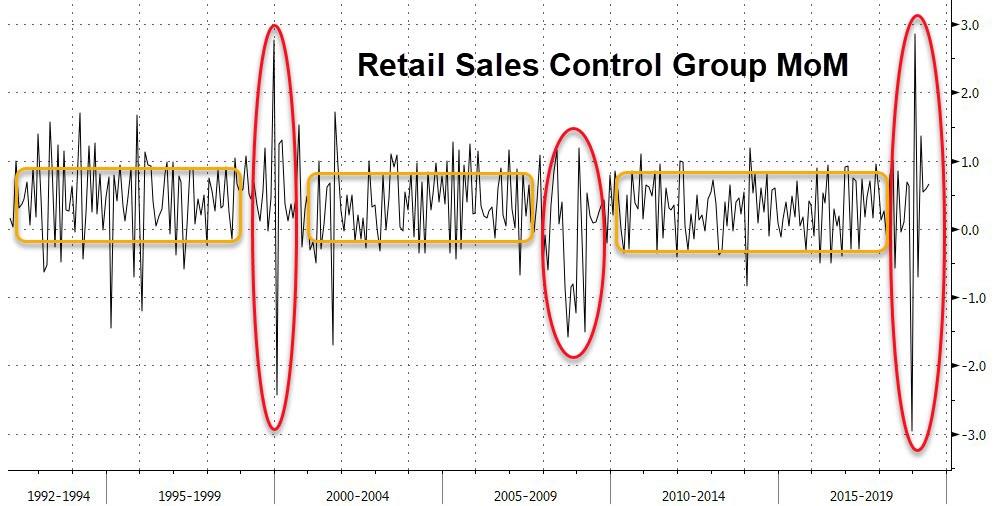
The market got an unexpected assist, which prevented a continuation of yesterday’s slide; at least for the time being. Retail sales surged in July, but that does not mean all is well, as these surges in the past have been followed by contractions. But for this moment in time, it was a positive with sales gushing +0.7% MoM vs. an expected +0.3%.

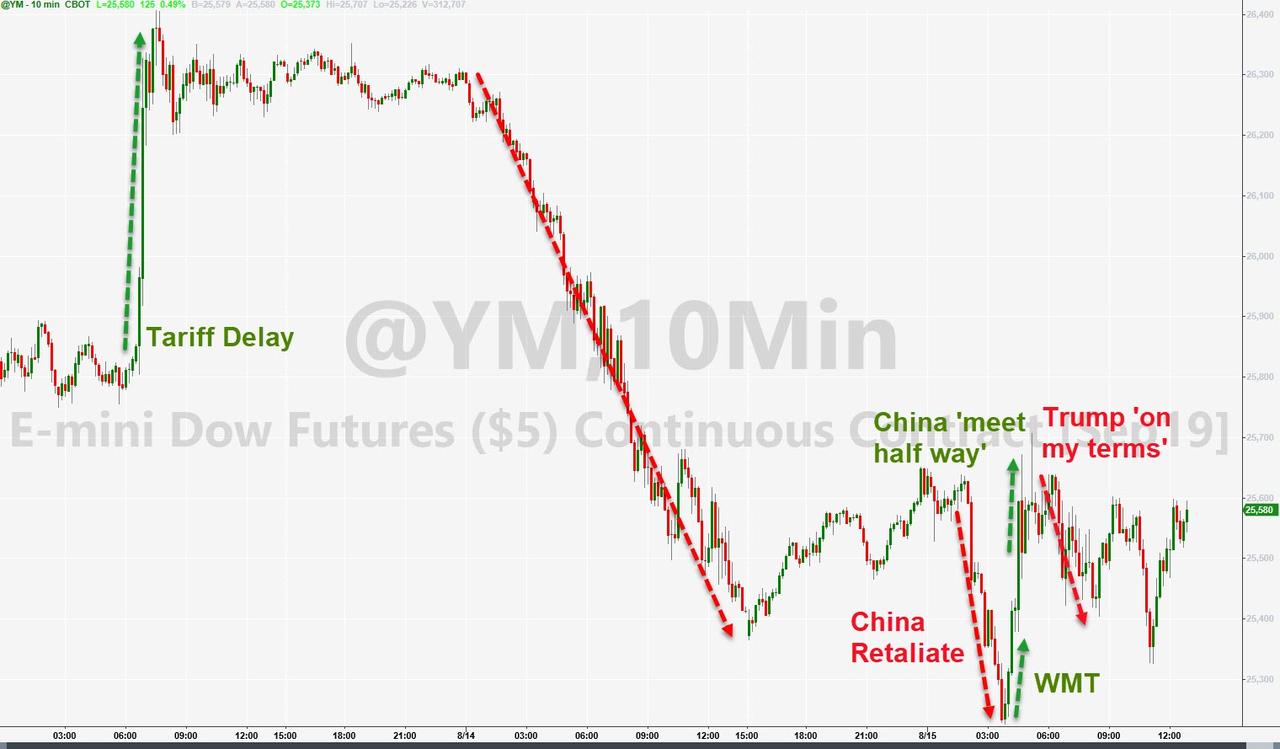
Then WalMart delivered better-than-expected second quarter earnings, as well as same store sales growth, while projecting even better numbers in the future. We also learned that US productivity increased 2.3% in the last quarter after a healthy 3.5% gain in the first 3 months.

These numbers put the US-China trade dispute on the back burner, but a spokesman for China’s foreign ministry seemed to throw out this olive branch:

“We hope the U.S. can work in concert with China to implement the two presidents’ consensus that was reached in Osaka, and to work out a mutually acceptable solution through equal-footed dialogue and consultation with mutual respect.”

This was counter to an earlier comment that threatened unspecified retaliation against Trump’s threat to impose more tariffs in September. And so, the jawboning goes on…

The WSJ reported that the European Central Bank (ECB) is in the process of revealing a stimulus package at its next meeting in September that should exceed investors’ expectations. In other words, things are so bad, economically speaking, that only a shock-and-awe effect will revive Europe’s sagging economies.

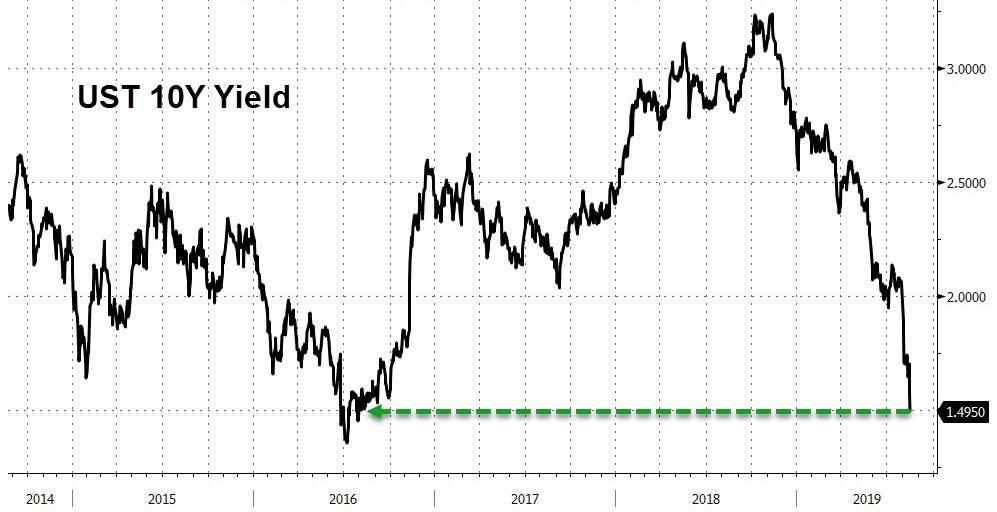
As a result, the 10-year US bond yield took a dive below the 1.5% level to touch 1.48% before rebounding. That was the lowest price in three years and confirms that the race to the bottom will accelerate. If you think, zero percent interest rates are simply insane, you are correct.

Look across the Atlantic towards Denmark, where this idiocy has now morphed into negative mortgage rates. Denmark’s 3rd largest bank is now paying people to take out a mortgage.  

In the end, the markets meandered aimlessly with the absence of bulls and bears marking a day that was clouded by confusion and uncertainty. However, it was a good environment for those of us holding the low volatility ETF SPLV, which advanced +1.11% vs. the SPY’s more meager +0.26%.

Read More

Mayhem In The Markets: Stocks Get Hammered As Roller Coaster Continues—Sell Signals On Deck

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

Yesterday’s attempt by Trump to put some lipstick on the trade pig, via a possible delay of certain tariffs, now seems to have had only a one-day effect with global realities taking front and center.

Newly released data shows a worrisome development regarding economic growth with China and Europe’s economic powerhouse Germany both presenting weak data. Chinese production slowed to 4.8% YoY, its lowest level since 2002, while retails sales came in way below consensus. But at least they’re showing positive numbers.

That can’t be said for Germany, which showed its GDP contracting -0.1% in the second quarter, the first time since the 3rd quarter of 2018. Much is contributed to the impending Brexit later this year.

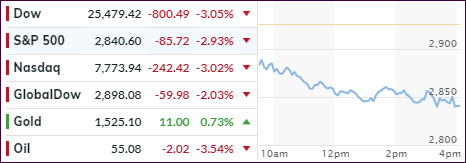
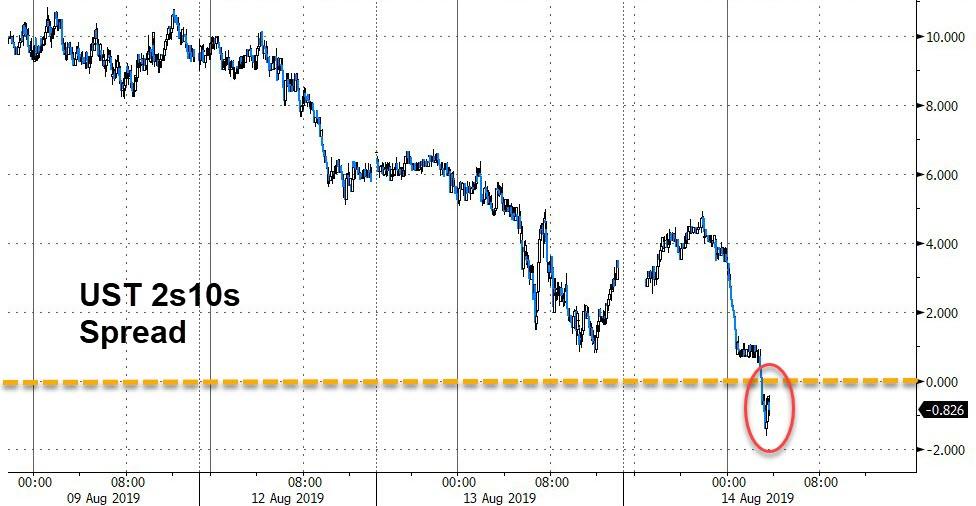
But the nail in the market’s coffin, at least for today, was the bond market where the 2/10 yield inverted for the first time in 12 years. What that simply means is that, if you invest in a 2-year bond, you will get a higher rate of return than for a 10-year bond. Insane! The 30-year bond plunged to a record low yield as well.

This type of inversion (2/10) has always signaled an upcoming recession, which is why we saw this violent market move today. The damage was widely spread, but the low volatility SPLV softened the blow somewhat (-1.98%) vs. the S&P 500’s -2.93%.

Our Trend Tracking Indexes (TTIs) came under fire as well (see section 3), and the Domestic one has reached a point that is within a hair of generating a ‘Sell’ signal. If this should materialize, we could see more downside damage with the potential of re-visiting the December lows now appearing to be a real possibility.

Of course, these days some more bad news could be interpreted as good news by the speed-reading computer algos, and we could be going back the other way.

Read More

Dangling The China Carrot—Markets Recover

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

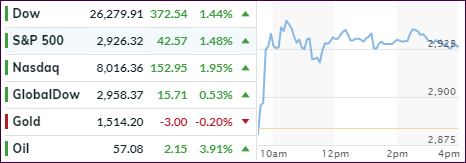
Again, it was a trading day that had me shaking my head. After yesterday’s drubbing, with the Dow losing close to 400 points, an explosive rebound sent the major indexes back into rally mode wiping out just about all of yesterday’s losses.  

It was a headline, that the speed-reading computer algos interpreted as an incredibly positive event regarding the US-China trade dispute. The statement that caused this violent bullish reaction was this one:

…some tariffs will take effect on Sept. 1 as planned, “certain products are being removed from the tariff list based on health, safety, national security and other factors and will not face additional tariffs of 10 percent,” the U.S. Trade Representative’s offices said in a statement Tuesday.

“Further, as part of USTR’s public comment and hearing process, it was determined that the tariff should be delayed to December 15 for certain articles,” the statement continued.

“Products in this group include, for example, cell phones, laptop computers, video game consoles, certain toys, computer monitors, and certain items of footwear and clothing.”

In other words, tariffs will go ahead on September 1st but tariffs on some products will be delayed until December 15 on the basis of health, safety and national security.

It looks like the algos only saw “delay” and “December 15” and the bidding war was on. If you think that this is ridiculous, you are correct, but this is the insane market environment we are living in.

In the end, the S&P 500 ended up close to where we left off on Friday with nothing gained but also nothing lost. It promises to be a hot August, as global/trade uncertainties will continue to affect volatility and market direction.

Read More