Below, please find the latest High-Volume ETF Cutline
report, which shows how far above or below their respective long-term trend
lines (39-week SMA) my currently tracked ETFs are positioned.
This report covers the HV ETF Master List from Thursday’s
StatSheet and includes 322 High Volume ETFs, defined as those with an average
daily volume of more than $5 million, of which currently 206 (last week 234)
are hovering in bullish territory. The yellow line separates those ETFs that
are positioned above their trend line (%M/A) from those that have dropped below
it.
In case you are not familiar
with some of the terminology used in the reports, please read the Glossary of Terms.
If you missed the original
post about the Cutline approach, you can read it here.
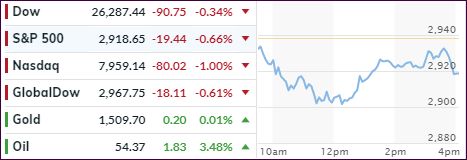
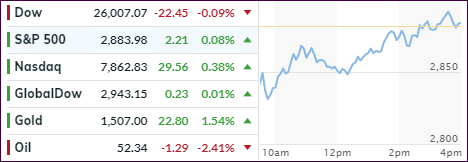
It ended up being a mixed Friday, as the major
indexes did an early swan dive but, despite recovering some of the losses, they
still closed in the red. It was a wild week, which could have ended up far worse,
but as it turned out, the S&P 500 only surrendered -0.66% with the other 2
major indexes sporting similar numbers.
Starting the session to the downside were remarks
from Trump suggesting that a resolution with China was not forthcoming. He
added that “things are doing very well with China,” but that “he’s not
ready to make a deal.” Throwing more fuel on the fire were his remarks that
next month’s talks might be cancelled.
Equities reacted very negatively, which prompted
the While House to backpedal earlier remarks regarding Huawei that “we’re
not doing business with Huawei.” The clarification came that “the President
was referring to ONLY ban Federal Departments buying from Huawei,” and not
public corporations.
The markets did an about
face and quickly headed north with bond
yields following suit. In the end, this provided enough ammunition to drive
the major indexes back towards the unchanged line thereby averting what appeared
to be an accelerating plunge in the making early on.
“Scrambling back” was the theme of the week,
as volatility surged, giving an assist, at least temporarily, to the bearish
crowd. The only bright and shining light all week was gold,
which we added to our holdings, and which surged over 4% to conquer the $1,500
level—and having its best week in over 3 years.
We’ll find out next week, if there are more bearish
surprises in store for us.
1. From the universe of over 1,800 ETFs, I have selected only those with a
trading volume of over $5 million per day (HV ETFs), so that liquidity and a
small bid/ask spread are assured.
2. Trend Tracking Indexes (TTIs)
Buy or Sell decisions for Domestic and International ETFs (section 1 and
2), are made based on the respective TTI and its position either above or below
its long-term M/A (Moving Average). A crossing of the trend line from below
accompanied by some staying power above constitutes a “Buy” signal. Conversely,
a clear break below the line constitutes a “Sell” signal. Additionally, I use a
7.5% trailing stop loss on all positions in these categories to control
downside risk.
3. All other investment arenas do not have a TTI and should be traded
based on the position of the individual
ETF relative to its own respective trend line (%M/A). That’s why those signals
are referred to as a “Selective Buy.” In other words, if an ETF crosses its own
trendline to the upside, a “Buy” signal is generated. Since these areas tend to
be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending
on your risk tolerance.
If you are unfamiliar with some of the terminology, please see Glossary of Termsand new subscriber information in section 9.
1. DOMESTIC EQUITY ETFs: BUY
— since 02/13/2019
Click on chart to enlarge
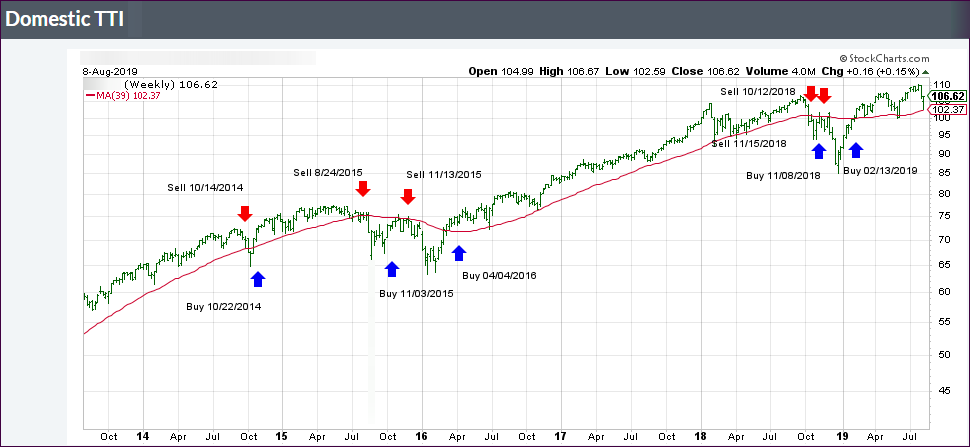
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is now positioned above its long-term trend line (red) by +4.30% after having generated a new Domestic “Buy” signal effective 2/13/19 as posted.
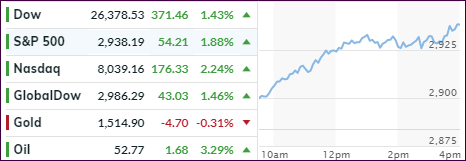
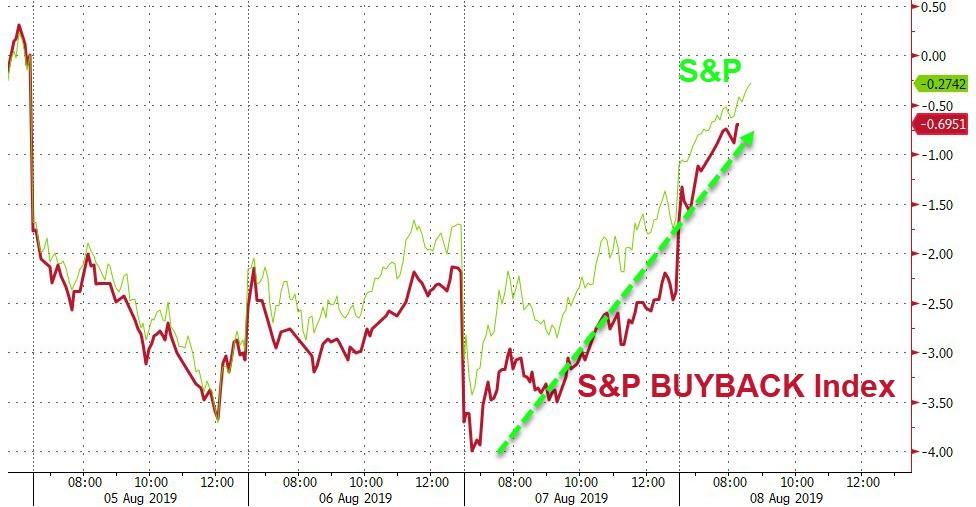
Two forces combined to pull
the markets out of the doldrums after Monday’s drubbing. For one, we saw
corporate buybacks
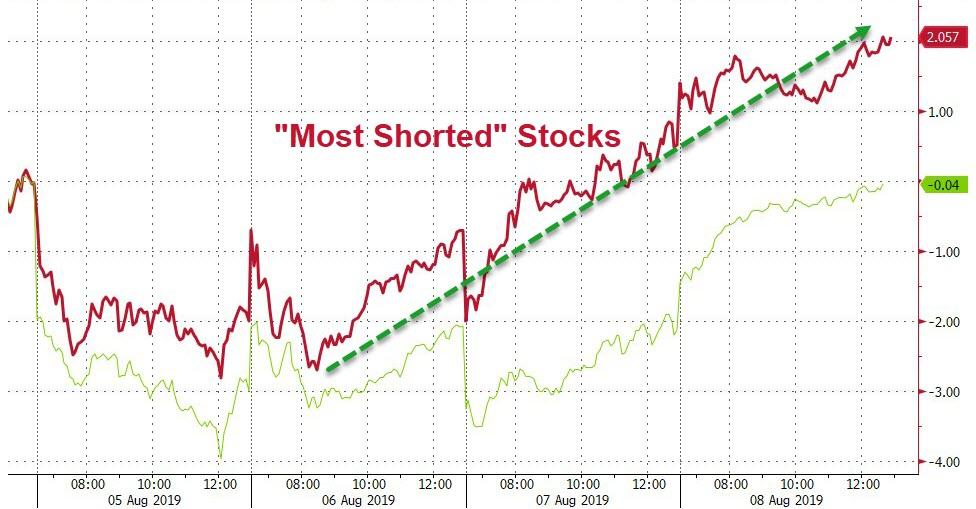
pick up speed, and two, a giant short-squeeze,
now its third day, threw an assist to push the S&P 500 slightly above last
Friday’s close. Both, the Nasdaq and S&P are back in the black for the week.
Setting the stage early on,
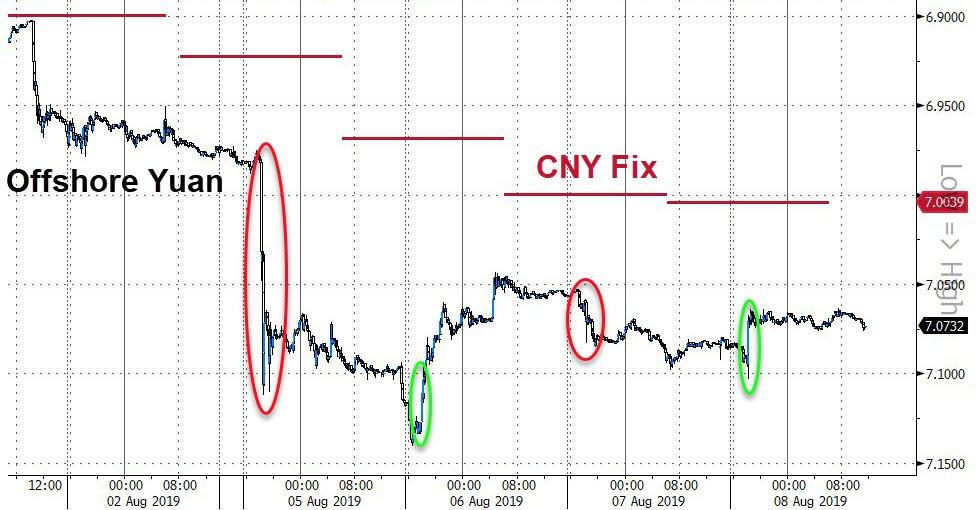
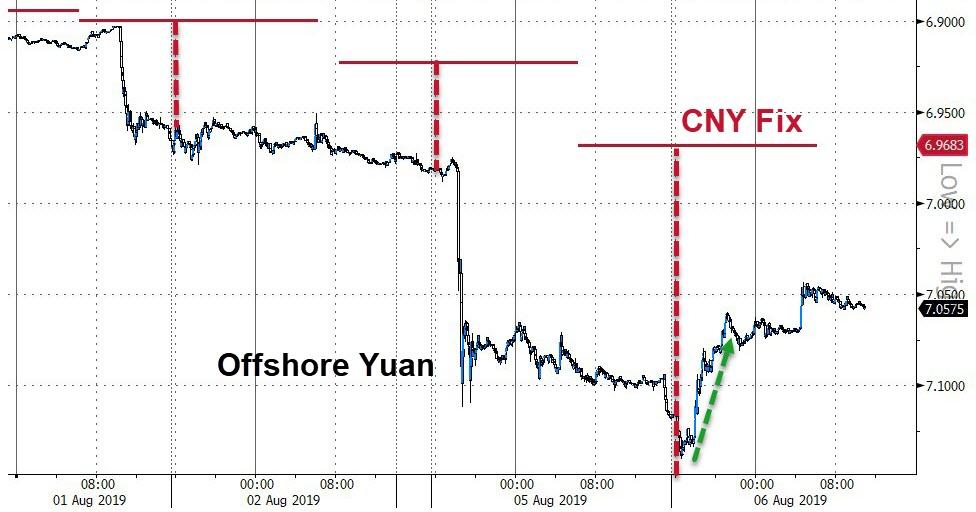
was China’s Yuan, the peg of which is still set at the weakest
level since 2008 but slightly higher than feared. That helped steady markets worldwide,
as global growth fears subsided a tad and allowed the Global Dow to finally
show a gain after the recent spanking.
While the markets seem to have
stabilized for the time being, traders are still uneasy, as it would not take much
to turn this trend around and retest Monday’s lows. Soothing the mood on Wall Street,
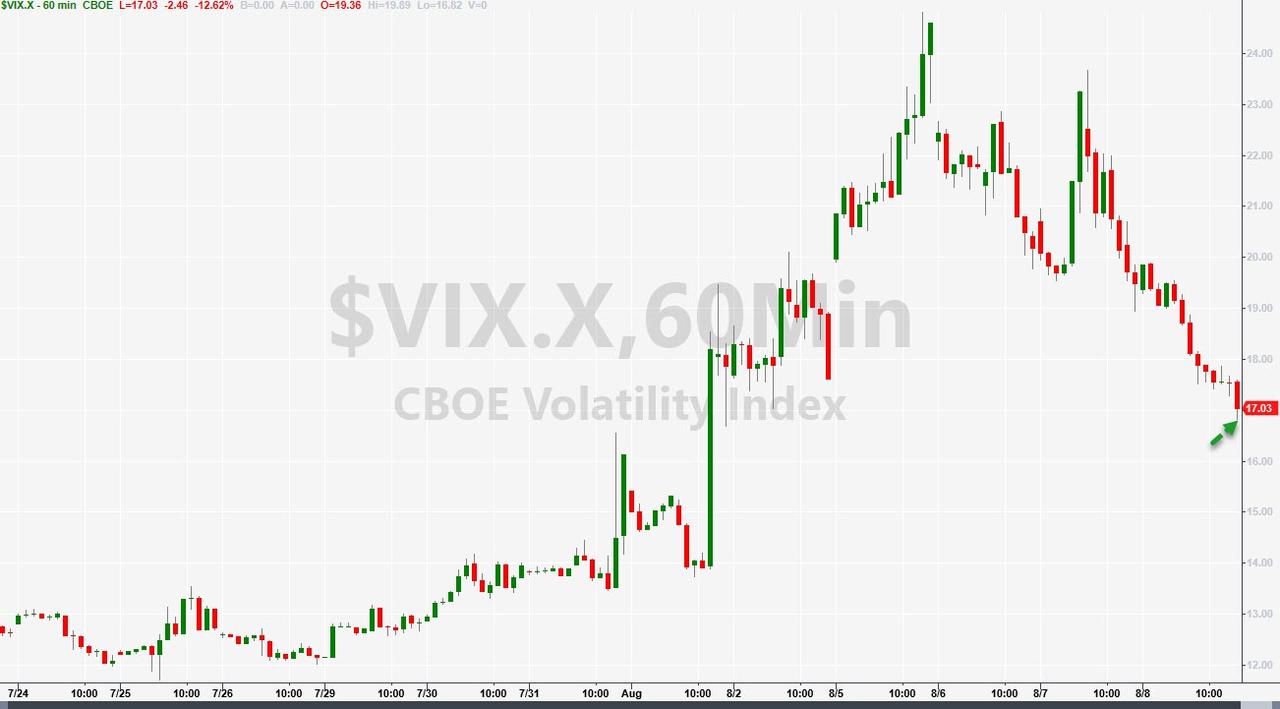
however, was the volatility
index (VIX), which dropped back from its recent highs to settle at a not so
nerve-wrecking 16 level.
In the end, for us trend followers,
no damage was done, and the major trend direction remains bullish, keeping us on
board until that fact materially changes.
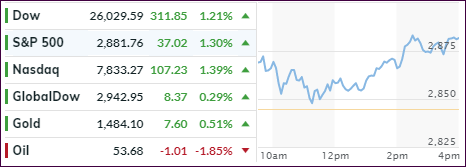
The markets lucked out, as
an early sharp sell-off found some footing, after which buyers stepped in to scoop
up assets at lower prices with all losses being wiped out by the end of the
session. Whether that was just a one-day outlier, or a resumption of the bullish
trend, remains to be seen.
The Nasdaq led the major
indexes, with the S&P barely moving into the green, while the Dow was left
behind and remained a fraction in the red.
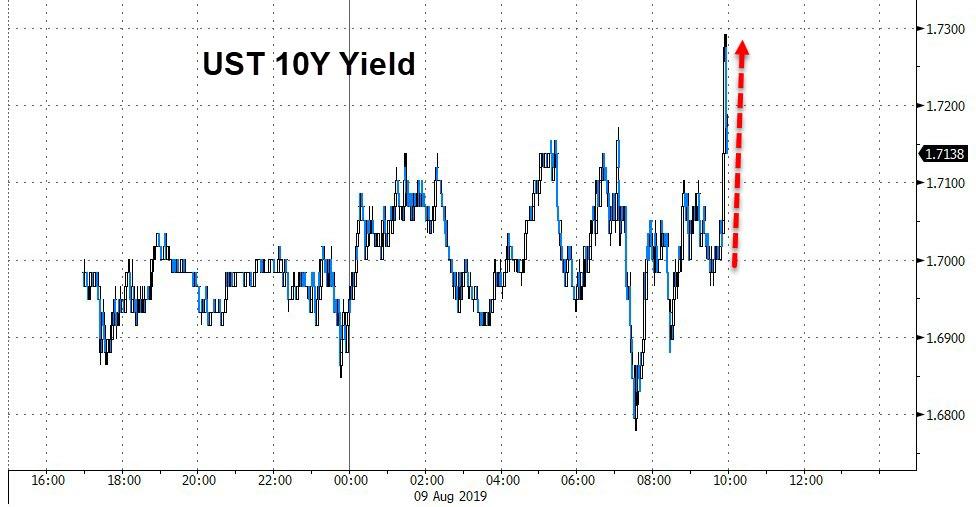
Bond yields took a sharp dive
early on with the 10-year touching 1.62%, then recovering and ending up 1 point
at 1.72%. Still, it appears the race to the bottom is on, meaning that yields
eventually may end up in negative territory.
On a global scale, we know
that some $14 trillion of bonds, or 25% of the market, are yielding negative
rates already. At one point in the past, this was considered a short-term aberration
but now has become an accepted (outside the US) common practice. This is simply
insanity and will not end well.
The recent surge in volatility
can have a devastating effect on equities, which one portfolio manager summed
up as follows:
“An extended period of low
volatility like we have seen in recent years significantly increases leverage
and risk-seeking behavior,” he said in an interview.
“When volatility turns like
it has, people often need to sell assets to meet margin calls. That’s what
makes this so combustible.”
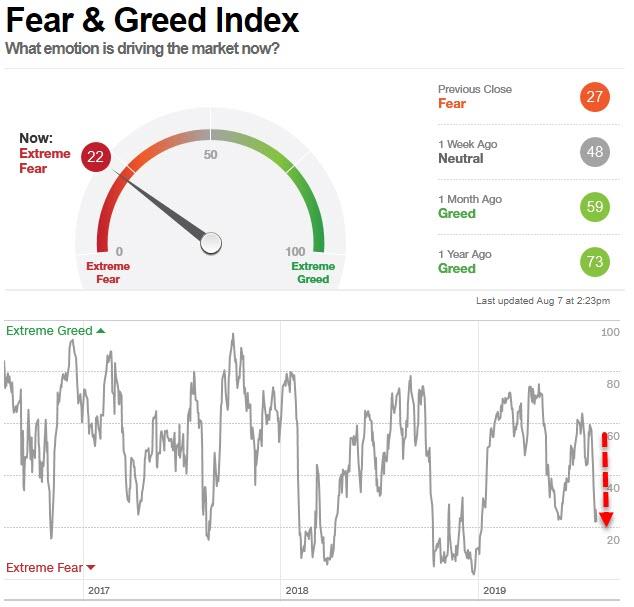
With the actions of the last
week, investor sentiment has collapsed from “euphoric greed” just a month
ago to “extreme fear,” as this chart
shows (thanks to ZH).
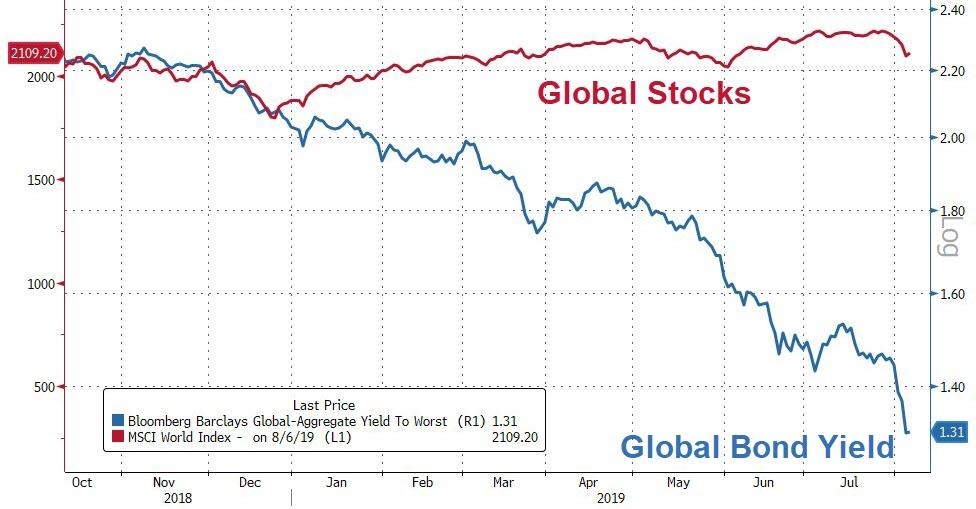
Even on a global basis,
stocks and bonds remain decoupled
by a huge margin. Knowing that bonds represent the “smart money” and stocks the
“dumb money,” we can guess well how this will turn out.
While the initial morning
rebound faded mid-day, buyers stepped in subsequently and pushed the major indexes
out of the doldrums and into a solid green close.
Helping matters was China stabilizing
the problem child that caused yesterday’s panic selling, namely the Juan. The
PBOC (China’s main bank) fixed
the Juan at 6.9683 per dollar, which was marginally stronger than the 7.00 “red
line in the sand.”
That reduced downside market
pressures with traders finally being able to steady their nerves after the Dow’s
767-point plunge. The mood, however, remains fragile, as Wall Street participants
are keenly aware that a stray headline or misunderstood presidential tweet
could kick market turmoil back into high gear.
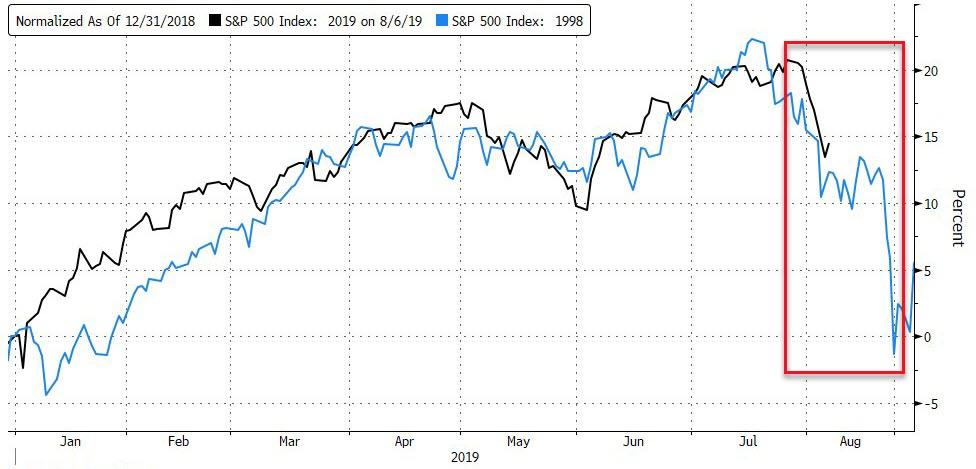
When looking at this
updated chart demonstrating the similarities between the 2019 and 1998
S&P 500 performance, you have to admit that it is eerily similar. This is
not to say that history will repeat itself but, so far, it seems to be a
possibility.