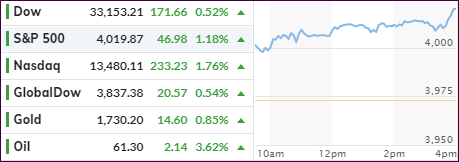
[Chart courtesy of MarketWatch.com]
- Moving the markets
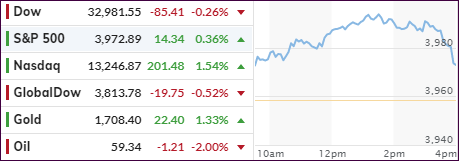
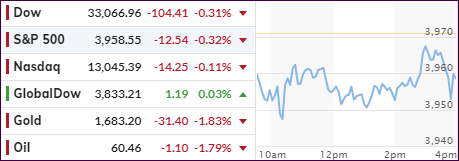
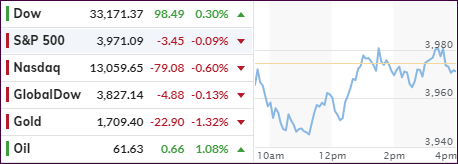
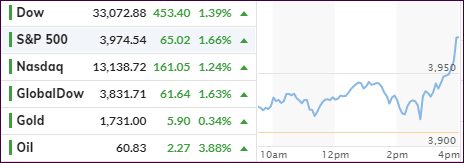
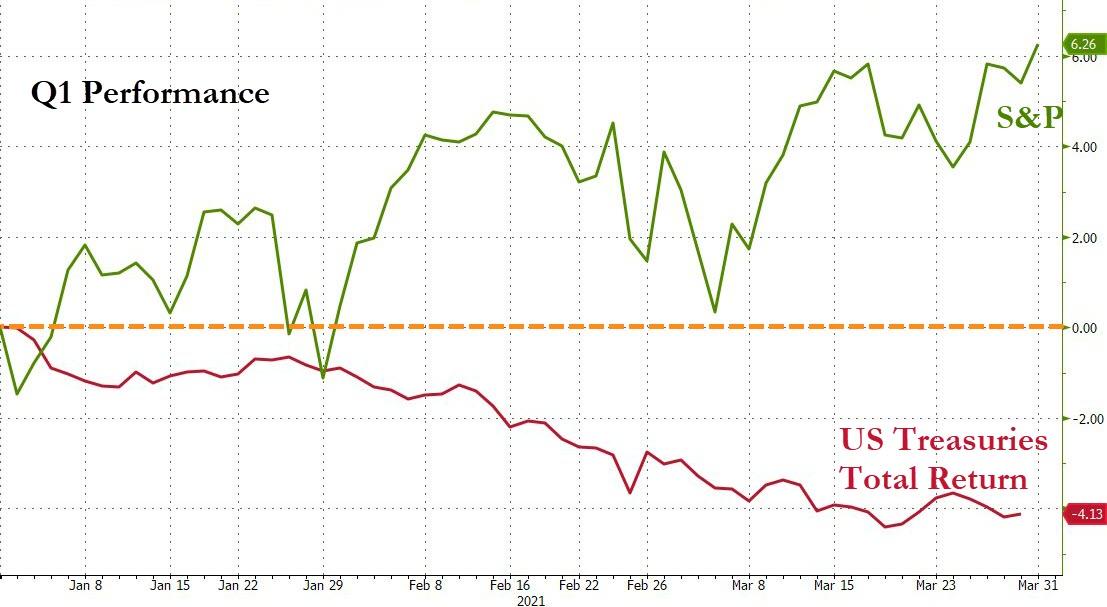
The major indexes greeted the month of April with a bang and a solid close in the green. The Dow lagged somewhat, but the S&P 500 made up for it by conquering its 4,000-milestone marker without hesitation.
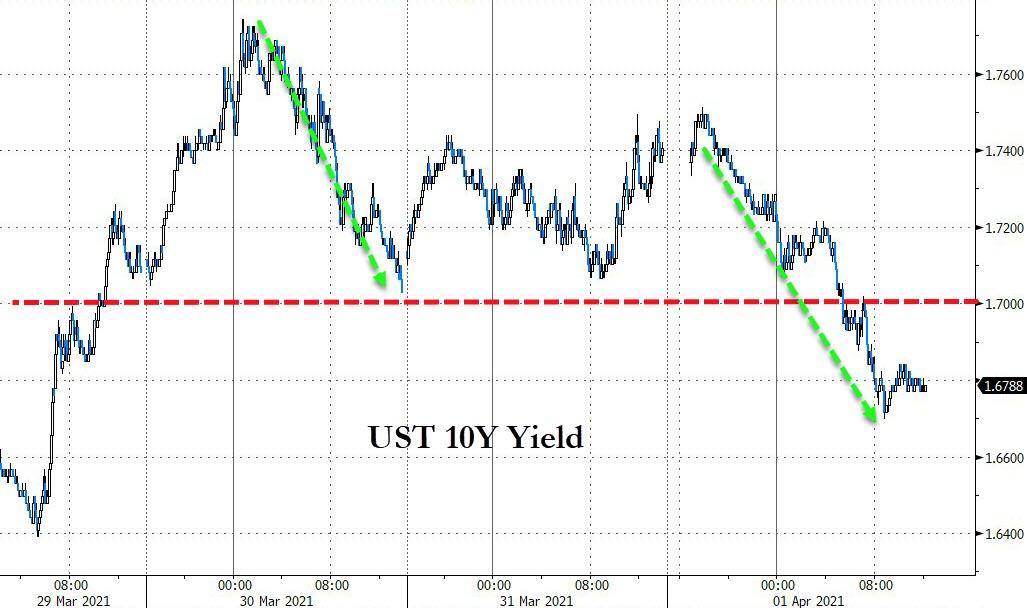
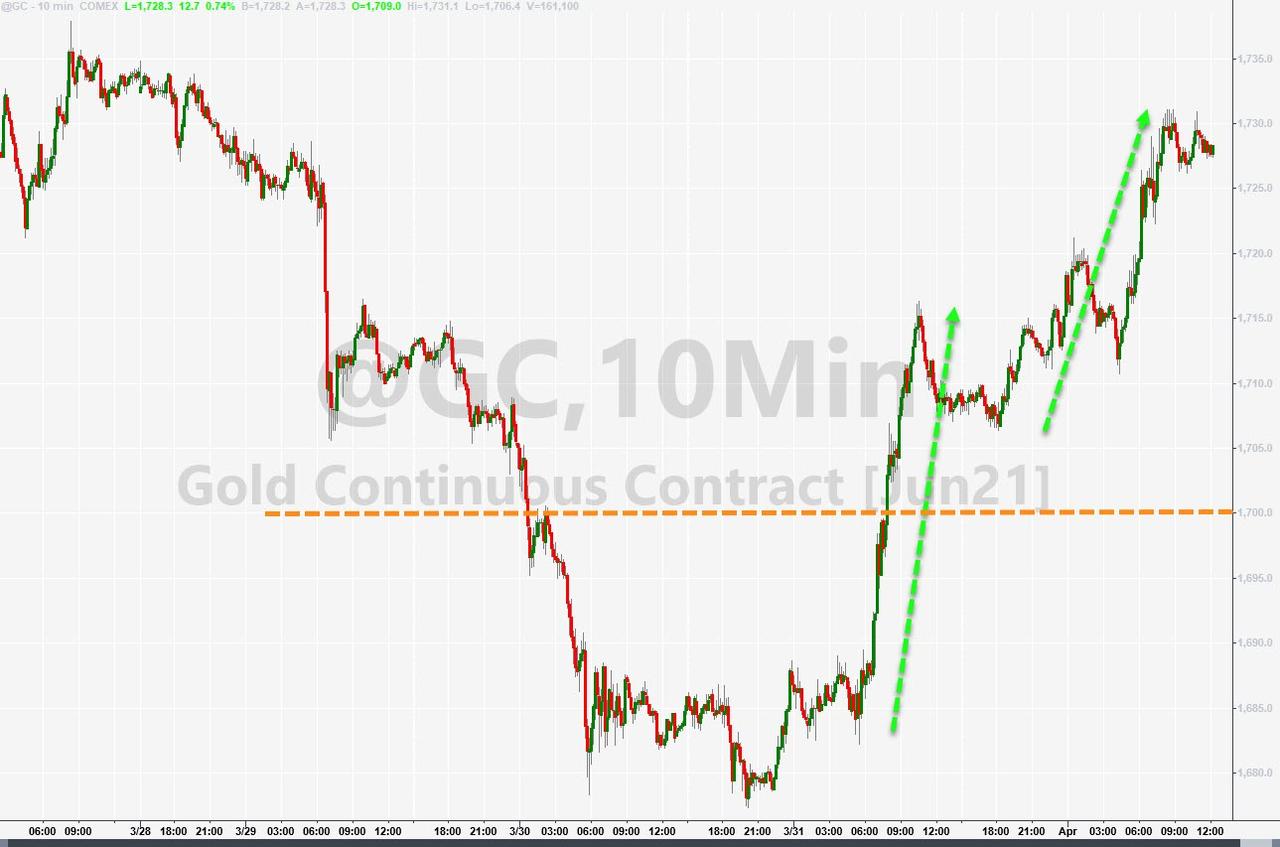
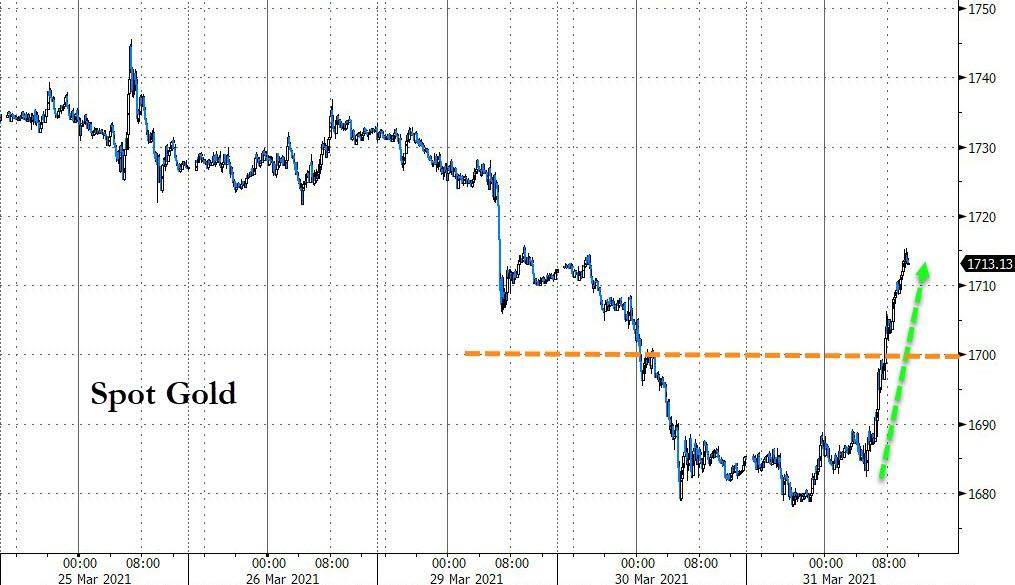
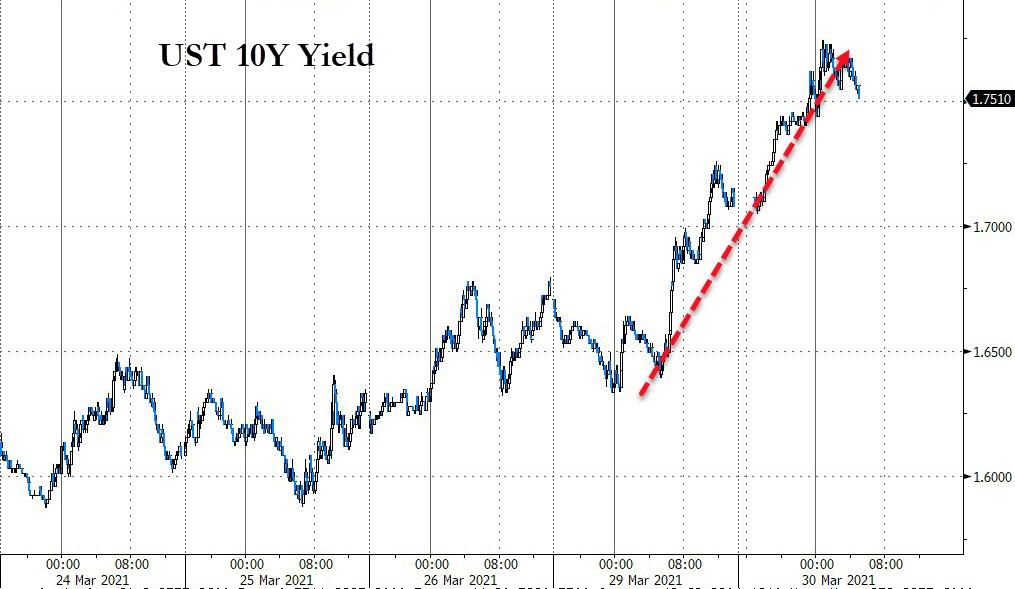
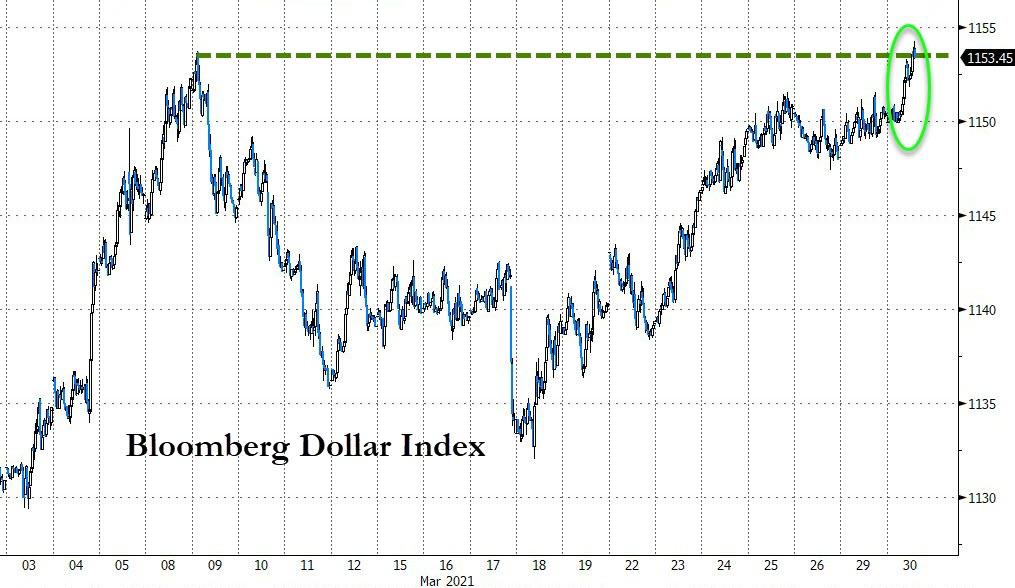
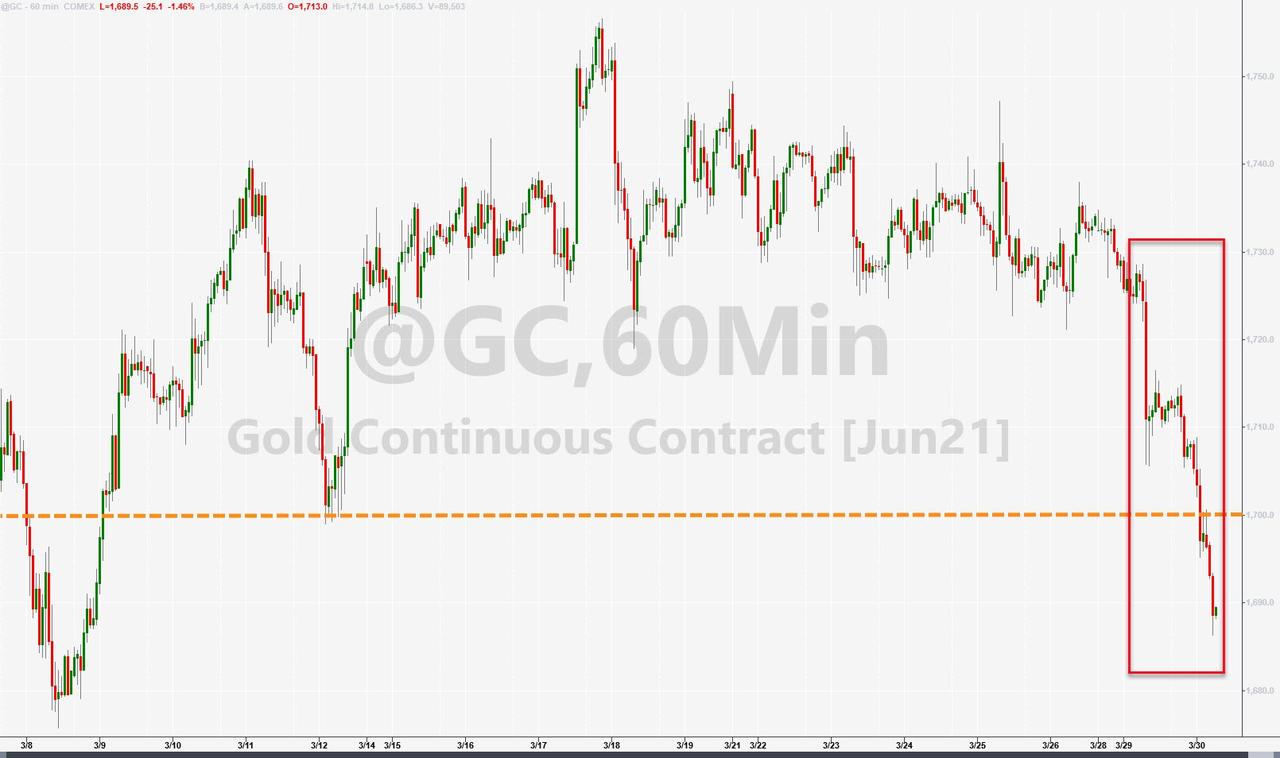
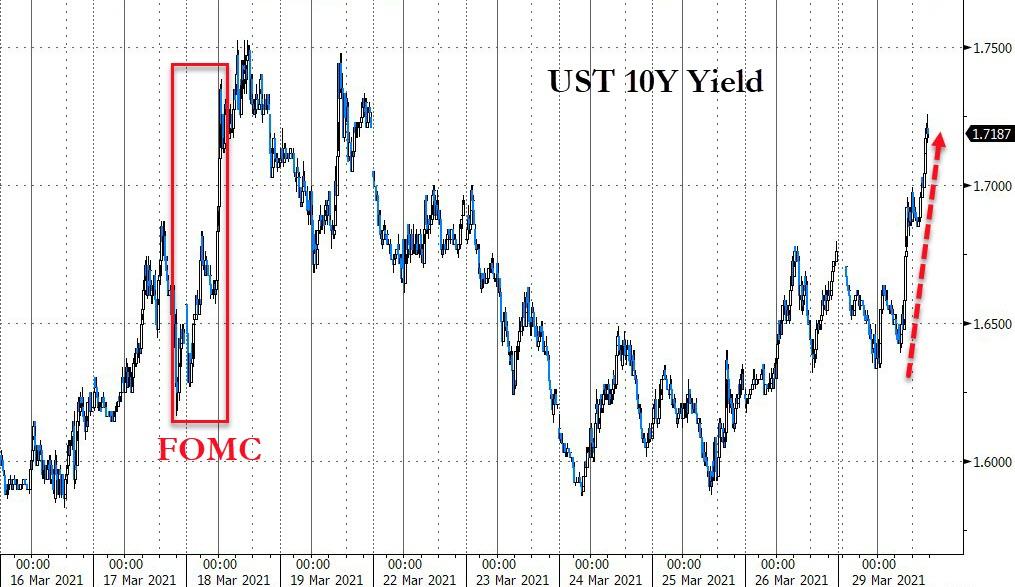
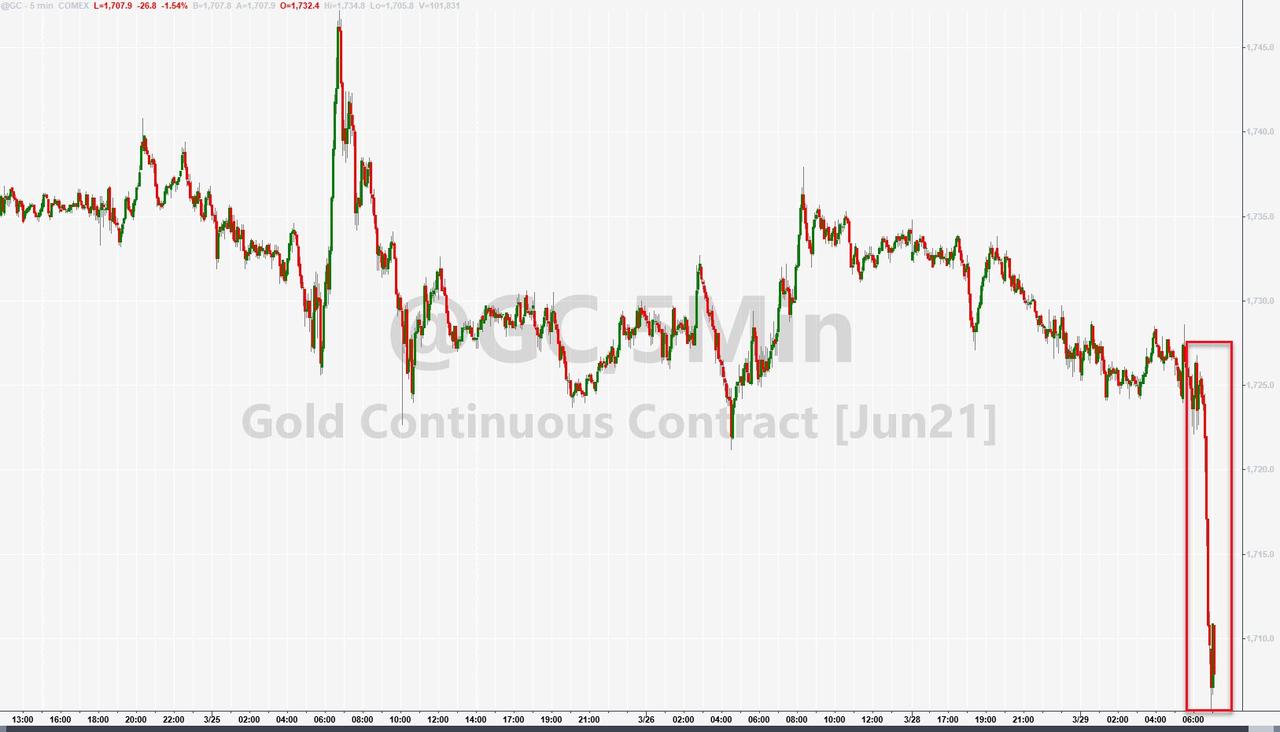
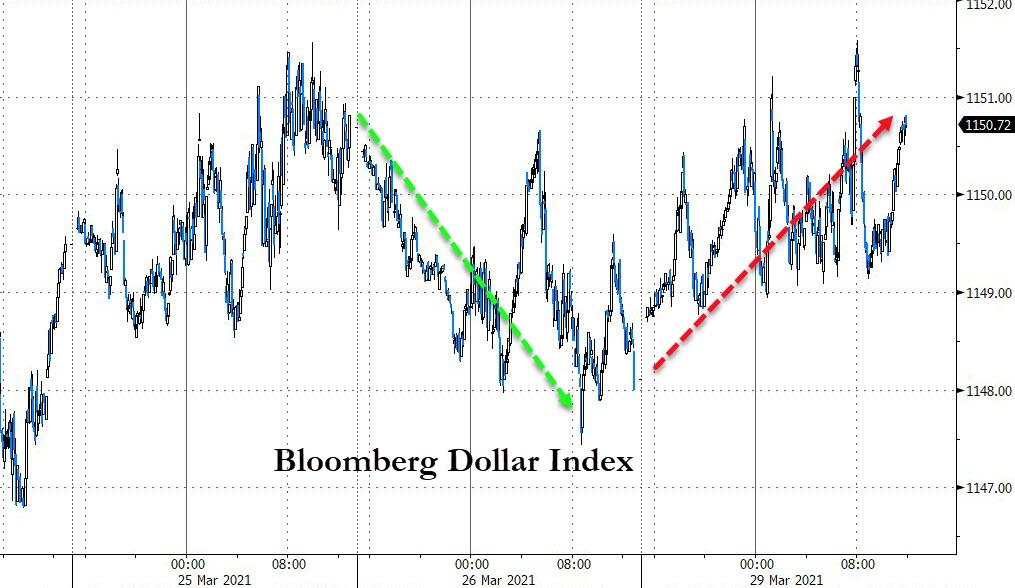
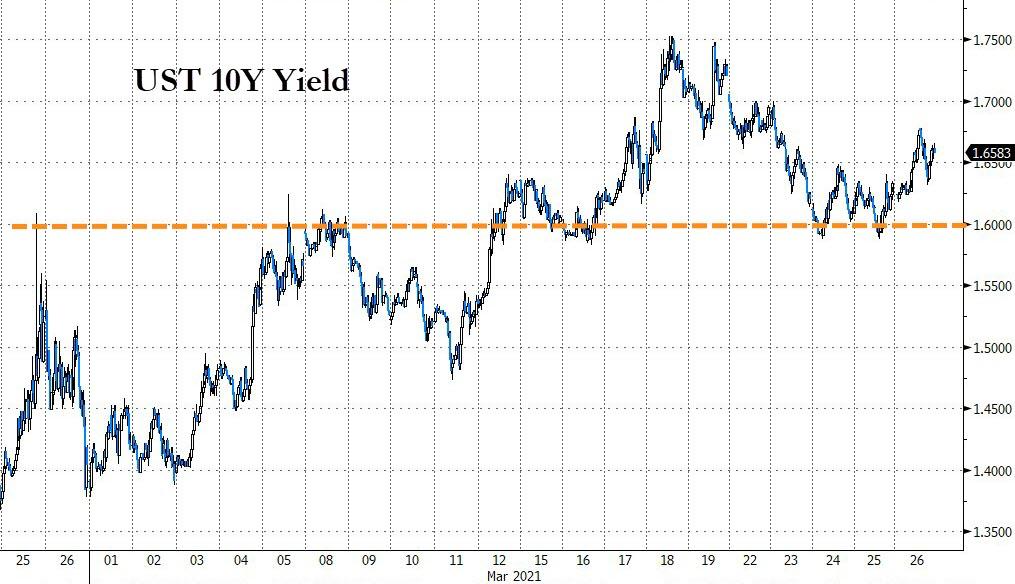
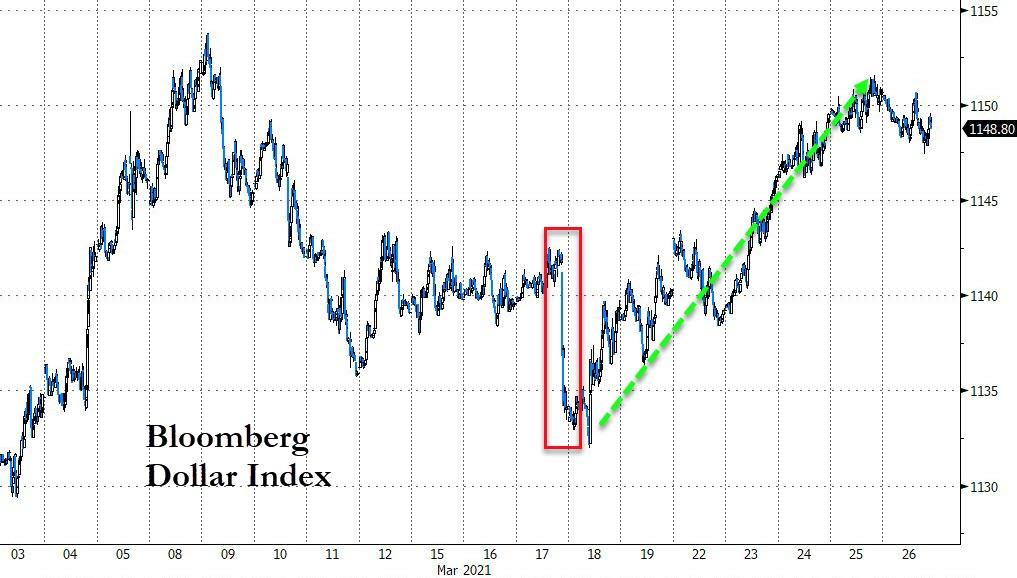
Tech stocks took the lead today and were powered by lower bond yields and a declining US Dollar, both of which combined to push gold higher with the GLD ETF adding a robust +1.27%.
The continued but spotty reopening of the US economy was a positive for equities, but concerns linger as to when we might reach the end of the coronavirus tunnel. However, the main driver is the ongoing reckless fiscal and monetary support, which is unprecedented and presents potential consequences that nobody likes to address.
On the other hand, higher taxes could pose a threat to corporate earnings and subsequently to stock prices. These concerns, while present, are largely ignored with most traders focusing on the more immediate benefit like maintaining the bullish theme.
On the economic front, the main number for the day, namely first-time filings for jobless benefits, rose from the prior week’s 684k to 719k. In other words, there is no consistent improvement other than an occasional temporary drop. Looking at the big picture, there are still over 18 million Americans getting jobless benefits. Ouch!
Tomorrow, Good Friday, the markets will be closed, but the Payroll Report announcement will be on deck. The only asset class, which will trade until noon are bonds, and they might respond in a big way (negatively), should the report hit the whisper number of 1.8 million, which would be triple the expectations. In that case, Monday’s session might see fireworks.
Read More