[Chart courtesy of MarketWatch.com]
- Moving the markets
It had to happen eventually, and today was the day when Atlanta Fed President Bostic finally broke away from the common theme, and confirmed what I have been saying all year:
Price surges caused by supply-chain disruptions, or the reopening of the services sector are likely to last, i.e., they are not transitory, and seem to be broadening to more parts of the economy, i.e., getting worse.
In other words, inflation will be with us and will not be of a transitory nature. While other Fed officials are singing a different tune, I would not be surprised if they adopt this type of narrative—eventually.
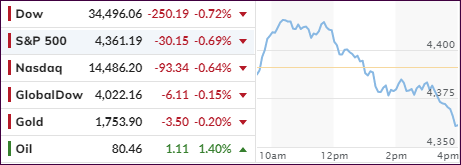
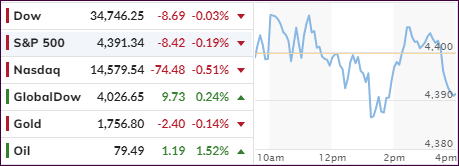
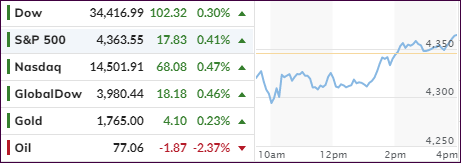
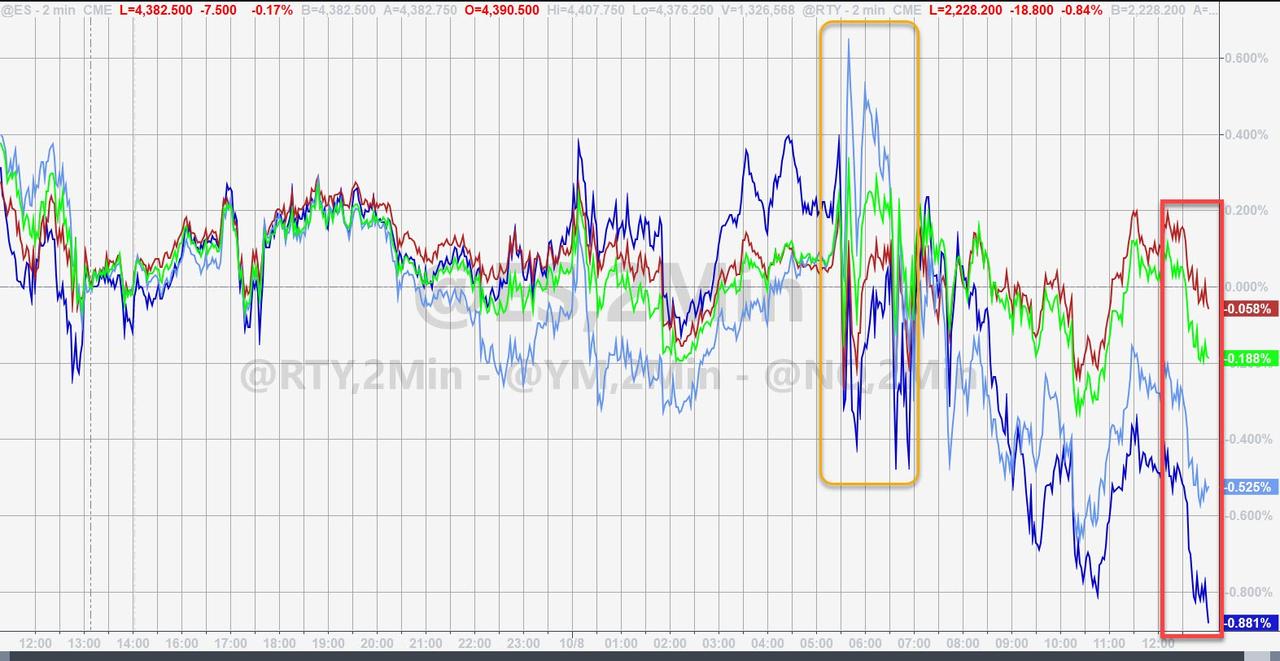
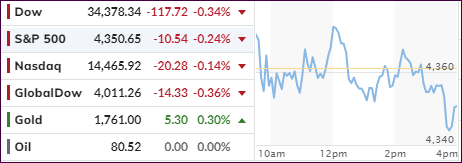
The markets continued to be affected by volatility, and the result was sloppy and choppy trading, with dip buyers finding no reason to step in and clean up this mess. With a key inflation reading (CPI) ahead of us, as well as retails sales numbers, and the earnings season on deck, the major indexes slid for the third straight session.
Adding to this uncertainty is Wednesday’s release of the minutes from September’s FOMC meeting, which will be dissected for any clues about the Central Bank’s plans to reduce easy monetary policy.
Headwinds abound, and traders are looking for directional guidance wherever they can find it, with slower economic growth ahead being a major threat.
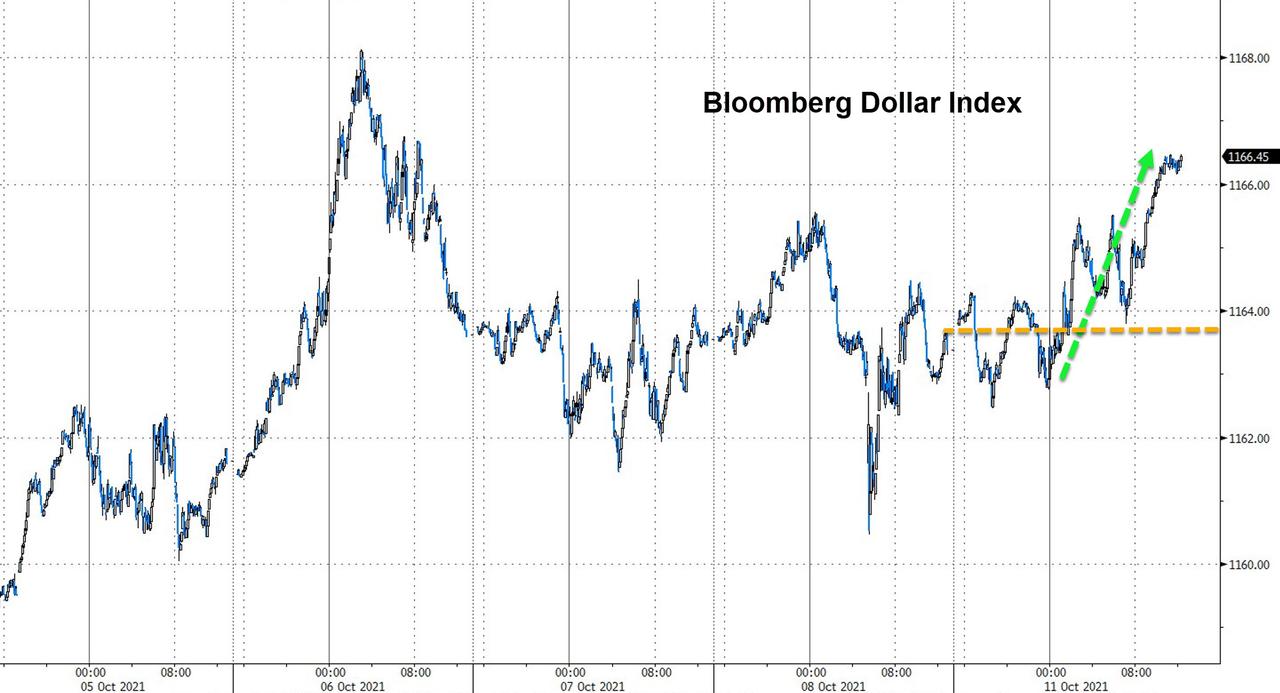
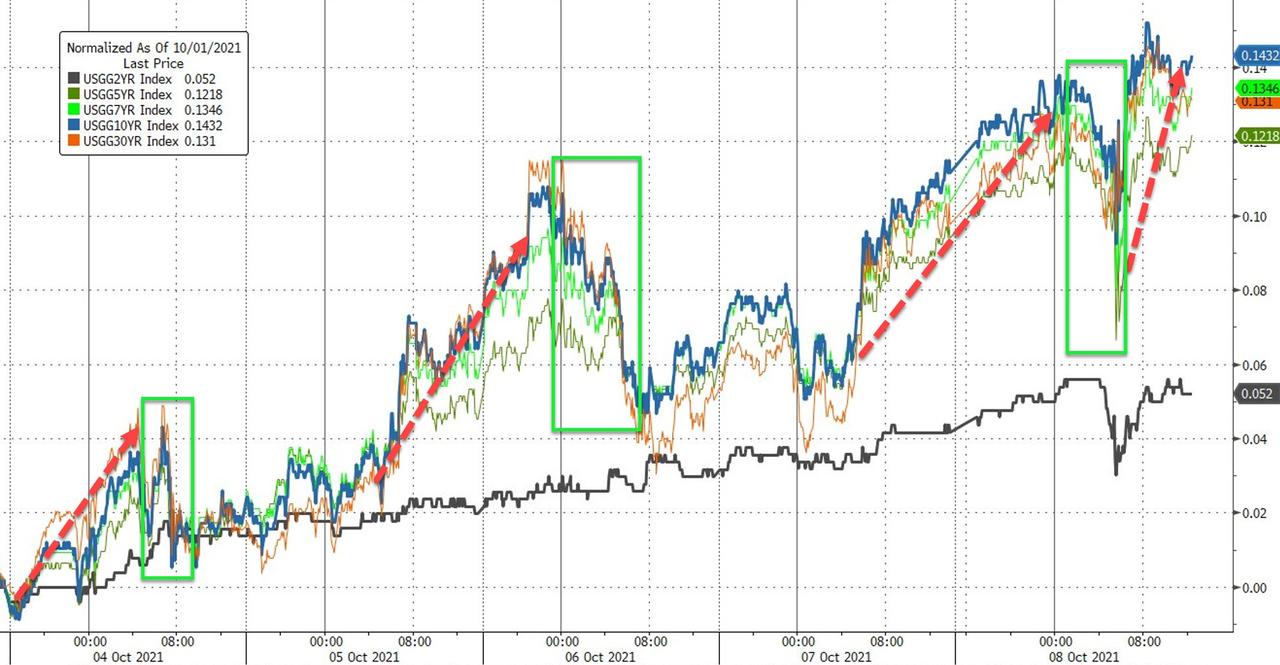
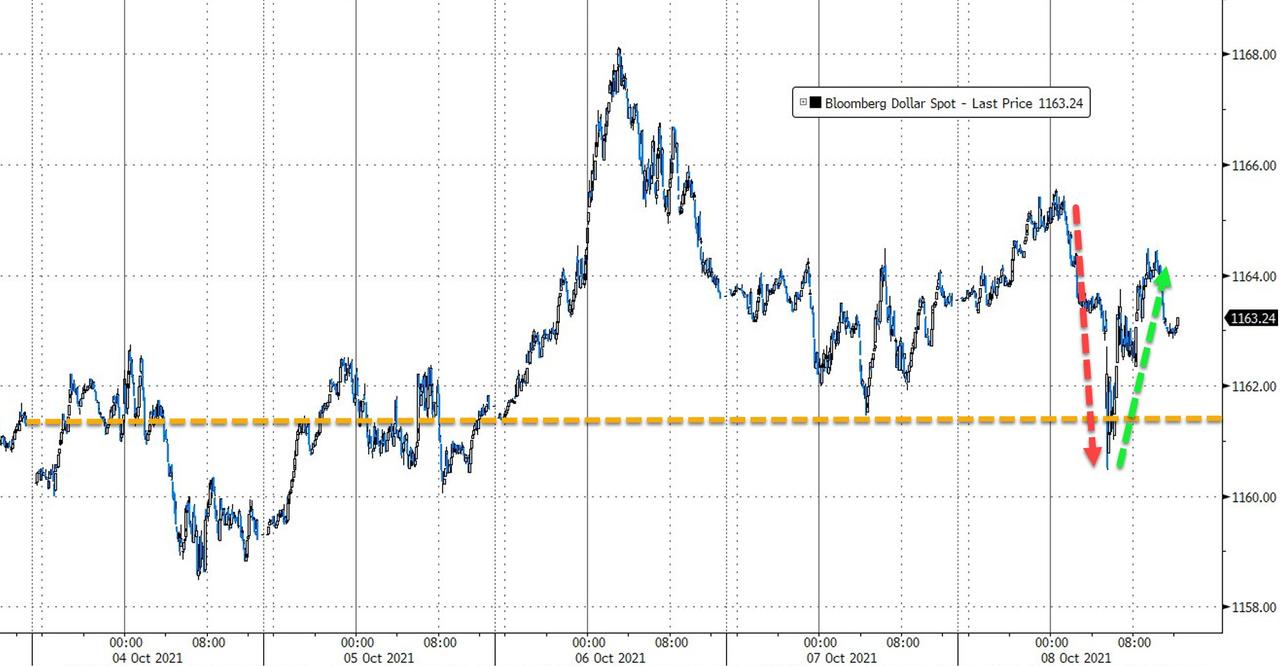
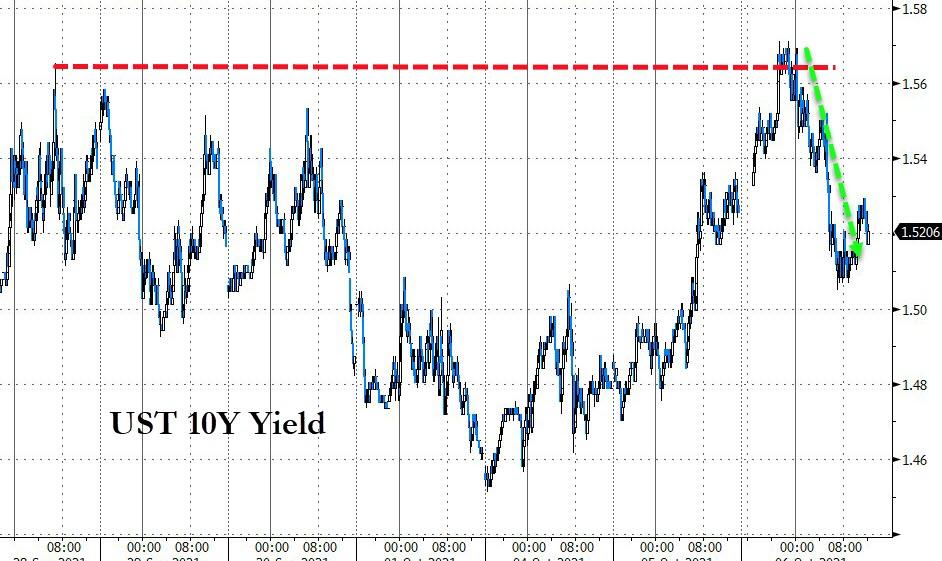
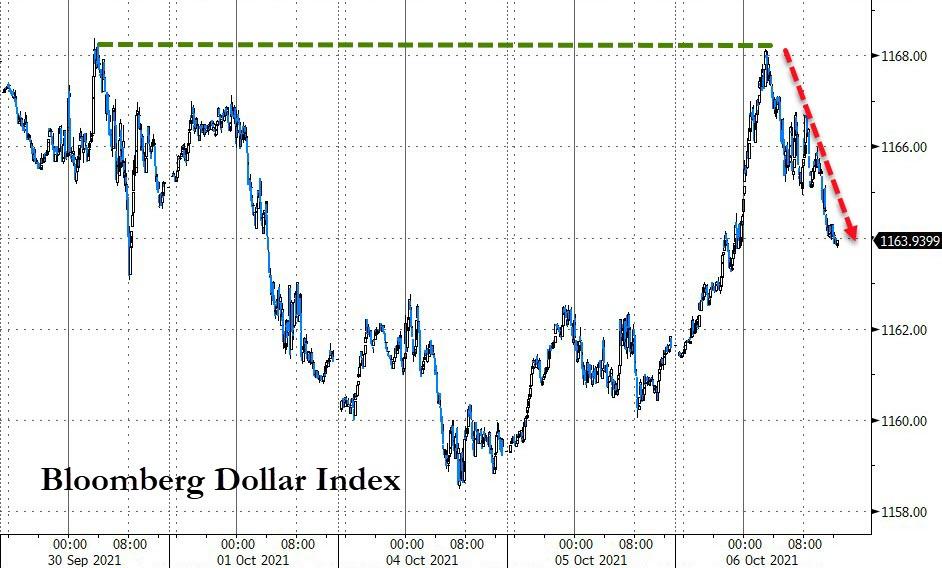
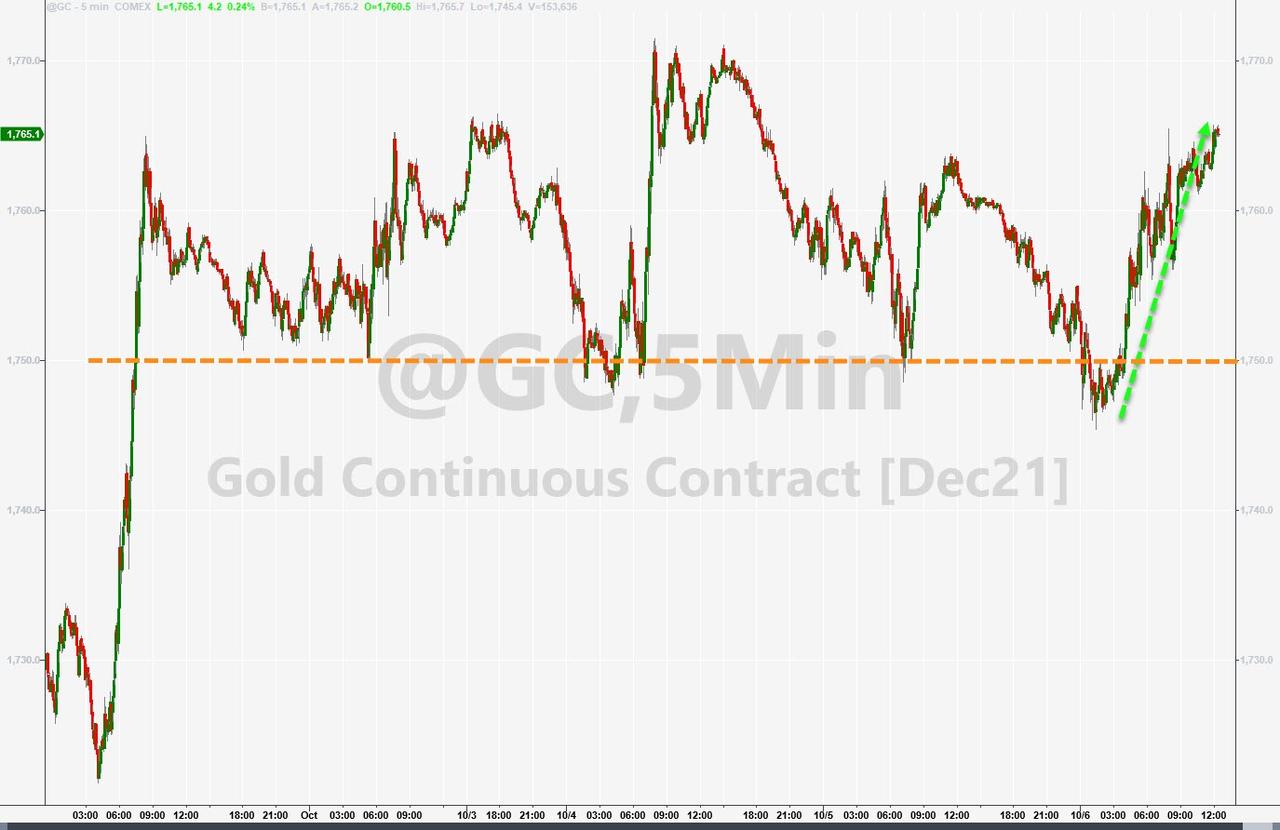
During this session, the US Dollar ended up a tad, as 10-year bond yields slipped to 1.573%, which allowed Gold to edge higher by a moderate 0.32%. While this day was volatile, it was quiet with tight trading ranges prevailing across the indexes, but this will likely change given the variety of upcoming events.
Read More