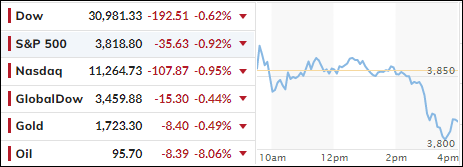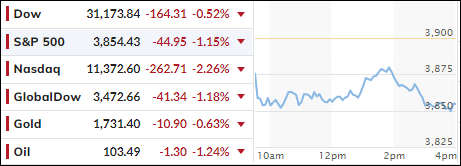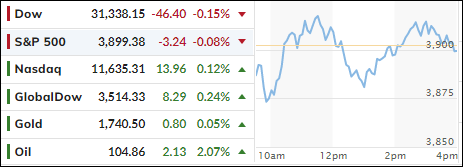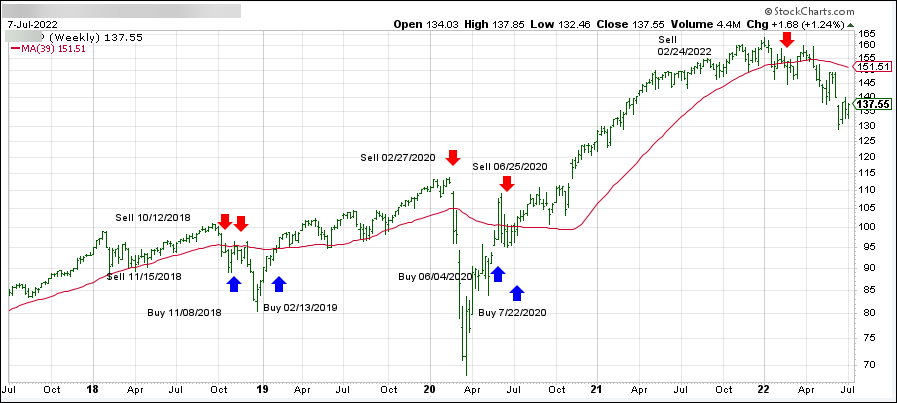
[Chart courtesy of MarketWatch.com]
- Moving the markets
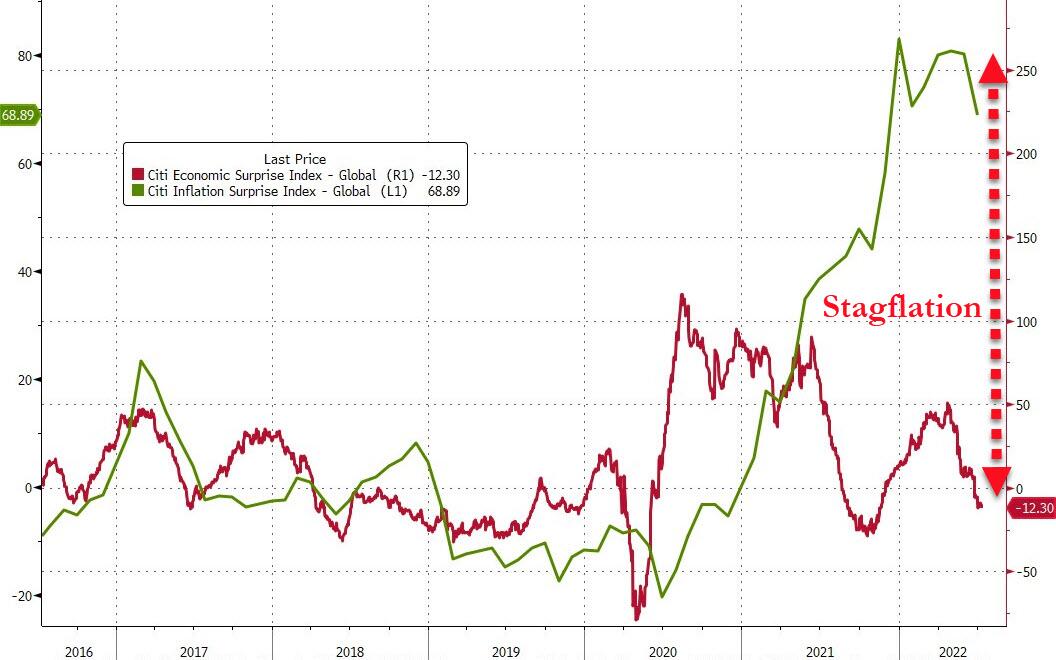
A hotter-than expected inflation report showed that the CPI rose 9.1% YoY in June, which was higher than May’s 8.6% reading, that had been the biggest increase since 1981. Economists expected an 8.8% print.
Even the Core CPI, which excludes food and energy, came in at 5.9% and topped the 5.7% estimate. On a monthly basis, the CPI was up 1.3% compared to hopes of 1.1%. Finally, some traders and investors are waking up to the fact that inflation has not yet reached its peak—far from it, in my opinion.
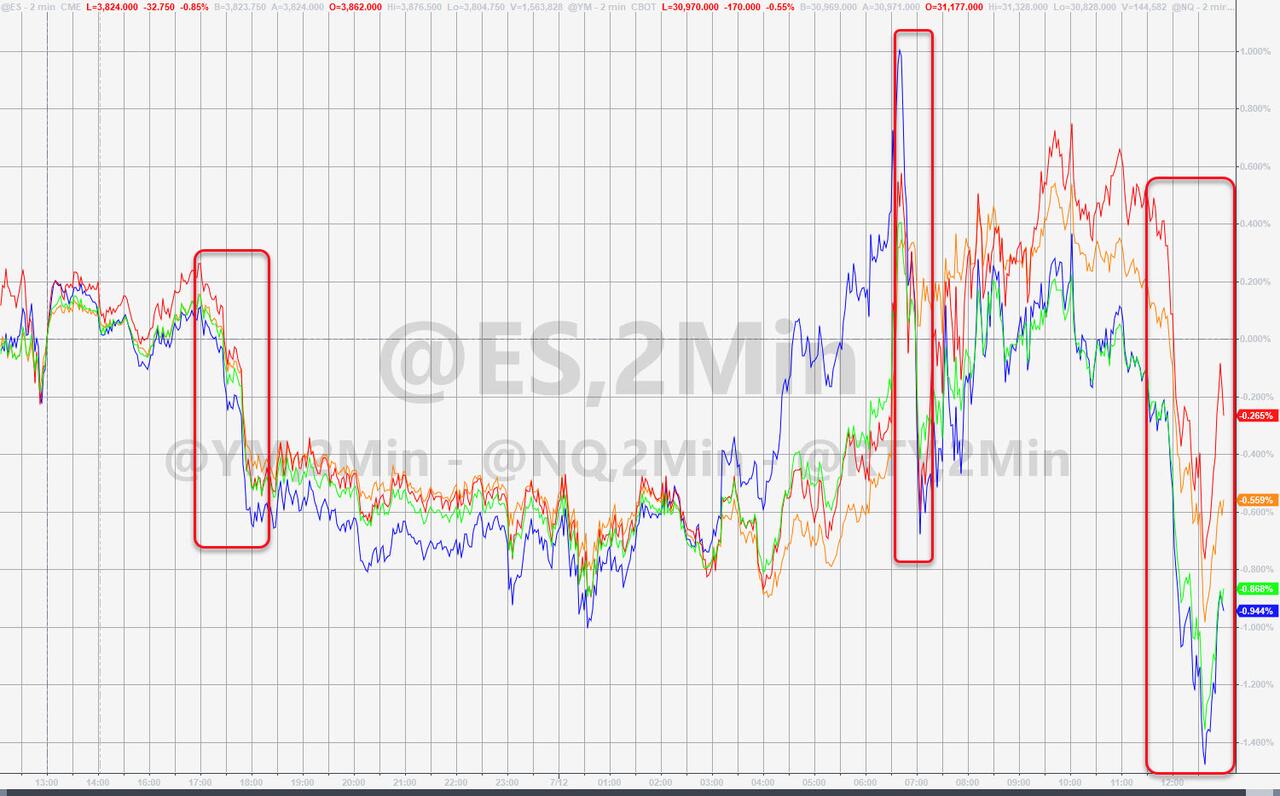
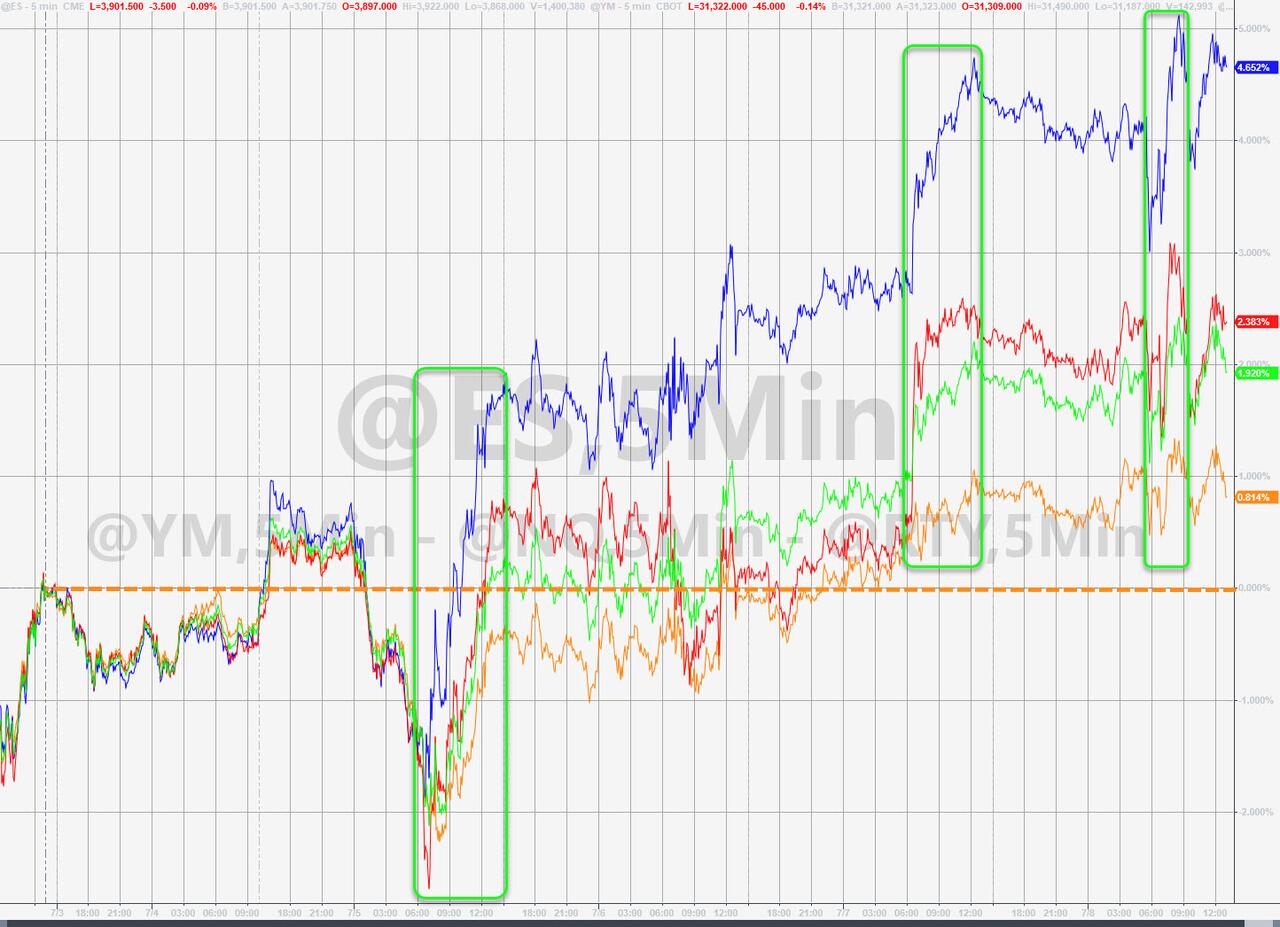
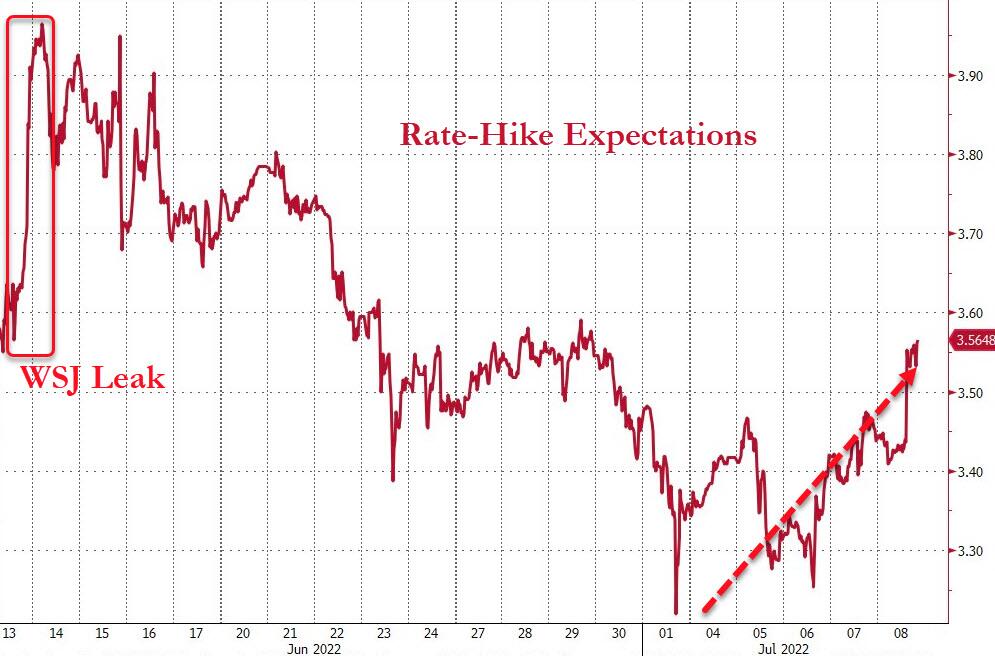
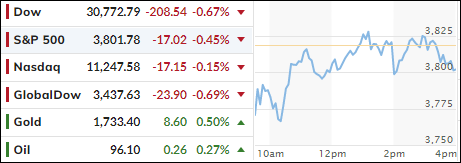
Initial market reaction was fast and furious with the Dow dropping over 400 points before staging a comeback. The reason for that sudden rebound was a report in the WSJ by Fed leaker Timiraos that a suddenly much feared 100bps rate hike in two weeks may not be realistic but a 75bps was.
That sent equities almost into a vertical ascent with the S&P 500 and the Nasdaq briefly seeing green numbers. However, Atlanta Fed President Bostic pulled the rug out from under this rally with quotes like this:
“Everything is in play.”
Asked if that included by raising rates by a full percentage point, he replied:
“it would mean everything.”
That destroyed any hope or confidence the WSJ article had created, so the major indexes headed back south but closed off their worst levels for the session.
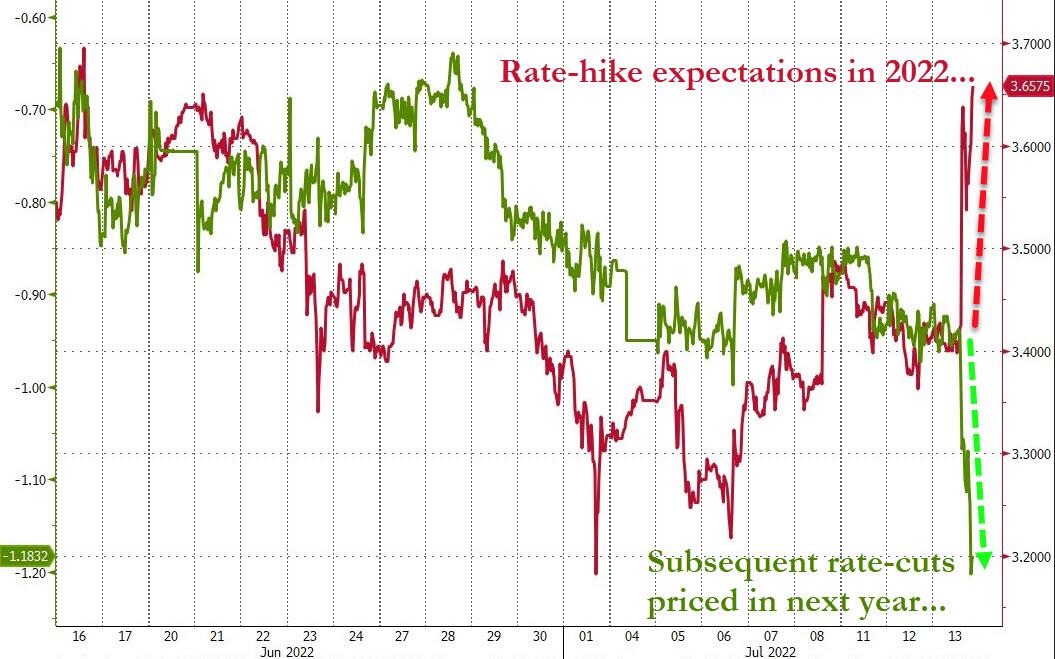
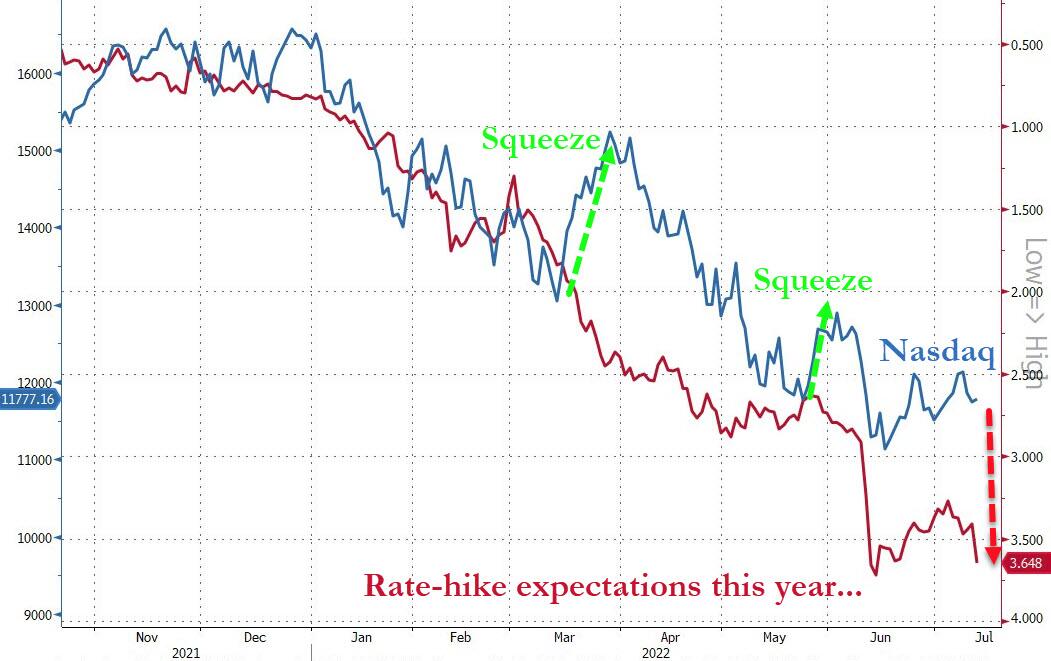
It means rate hike expectations are rising this year, with subsequent rate cuts virtually guaranteed in 2023, as the Fed will bail us out of a deep recession, as ZeroHedge put it.
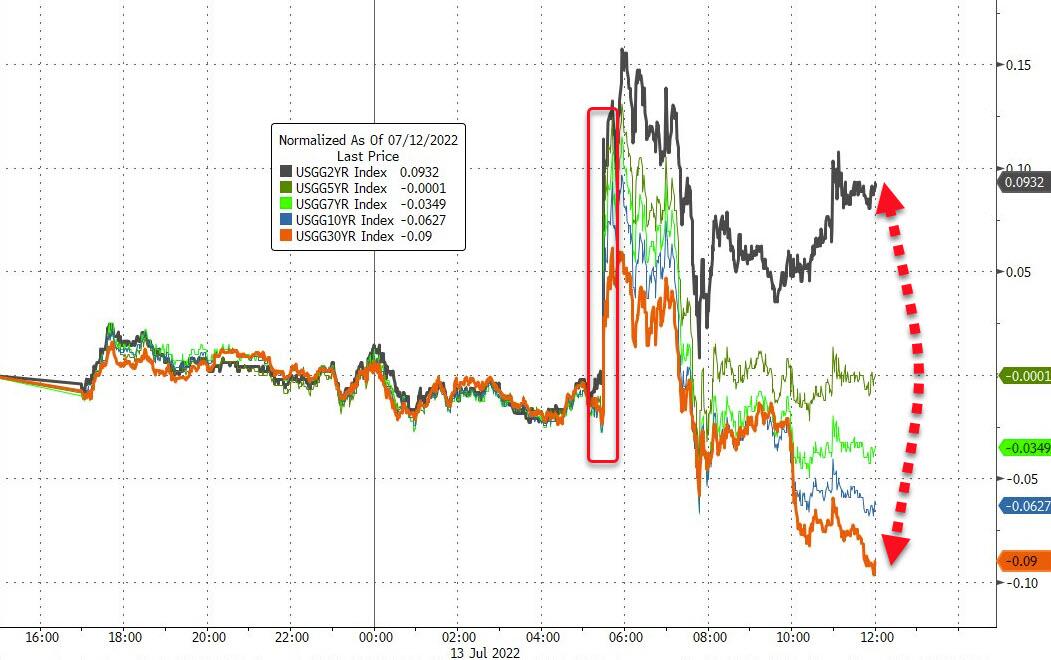
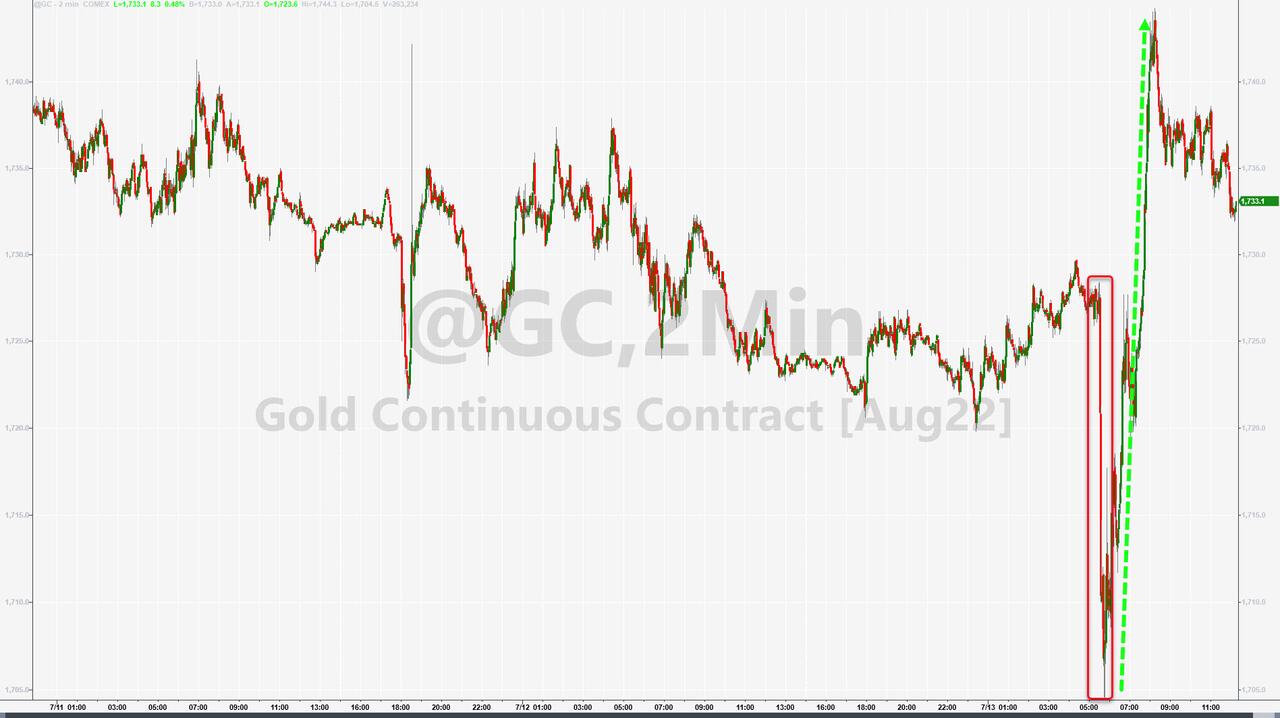
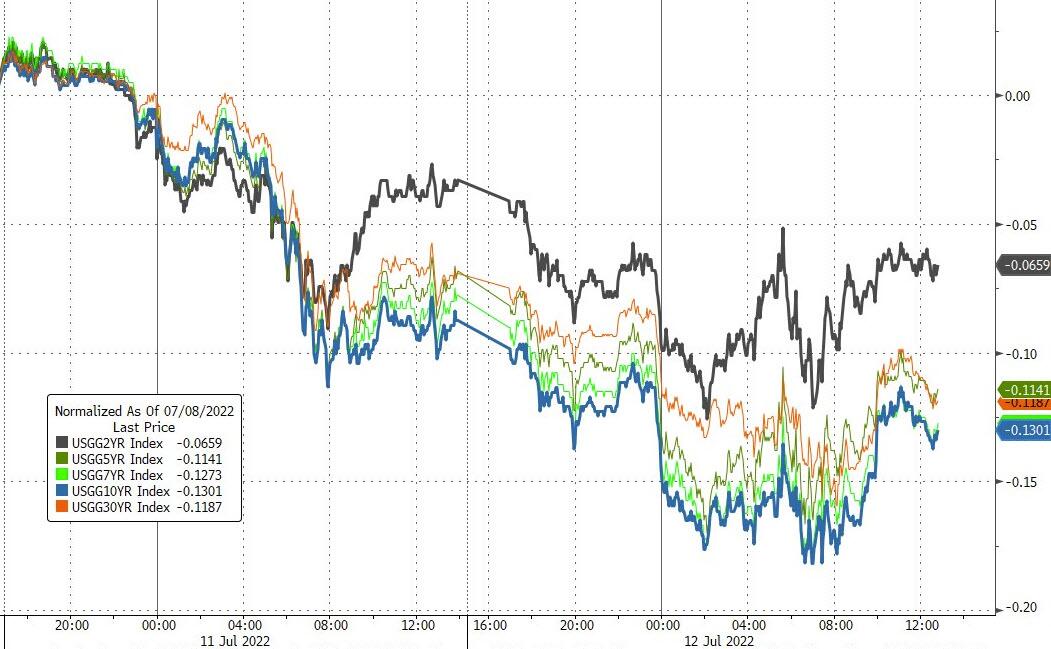
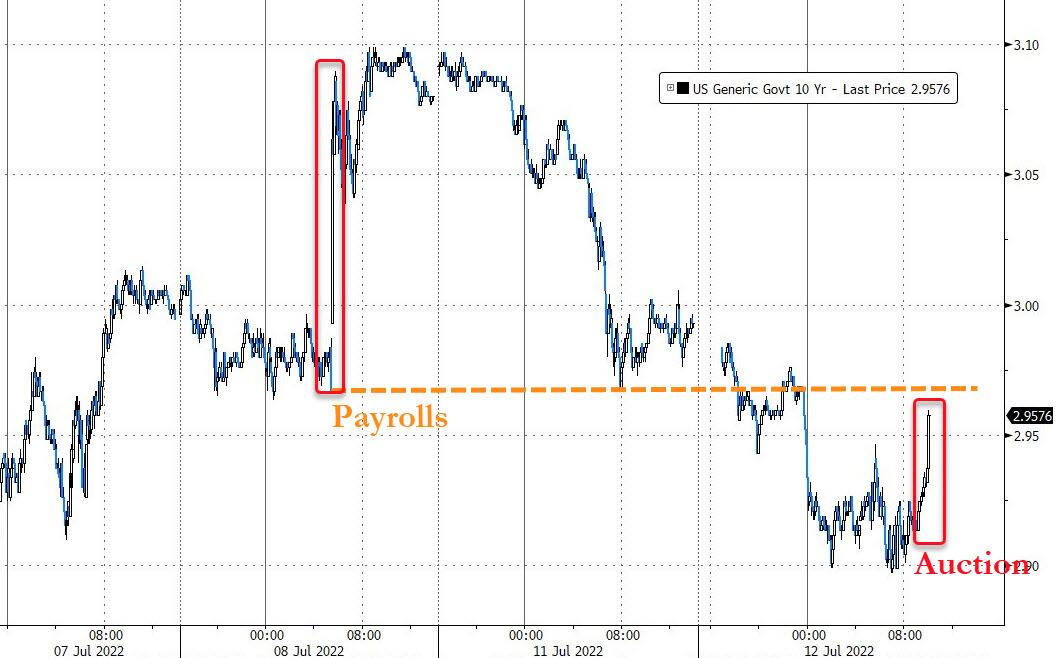
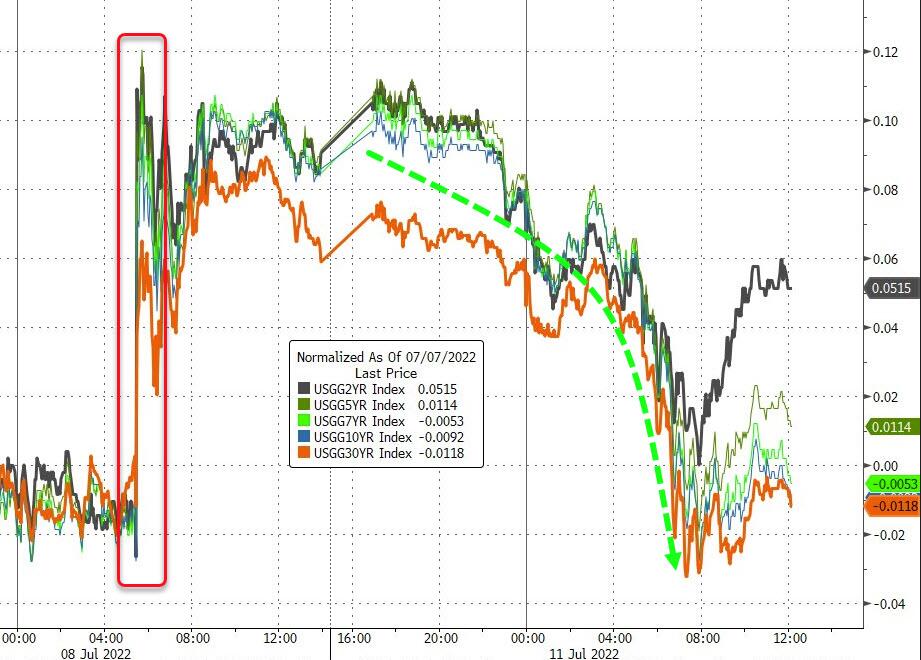
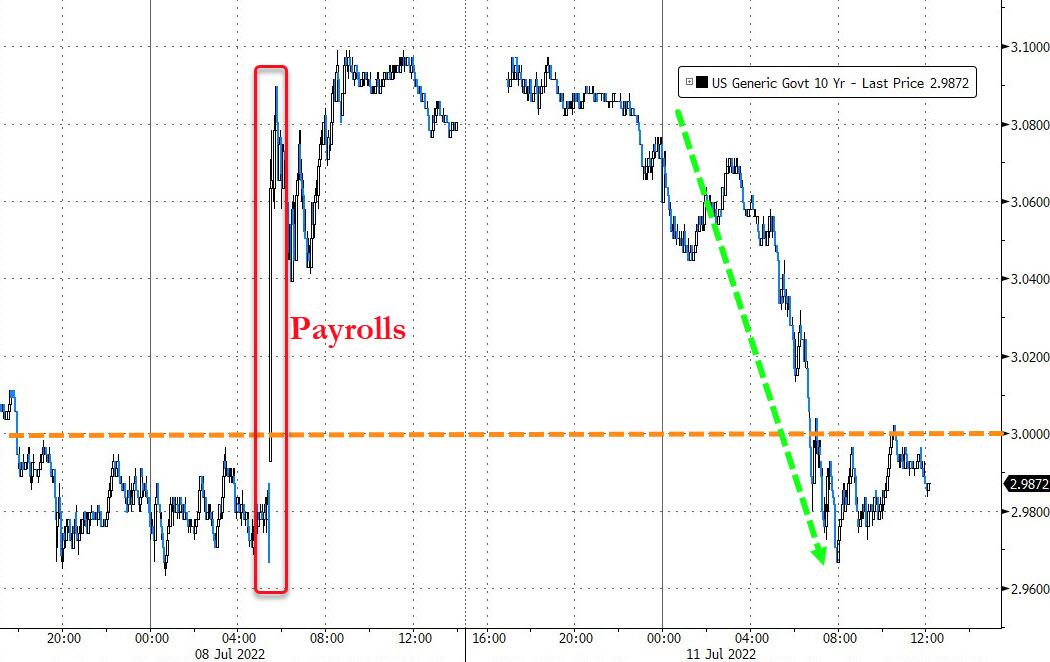
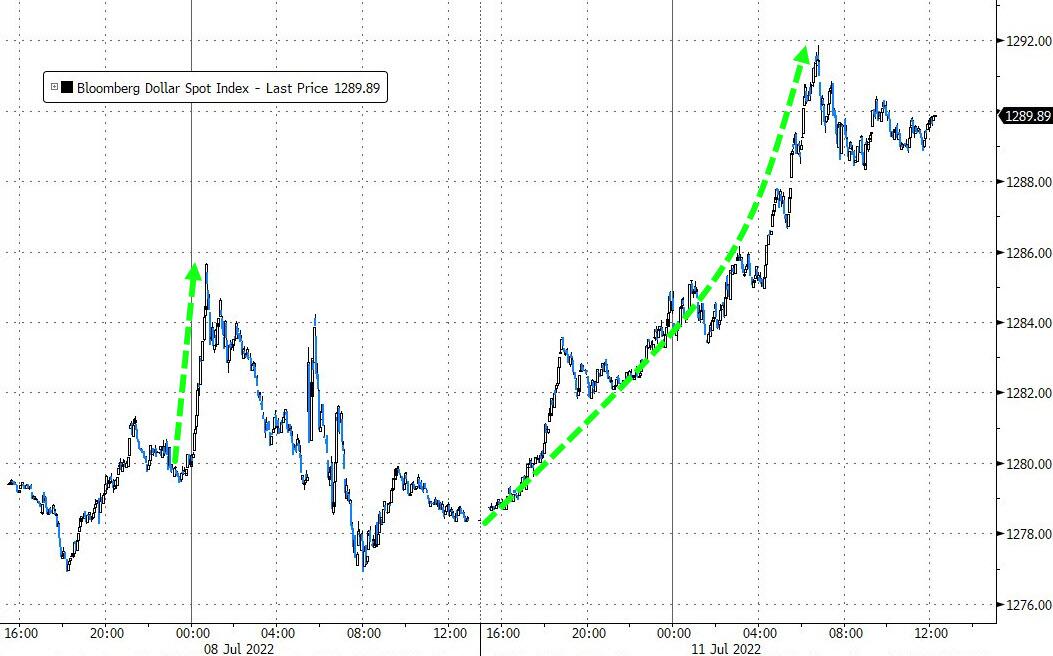
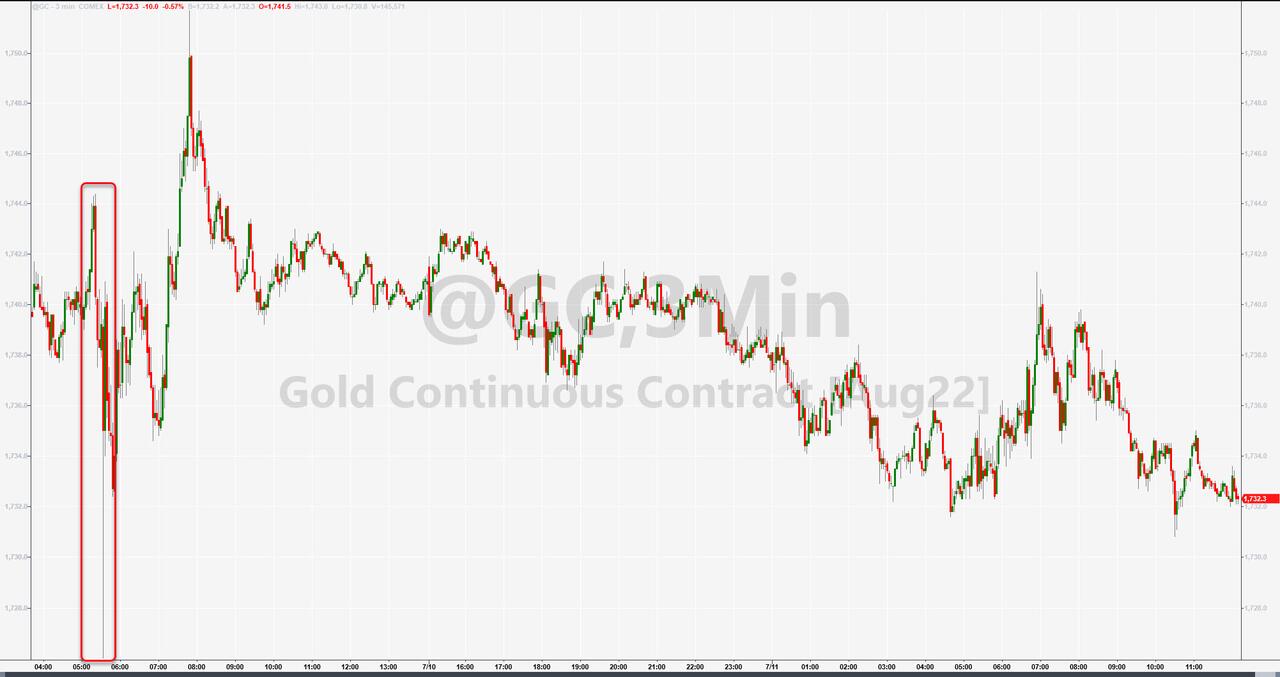
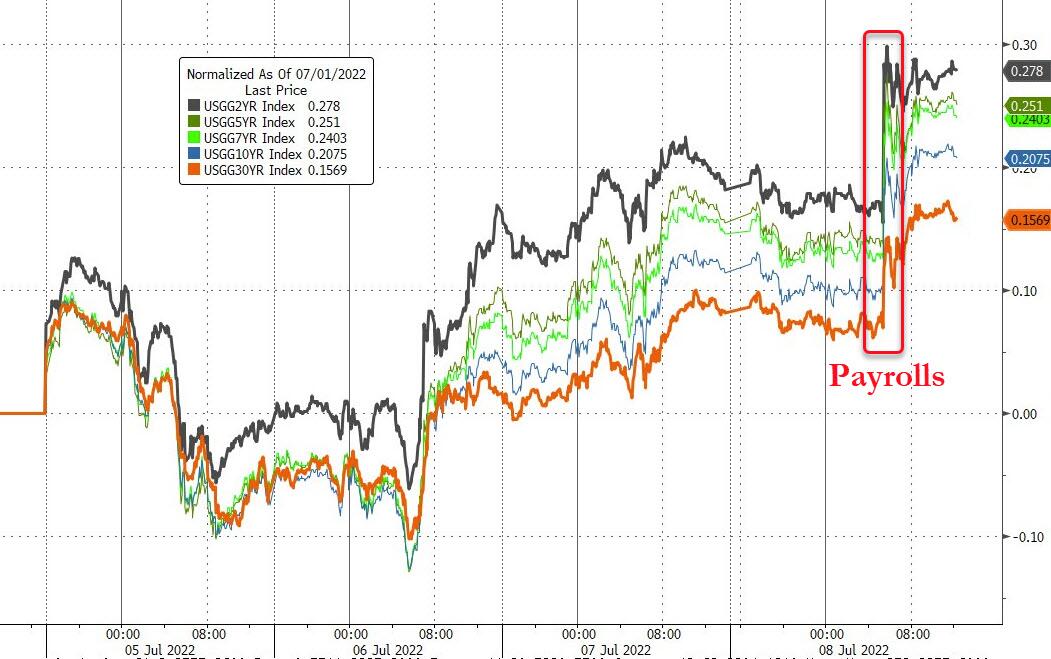
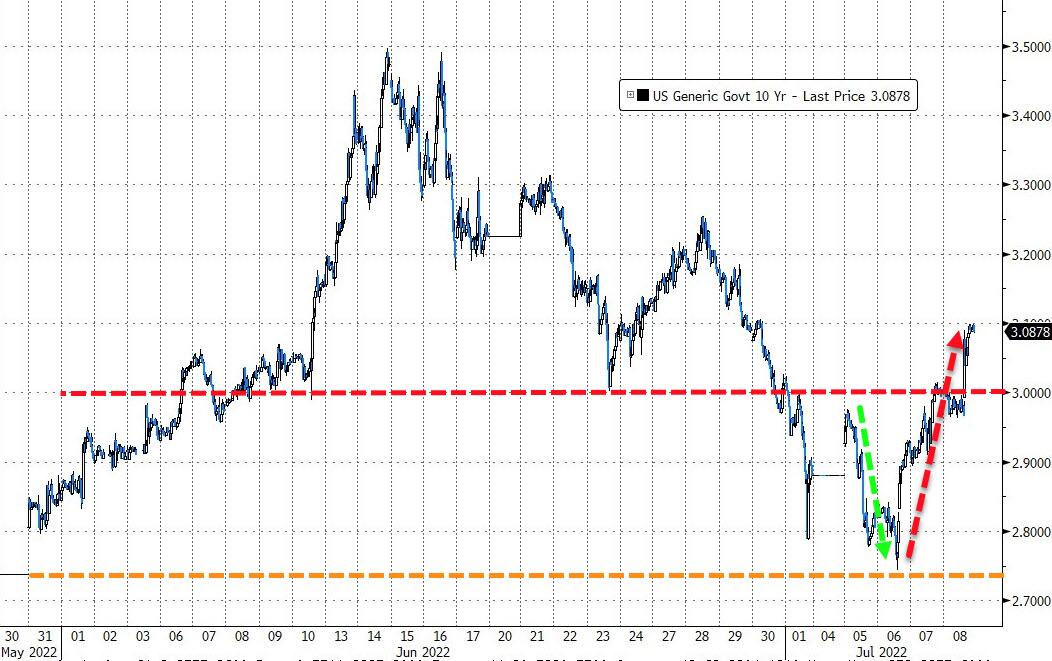
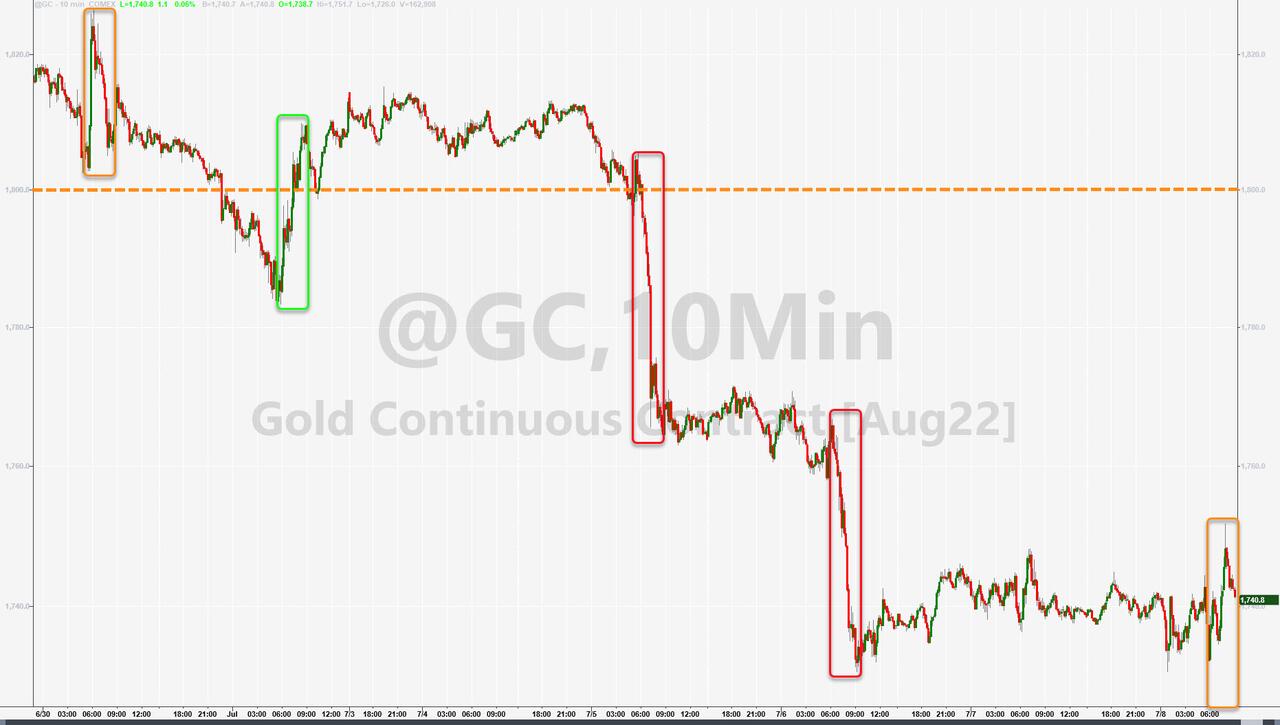
Bond yields spiked following the release of the CPI report, then dropped with only the 2-year yield closing higher. Gold rode its own roller coaster. The precious metal first puked then spiked and closed with modest gains.
ZH summed up the current environment like this:
- Stocks are still bipolar, and squeeze driven, as well as hoping beyond hope that the subsequent easing, after The Fed pushes the economy into recession, will save the day…
Hmm…
Read More