[Chart courtesy of MarketWatch.com]
- Moving the markets
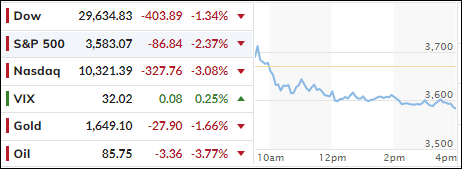
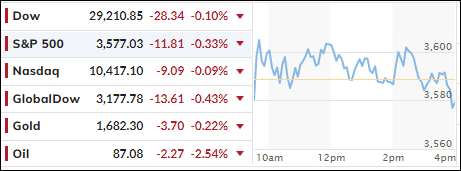
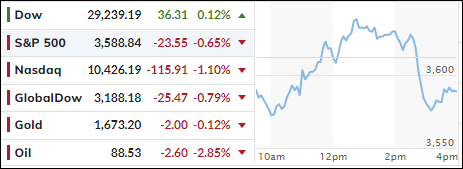
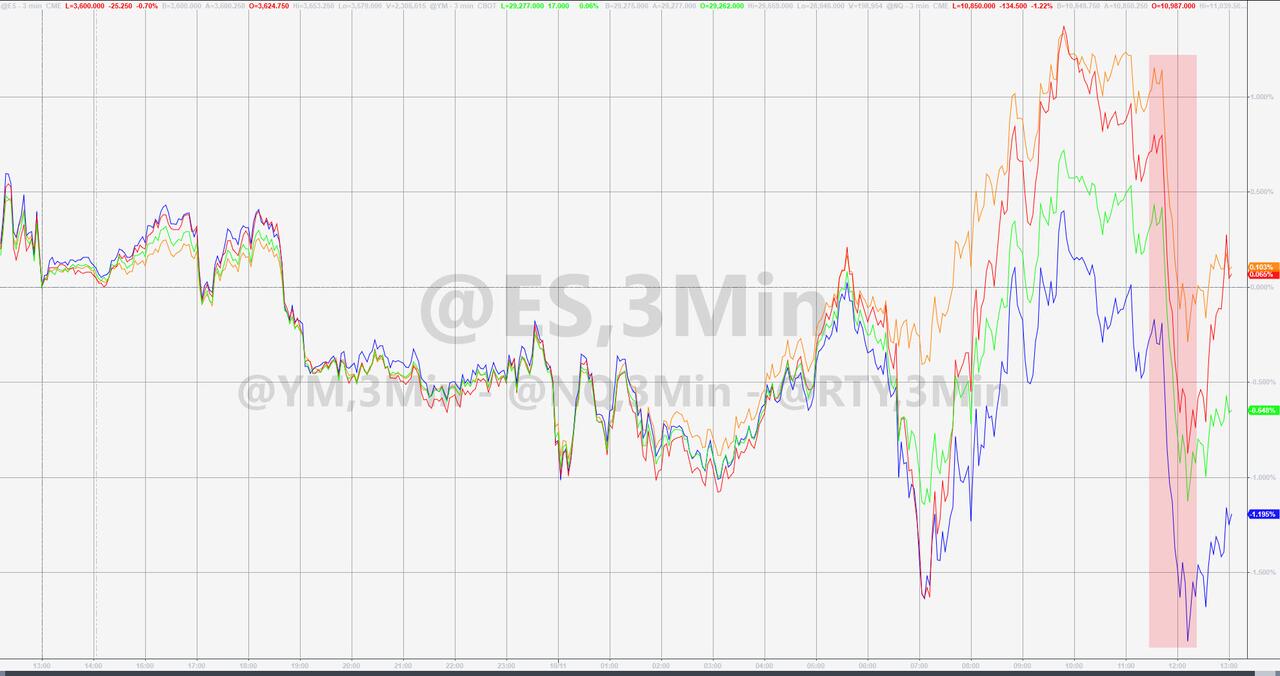
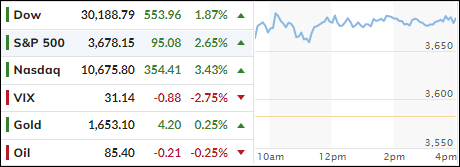
A relief rally held its ground with the major indexes remaining steady above their respective unchanged lines, as strong bank earnings by Bank of America and Bank of Mellon provided the fuel to sustain the rebound.
Of course, stocks have been in deeply oversold territory, and are hovering near year lows of the year, with the S&P 500 having declined in four of the past five weeks. We have witnessed big moves in both directions, as apprehension has spread through Wall Street causing this roller-coaster type of swings.
Today, the pendulum swung back in favor of the bulls, which also found some encouragement by the markets now moving into the seasonally strong part of the year.
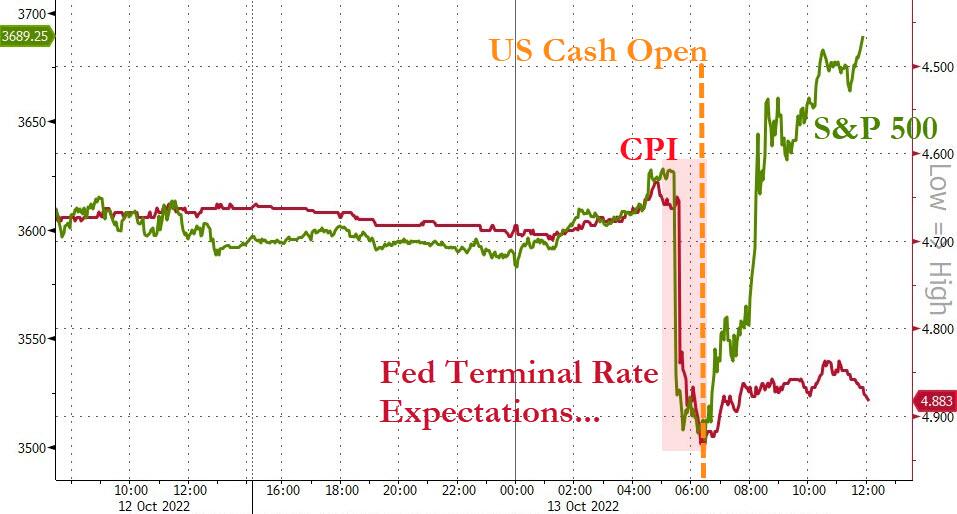
Whether that is enough to propel the rally further remains to be seen and will be impacted by the upcoming earnings season, as well as companies’ outlooks and/or revisions, along with the Fed’s policies in the face of persistently high inflation and an economic slowdown.
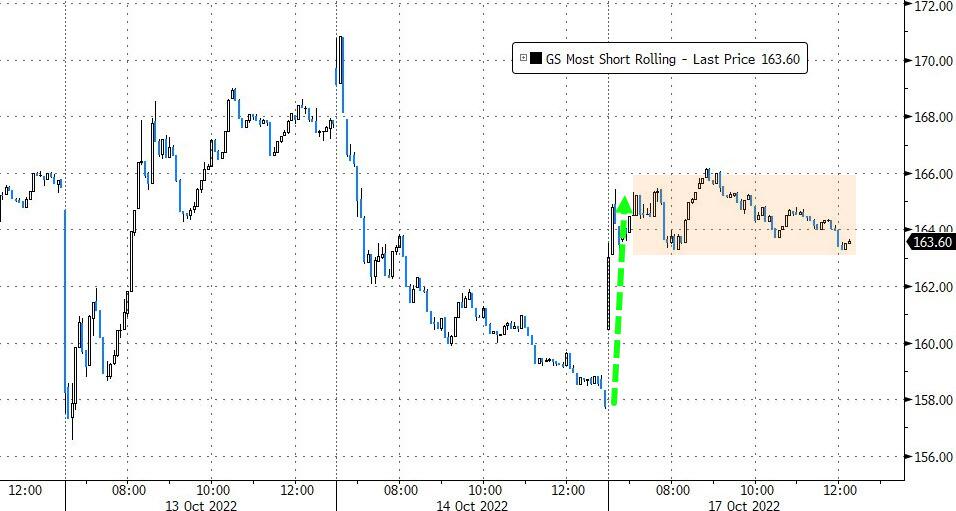
As ZeroHedge pointed out, “Friday’s bloodbath was dominated by hedge fund shorting, which set up the market for a major squeeze higher…yet again.” And that is exactly what happened, as the most shorted stocks got squeezed early on, but that was it—no follow through, which could indicate that all of the ammo has been used up.
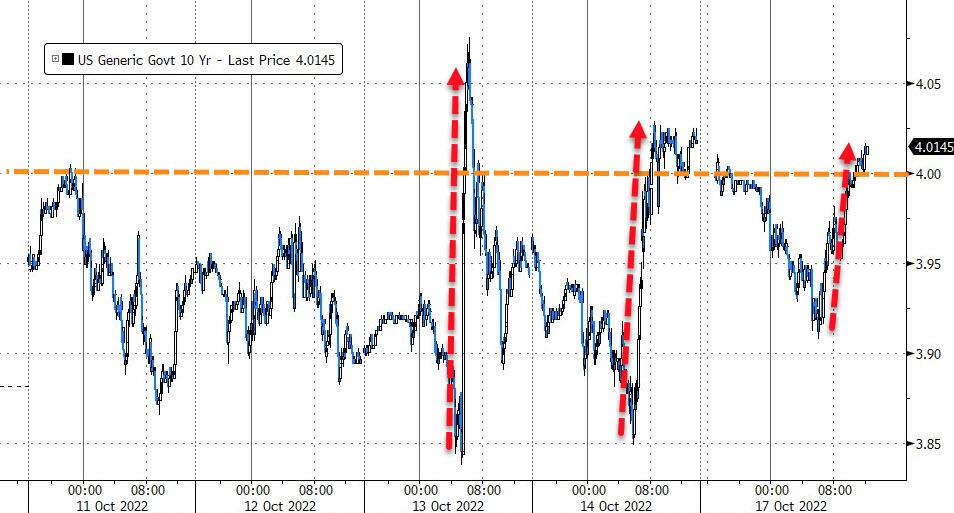
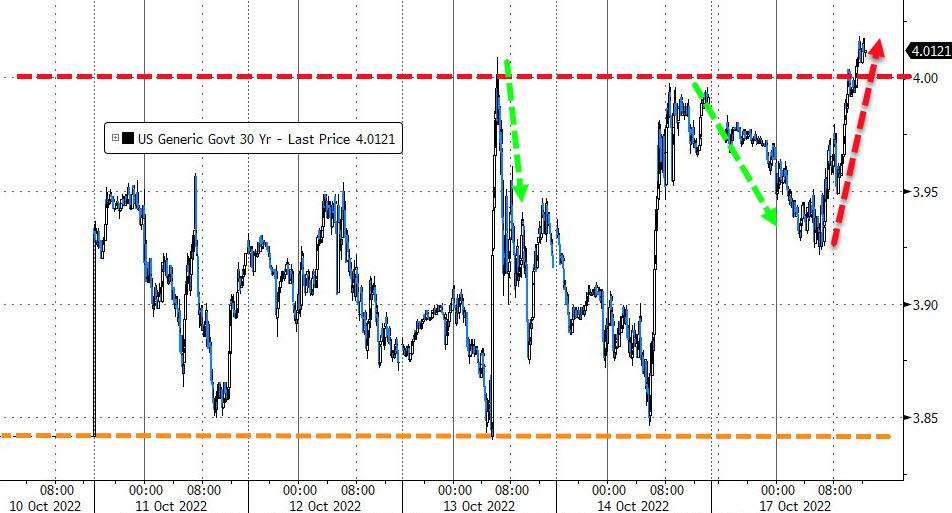
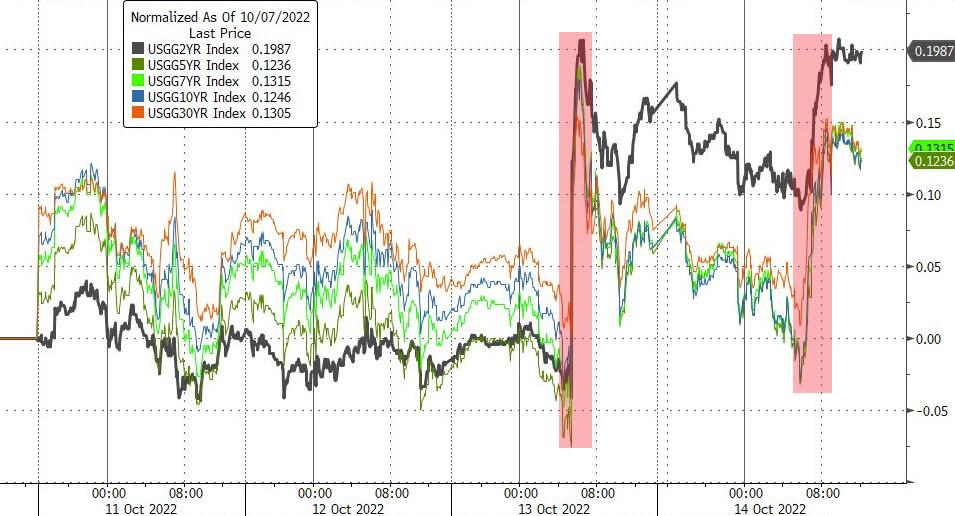
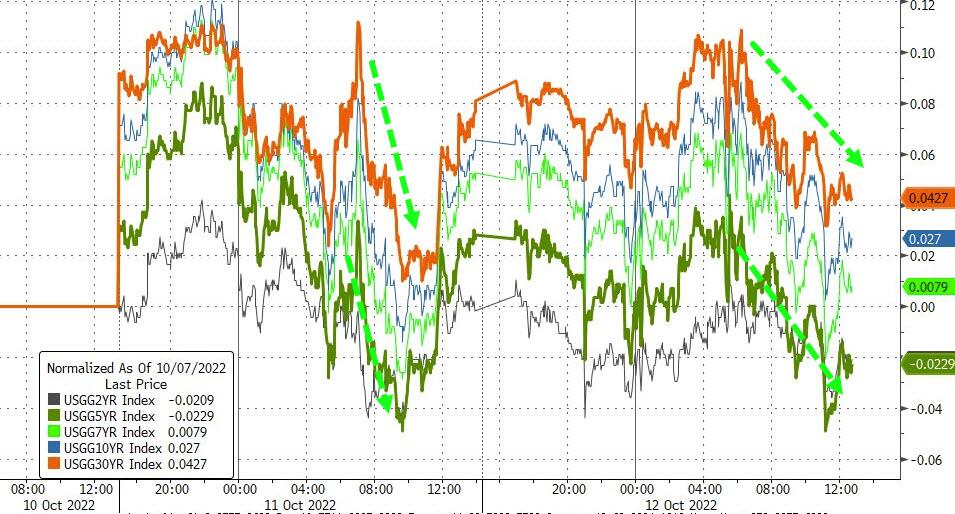
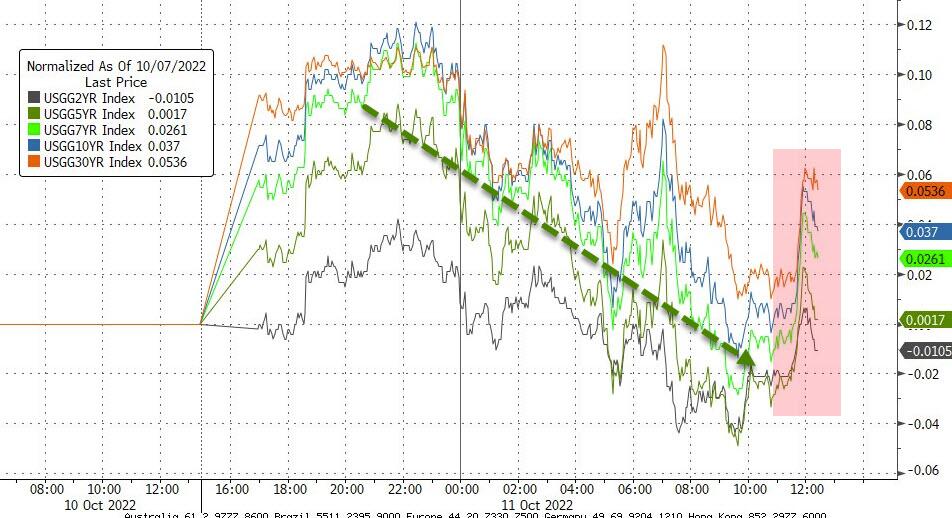
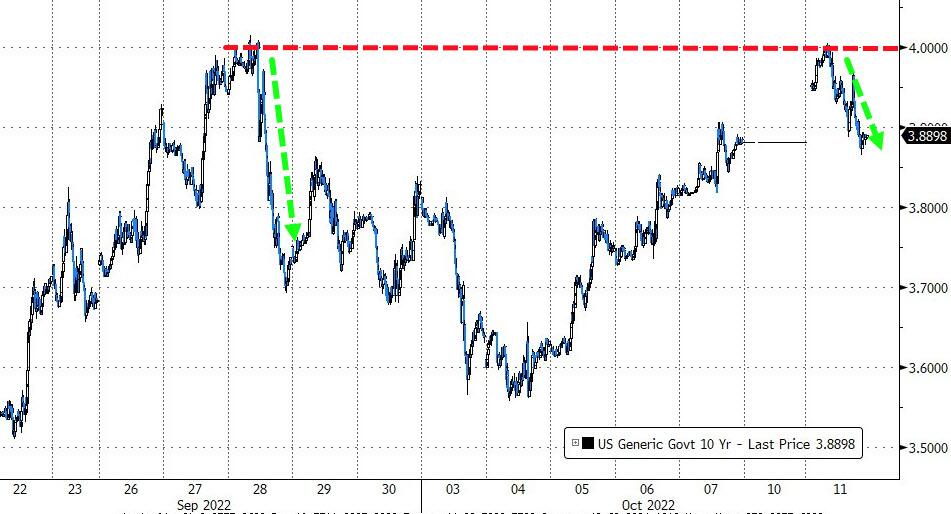
Bond yields presented a mixed picture with the 10-year rallying back above 4% and closing at 4.02%, while the 30-year followed suit. Yields have now risen for 11 straight weeks, the longest such streak since 1978, as ZeroHedge added.
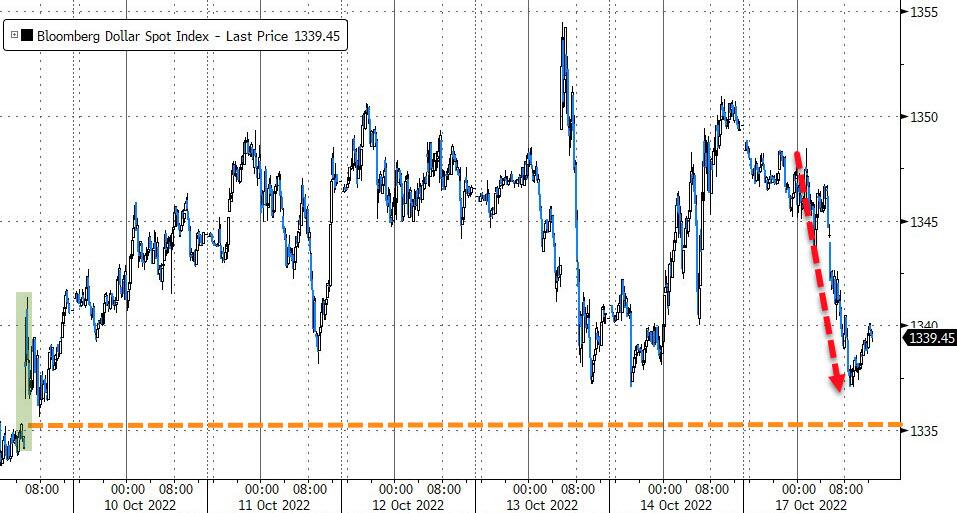
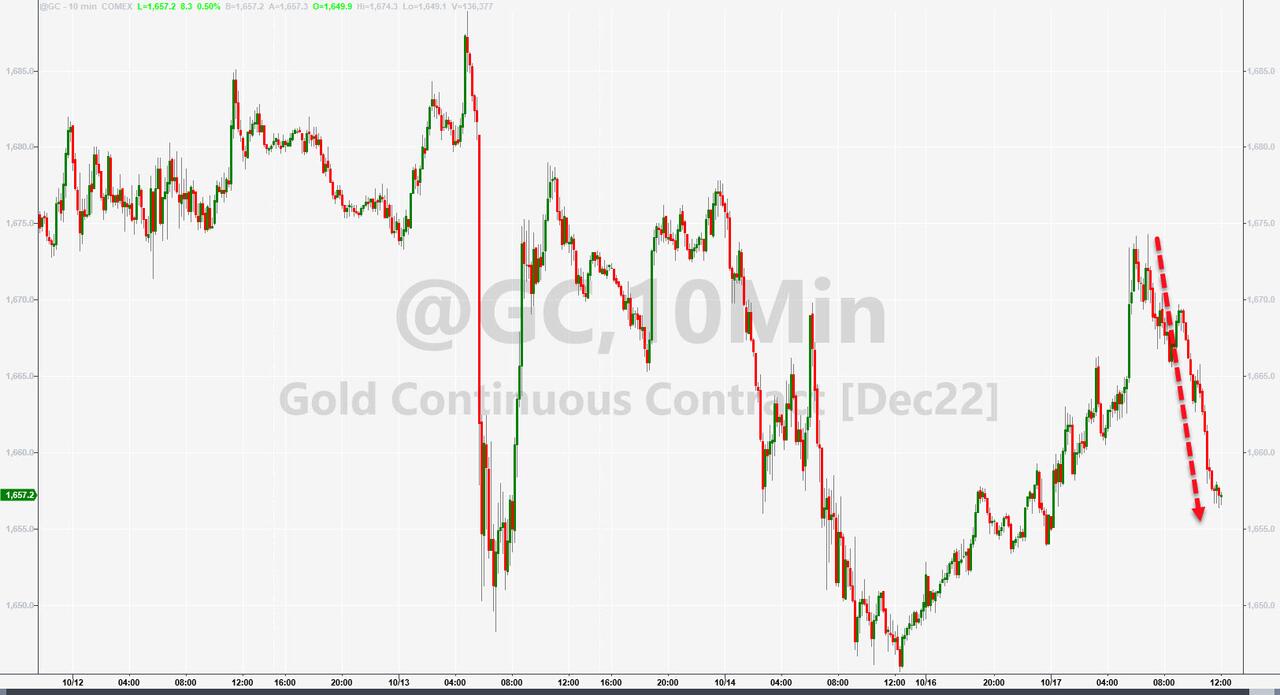
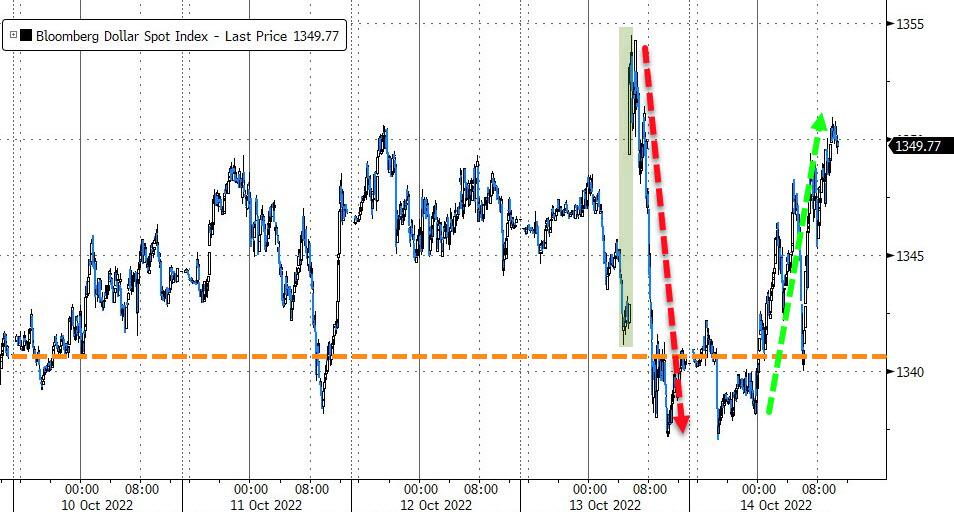
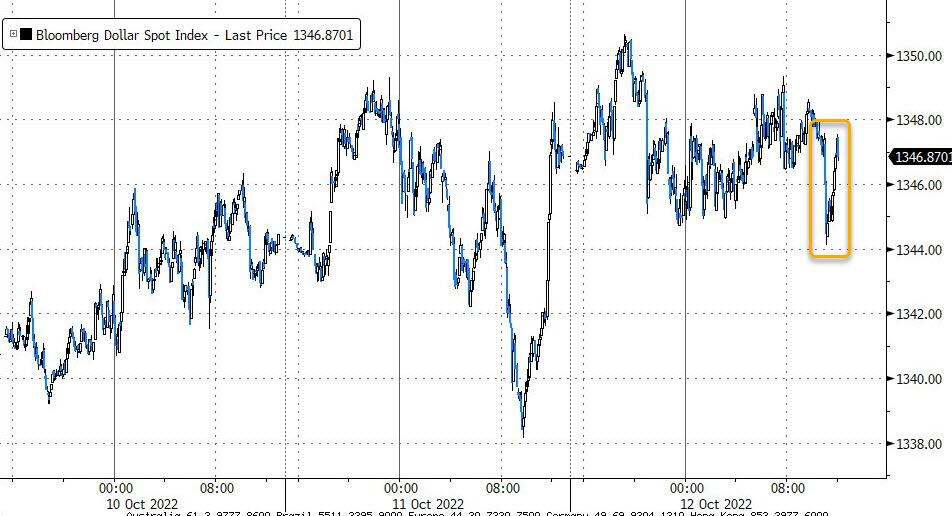
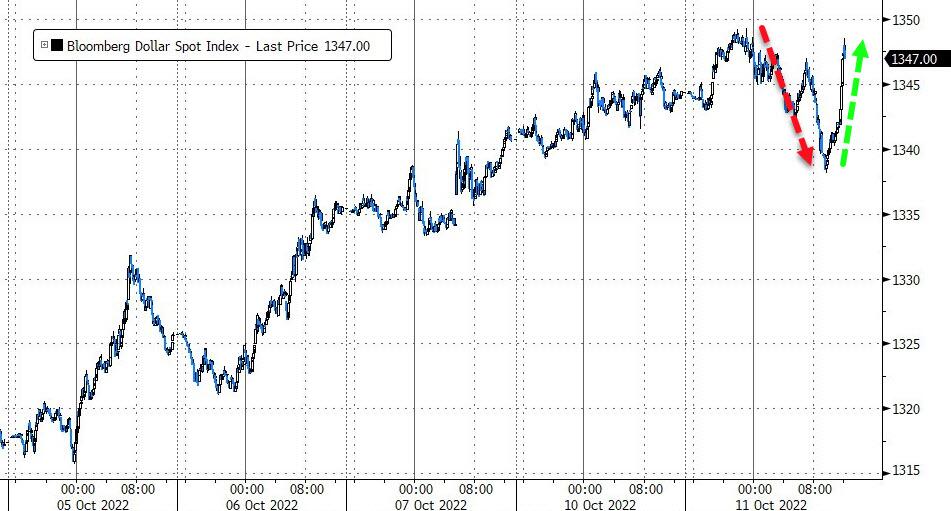
The US Dollar was in diving mode today, which helped Gold to rally, but the precious metal could not sustain the early gains but closed in the green.
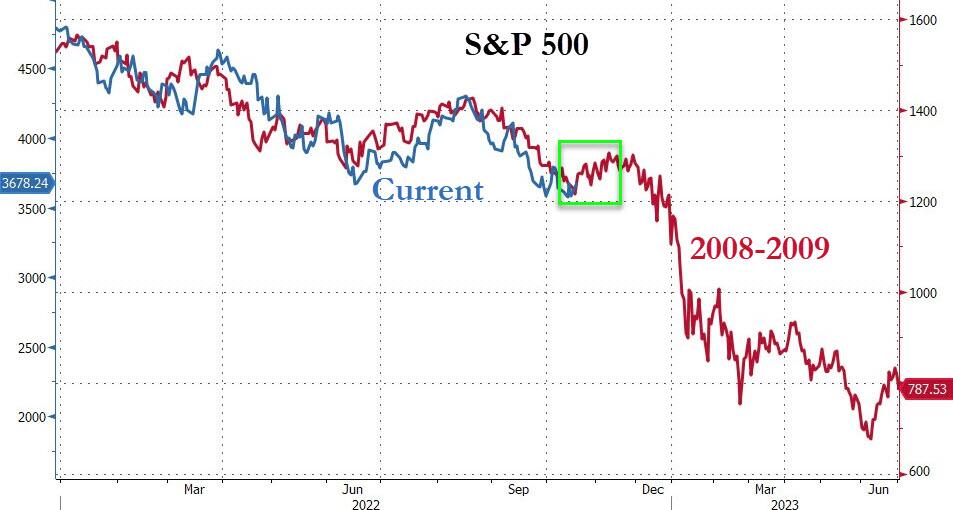
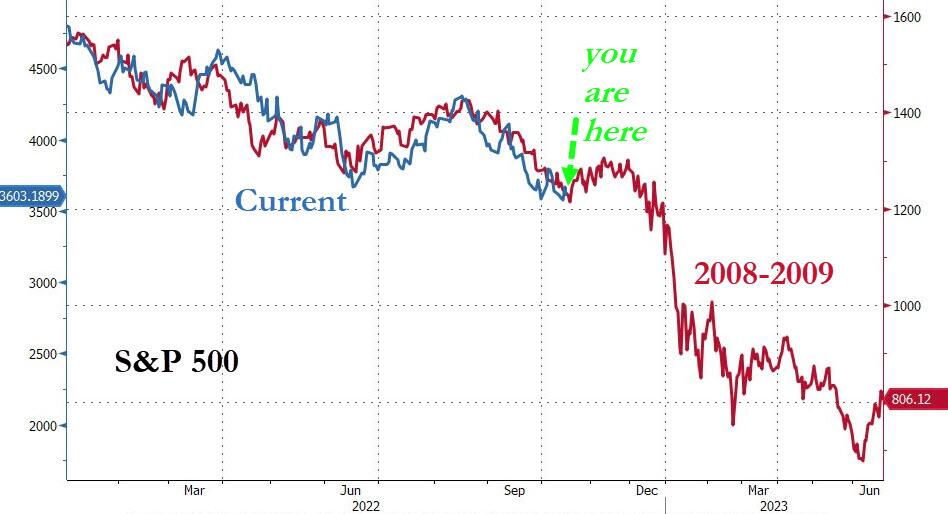
Can this bounce be prolonged? ZeroHedge concluded that it can—at least until the November FOMC meeting—that is if the 2008-2009 analog holds true.
Read More