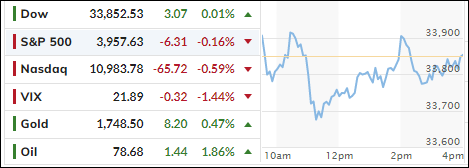
[Chart courtesy of MarketWatch.com]
- Moving the markets
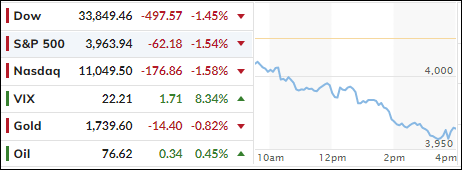
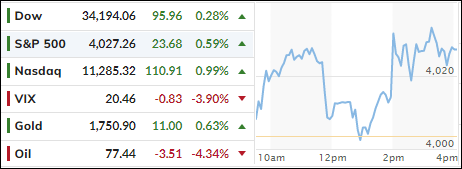
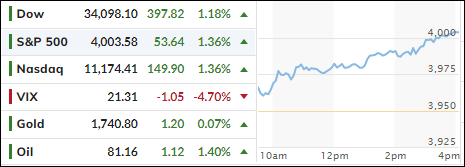
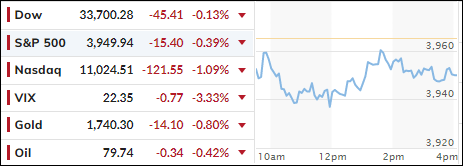
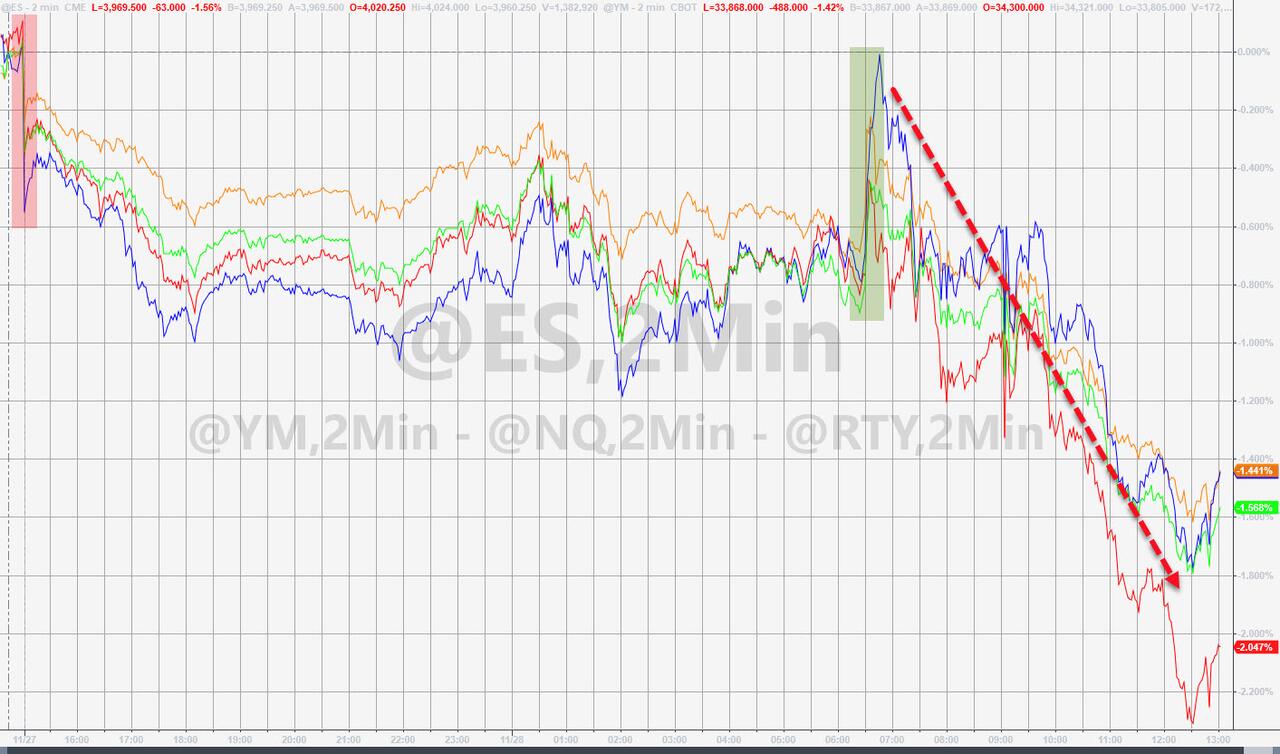
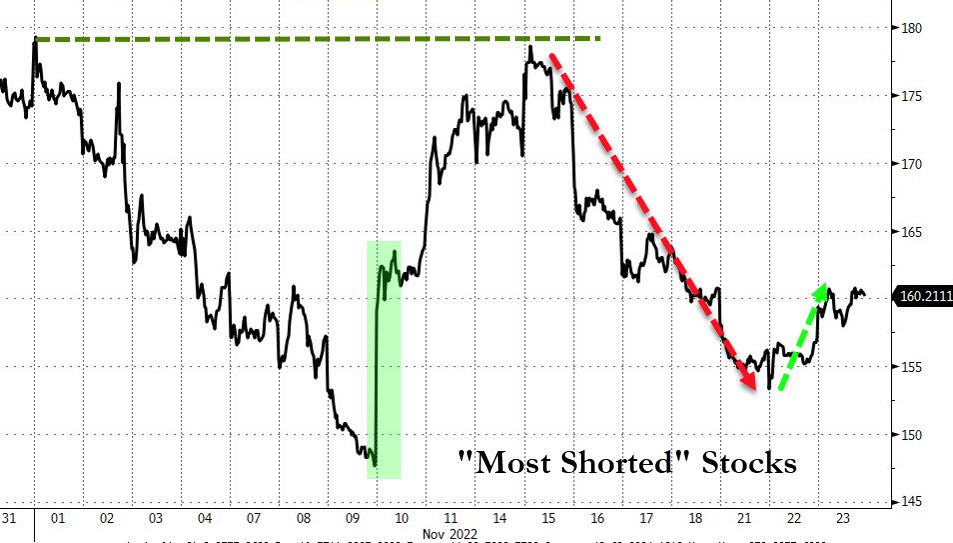
While the major indexes wandered aimlessly throughout the session, they at least managed to dig themselves out of an early hole, crawled back and reduced their losses. In the end, not much was gained or lost.
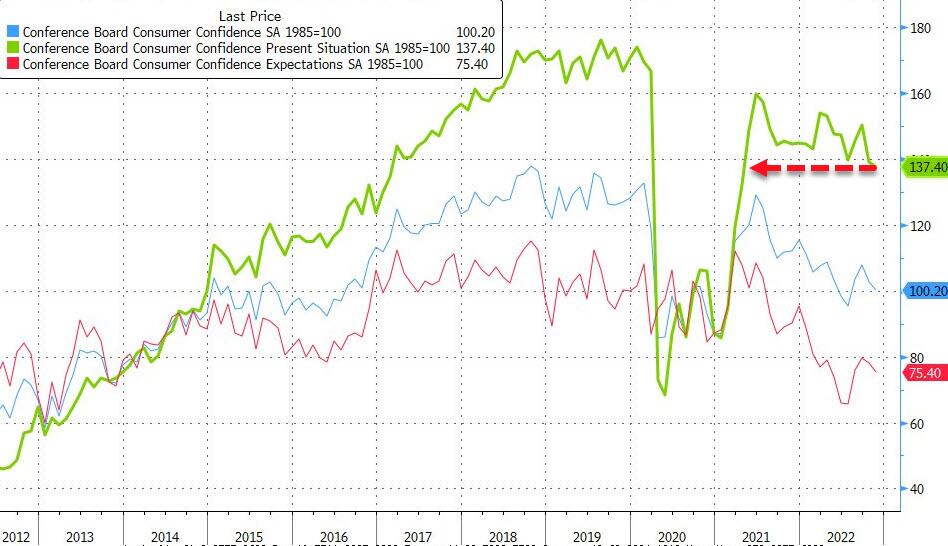
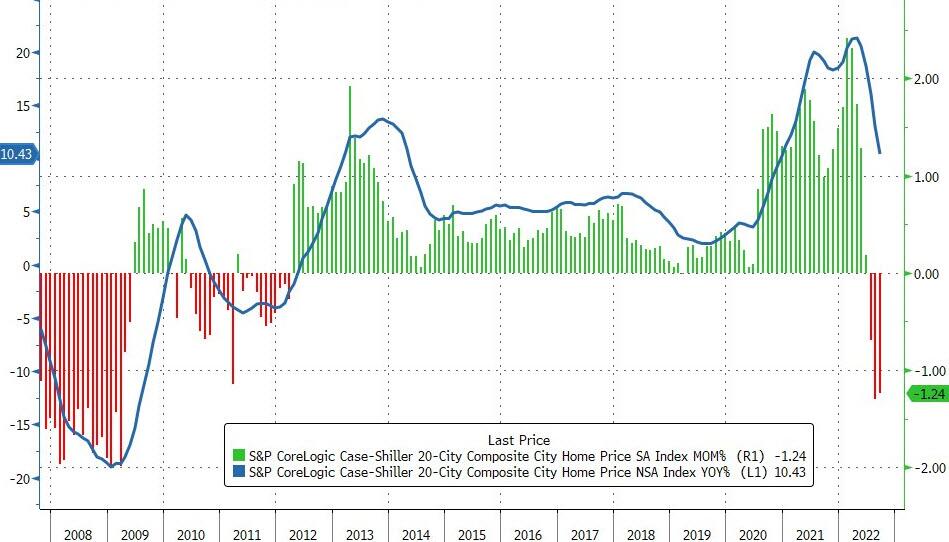
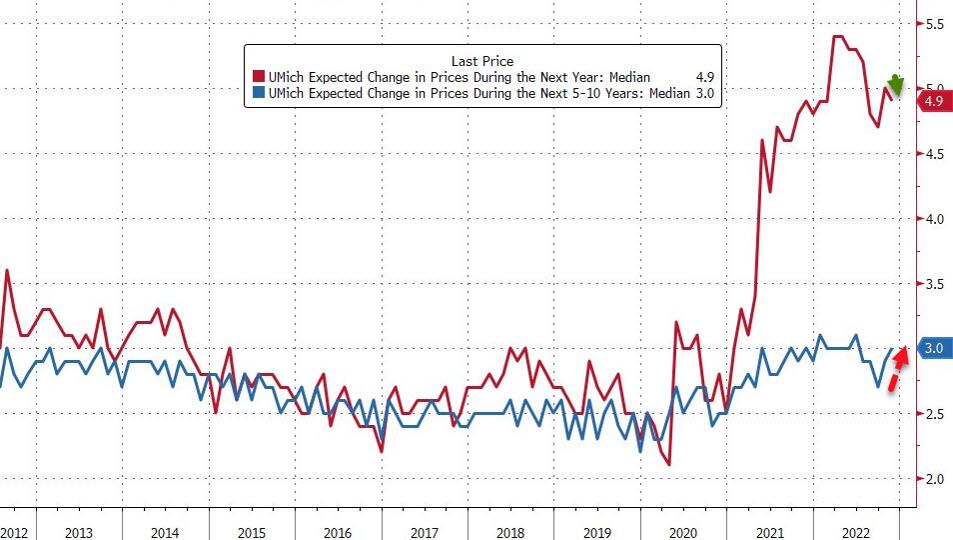
Economic data points did nothing to encourage bullish sentiment with Consumer Confidence dropping in October, while Inflation Expectations jumped. US Home prices declined for the 3rd straight month in September, as ZeroHedge reported, clearly a consequence of soaring mortgage rates.
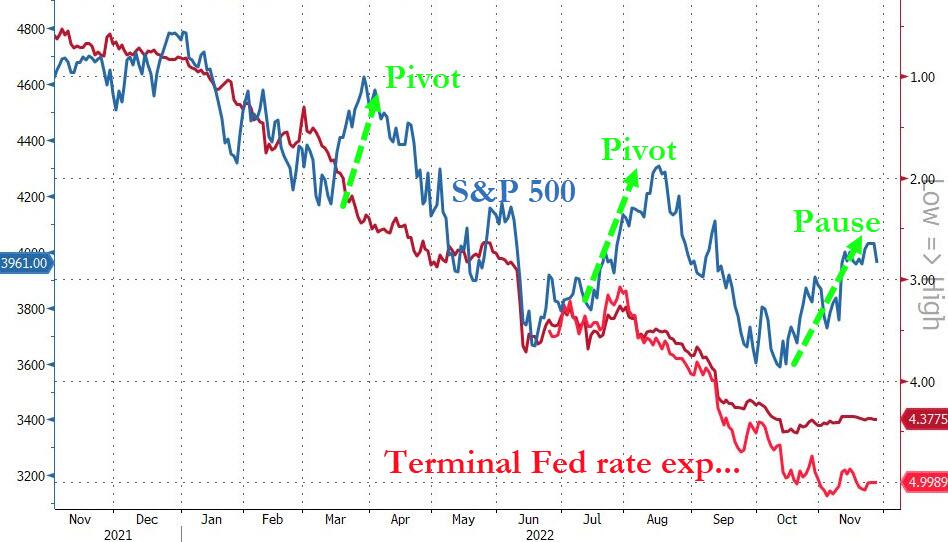
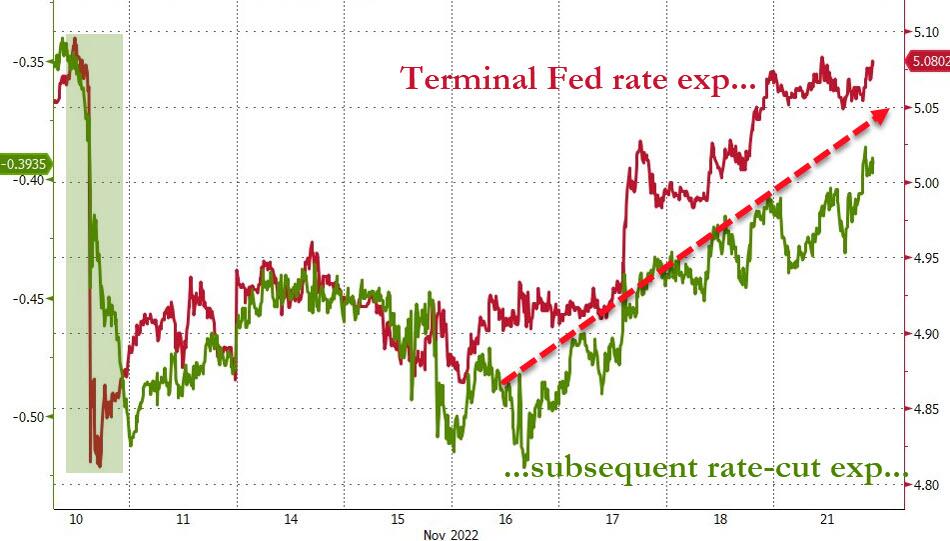
All eyes are now on Fed head Powell’s speech tomorrow when observers will be hunting for clues whether the central bank might pause or even stop interest rate hikes. It appears that this kind of hopeful thinking, despite Powell & Co having clearly and repeatedly announced that they are nowhere near the Fed’s expected termination rate—now at 5-7%.
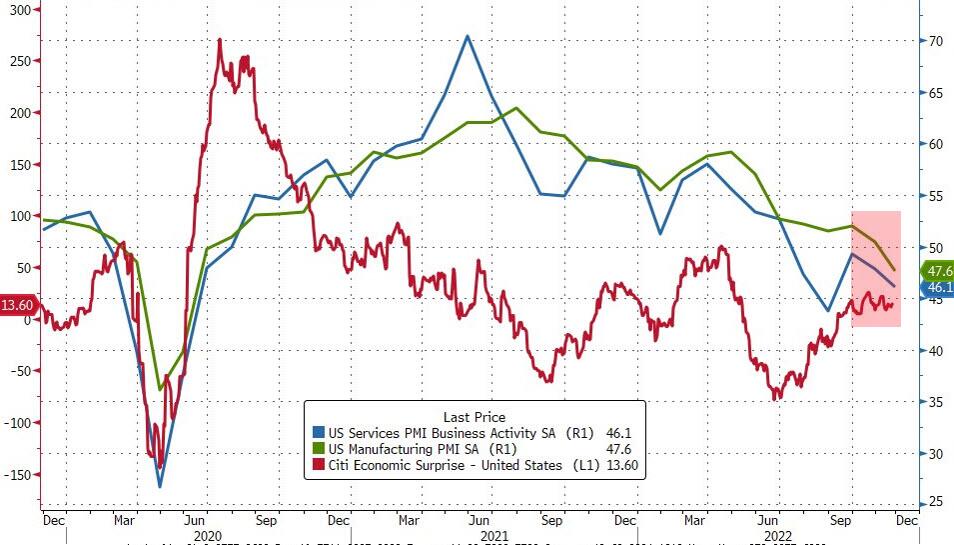
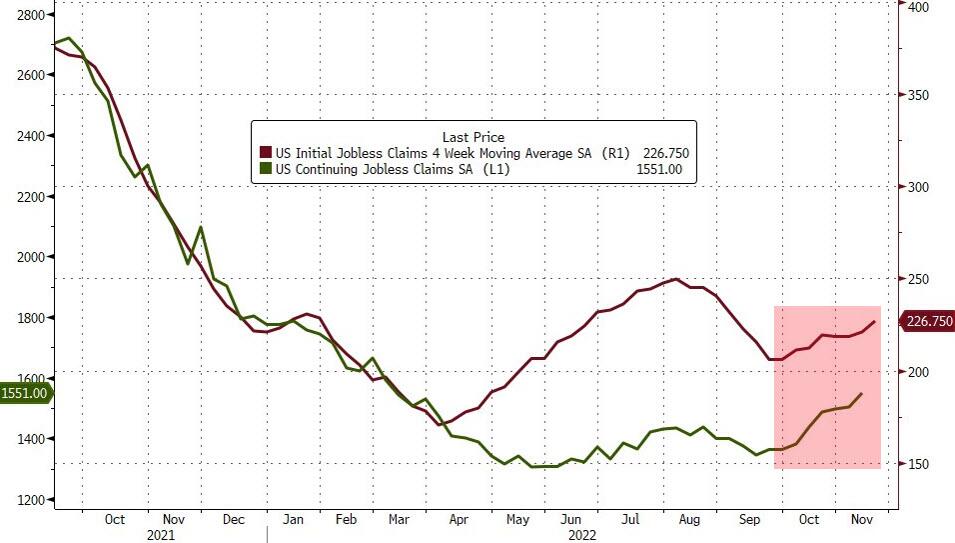
CNBC called the next 10 to 14 days a “data-rich period”, which may help clarify if inflation and economic growth can be balanced and, I suppose, co-exist. This Friday’s labor report and next week’s PPI number will add important context to see if this bear market bounce can be extended or not.
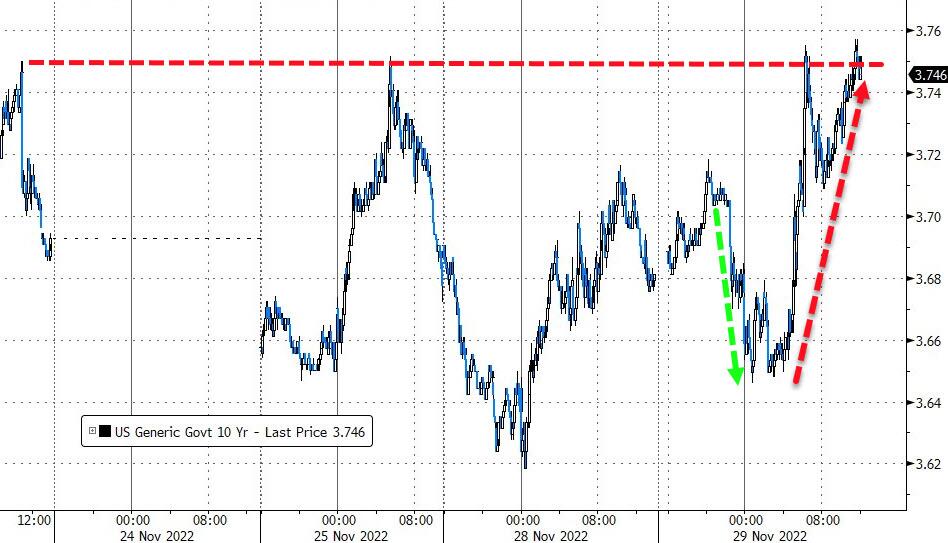
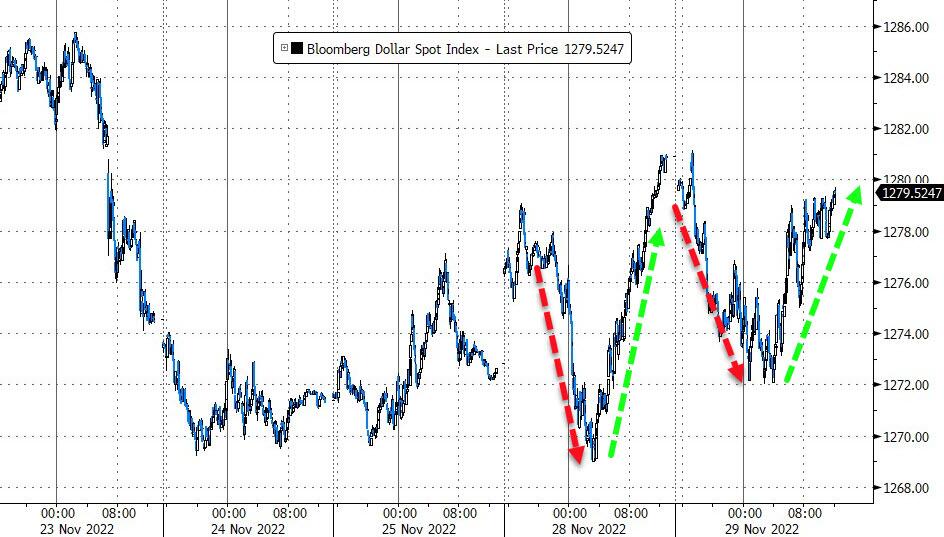
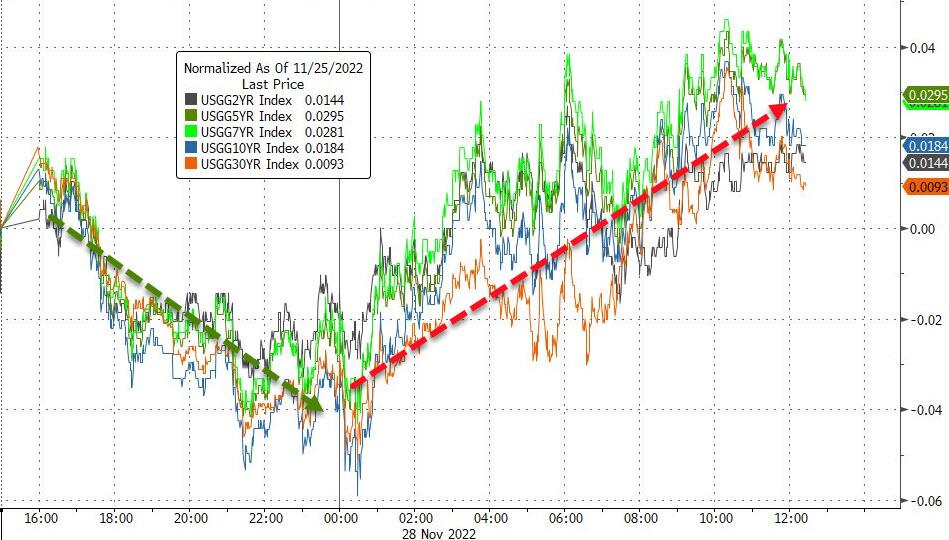
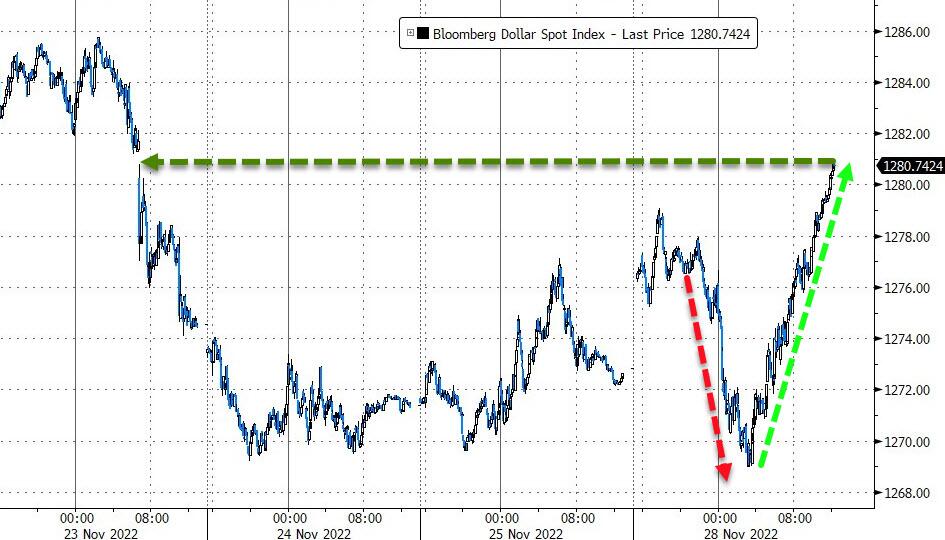
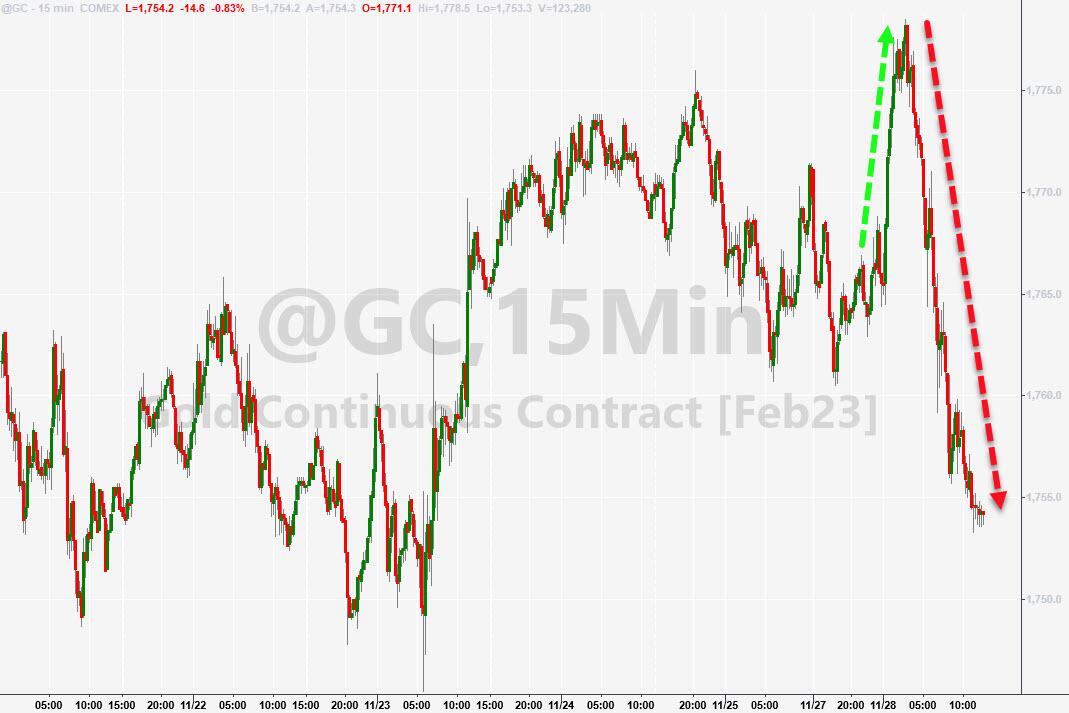
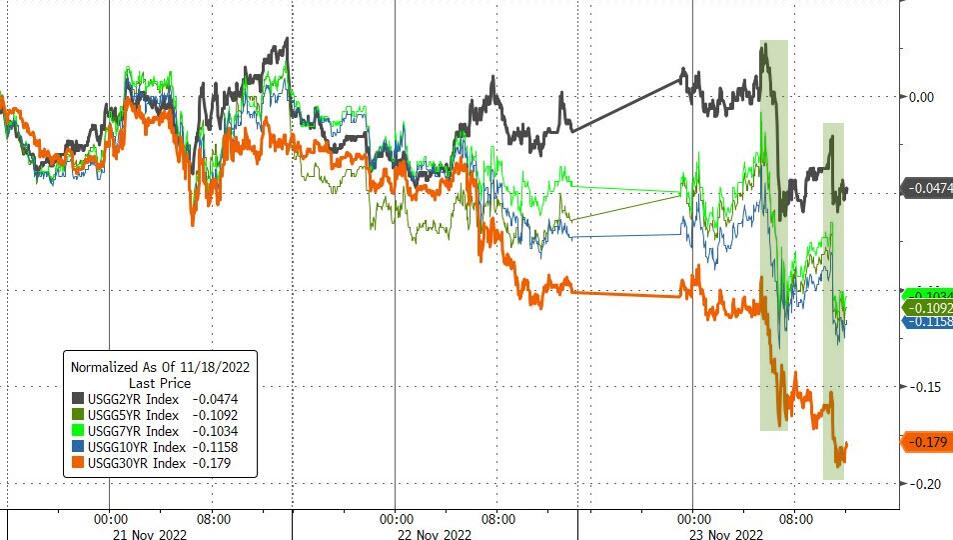
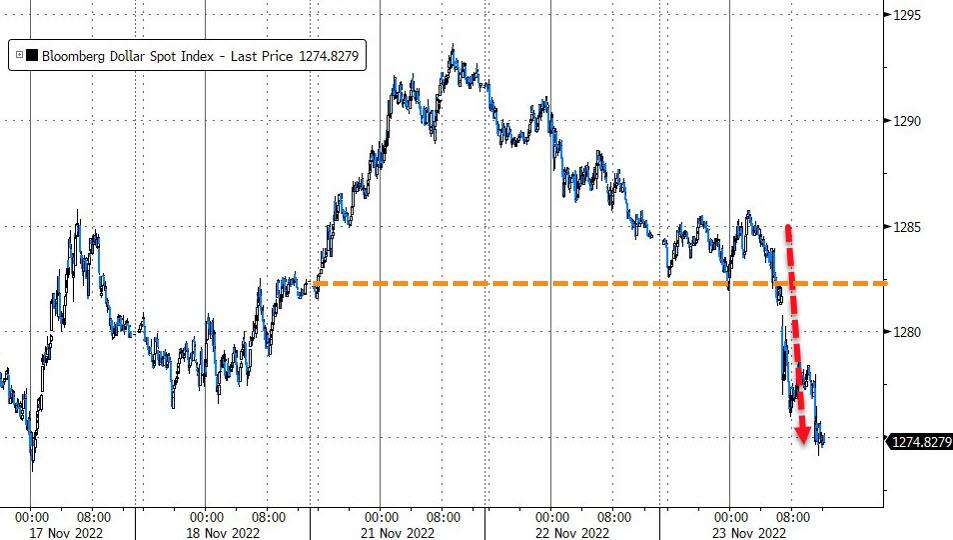
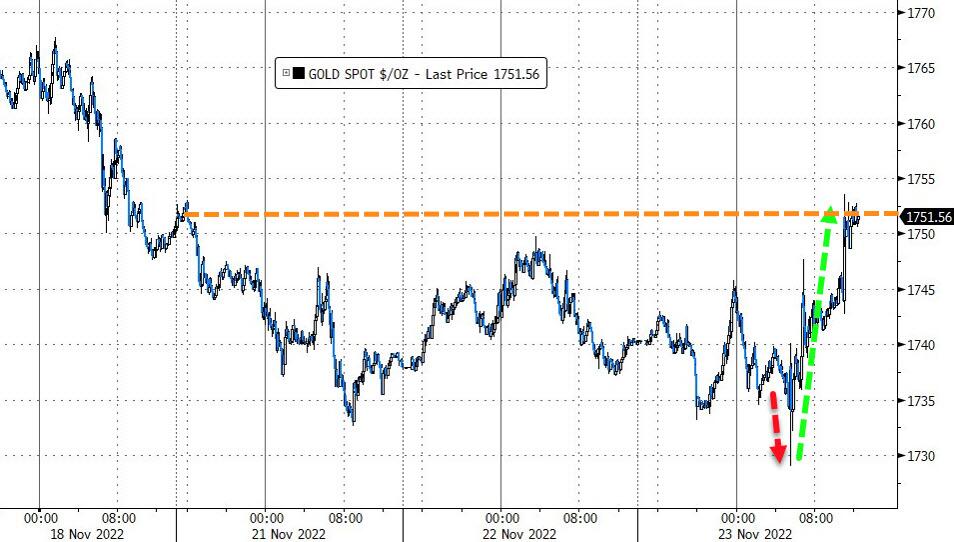
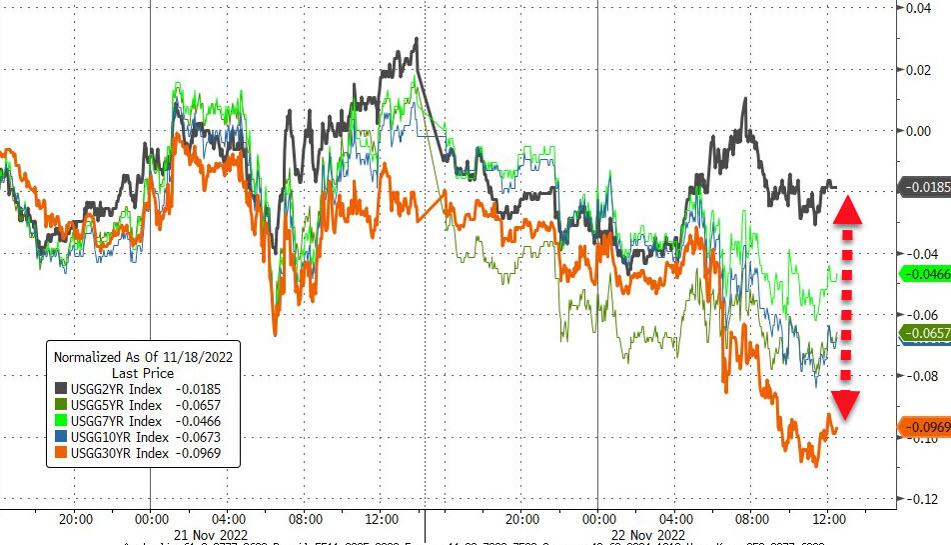
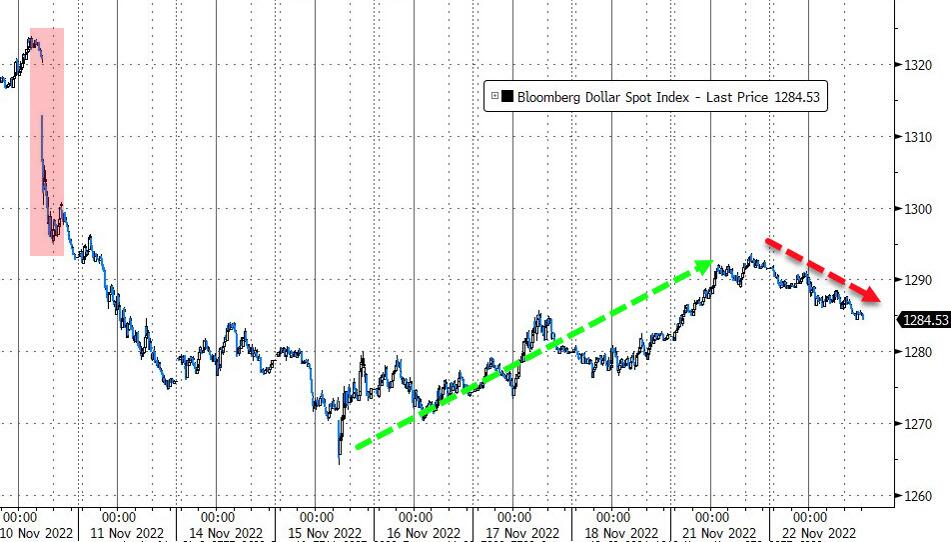
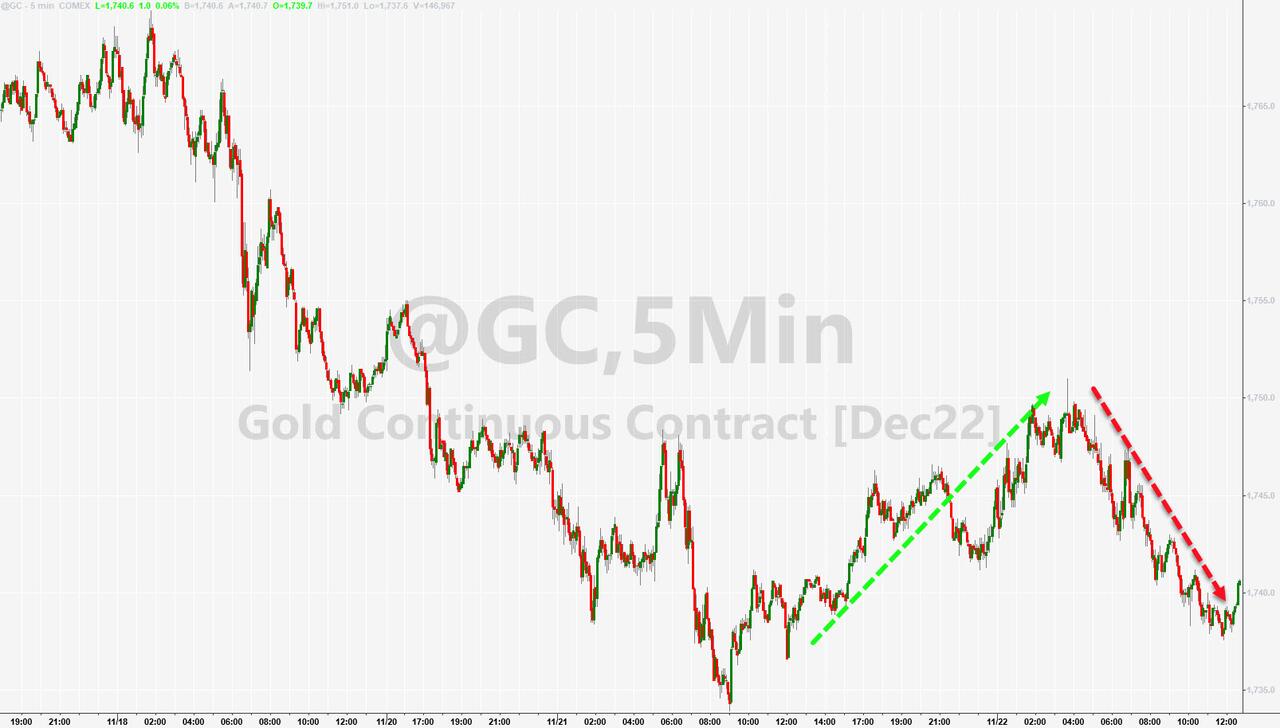
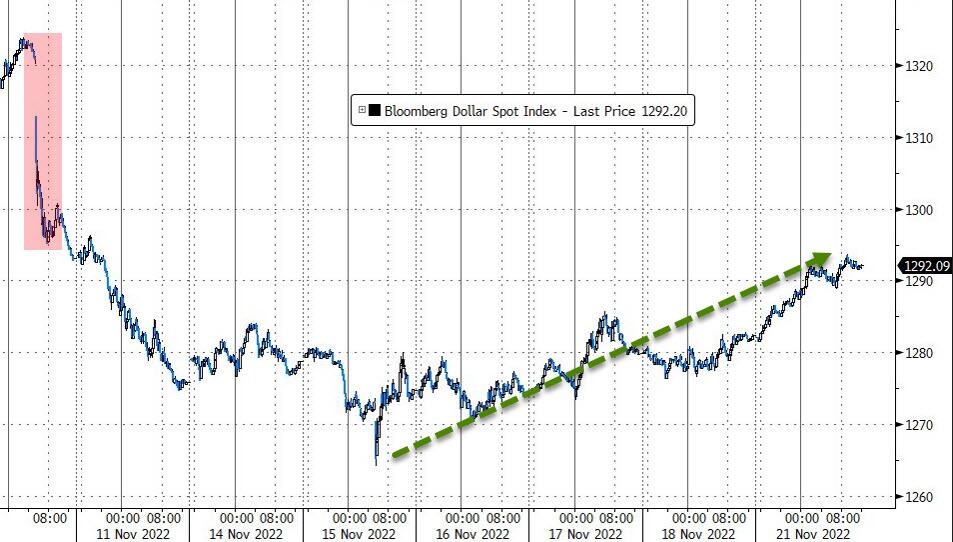
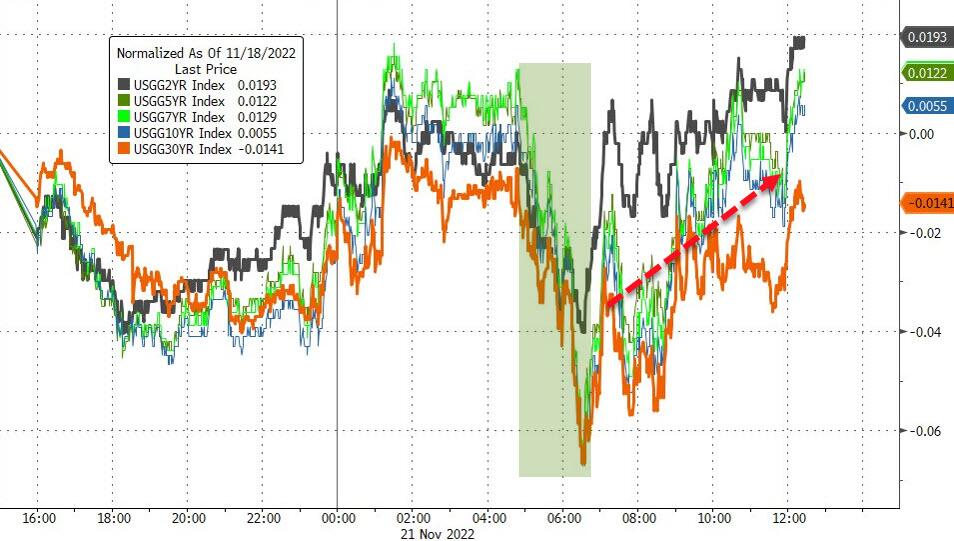
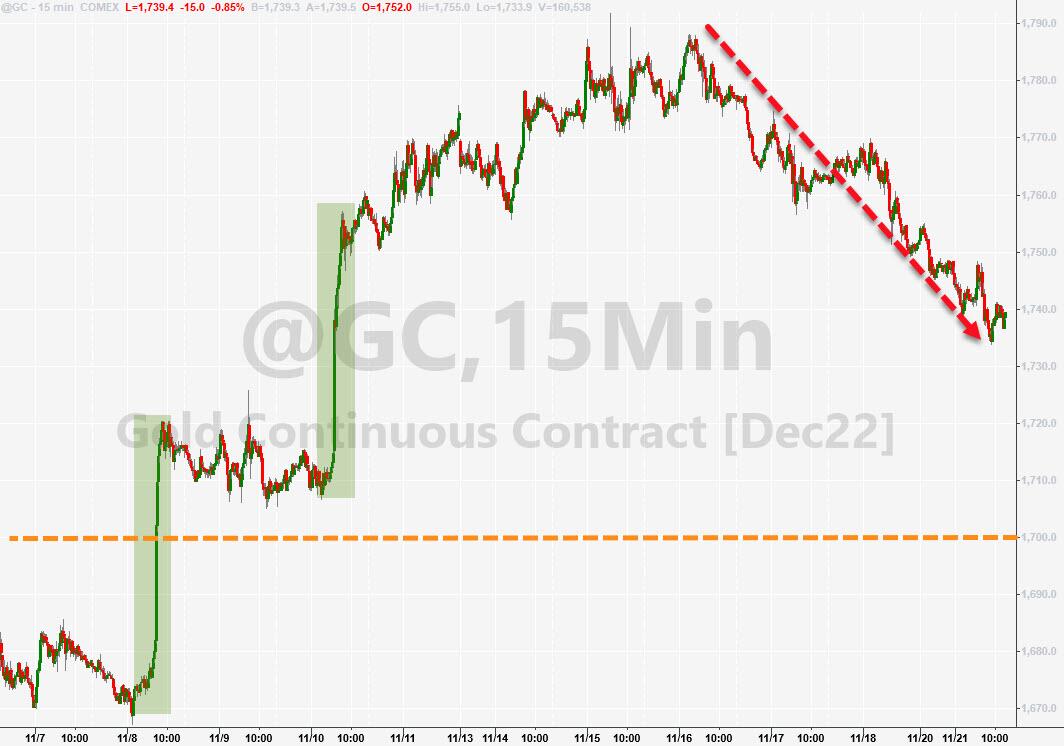
Bond yields rose a tad, with the widely followed 10-year bouncing off of yesterday’s lows. The US Dollar rode the roller-coaster again and slipped from yesterday’s close, thereby helping Gold to score some gains for the session.
Looking at the big picture, it appears that Central Banks all over the world are continuing to be in more of a tightening mood to battle the inflation monster, which has adversely affected consumer prices around the globe.
Read More