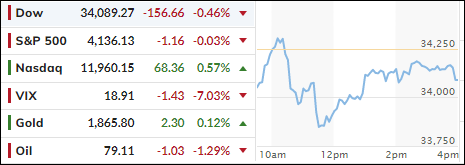
[Chart courtesy of MarketWatch.com]
- Moving the markets
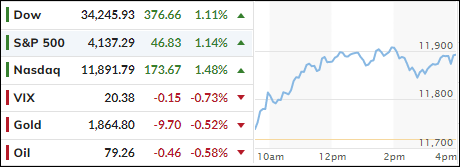
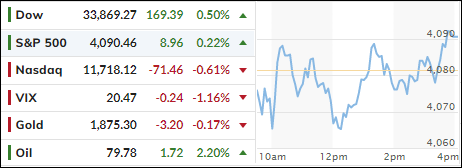
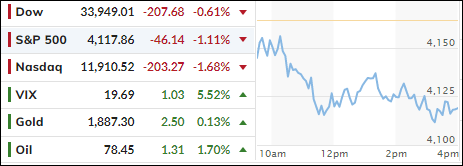
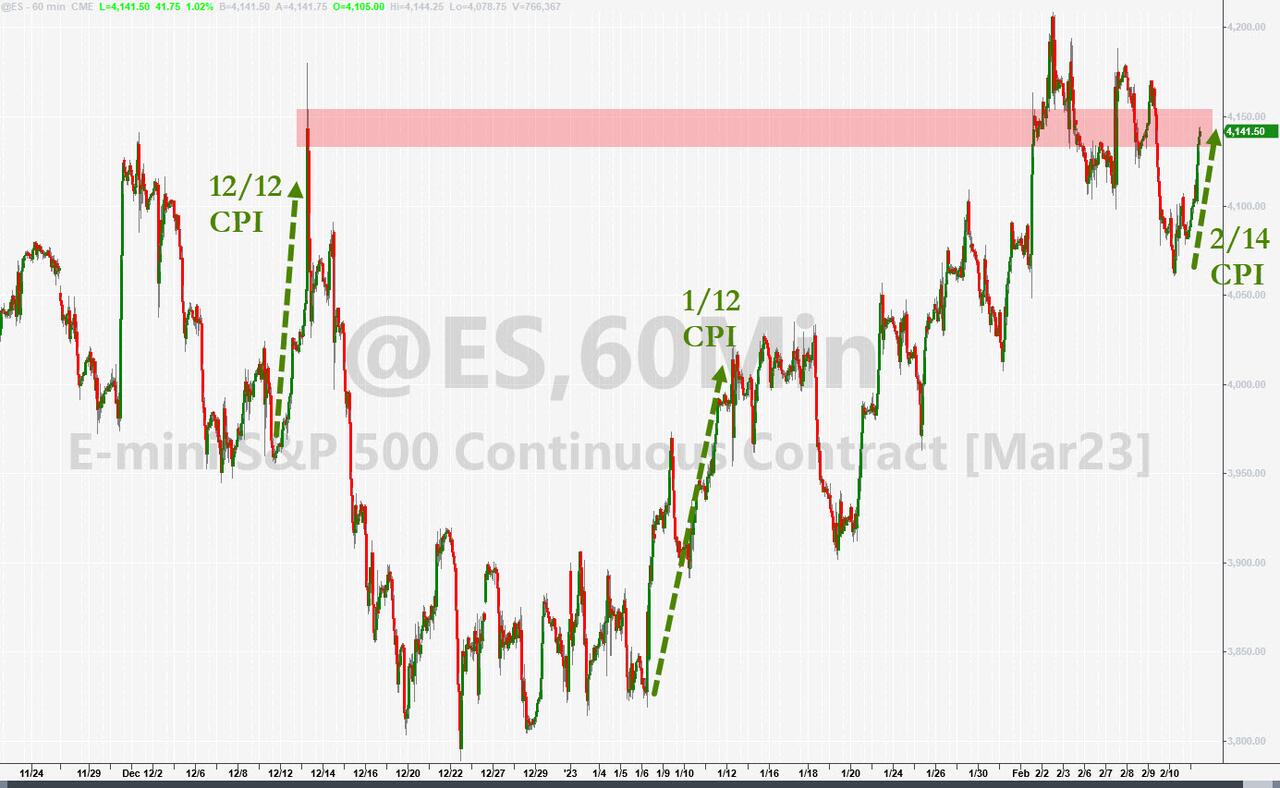
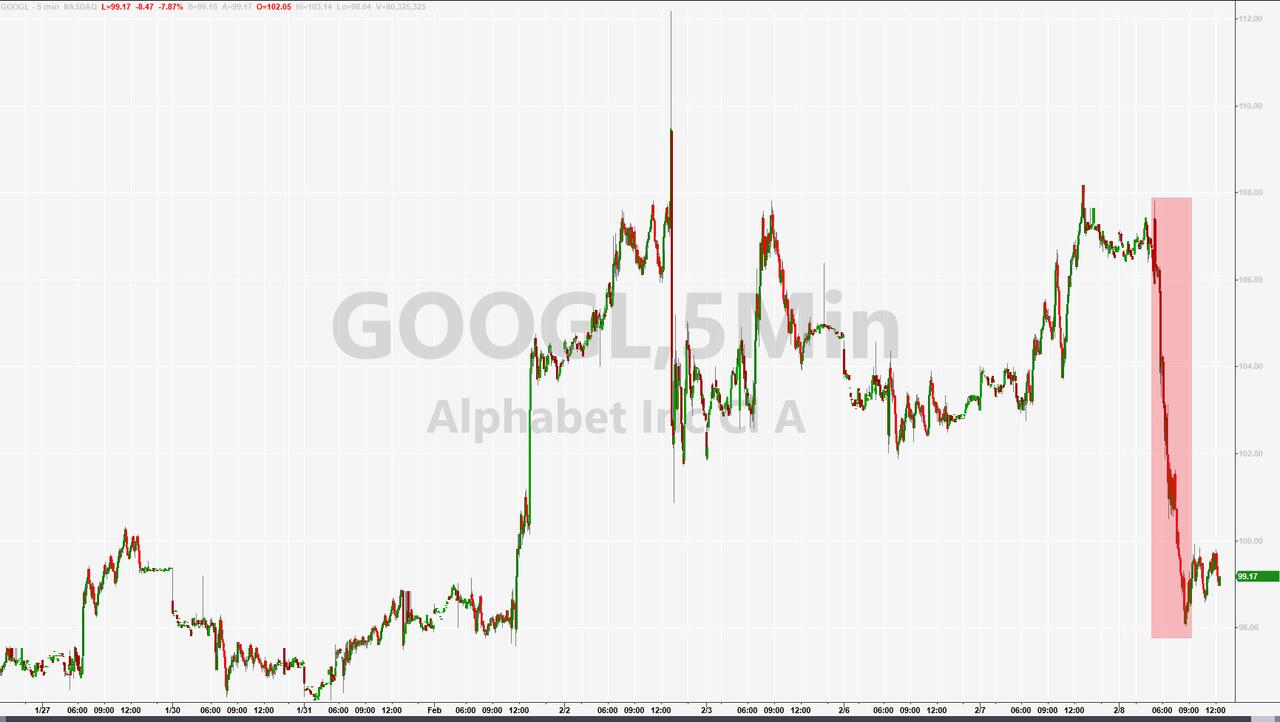
Wild chaotic swings during the early marked the uncertainty connected with the hotter-than-expected January CPI report. Stocks dumped, pumped, and dumped again before managing to recover steep early losses. The reversal pushed only the Nasdaq back above its respective unchanged line by a moderate margin.
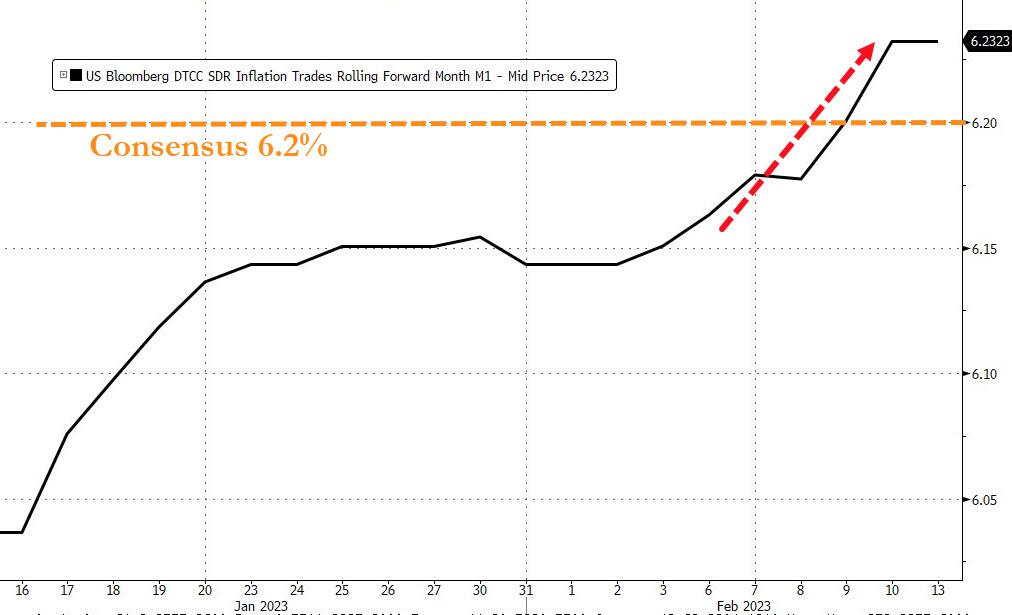
The CPI rose 0.5% for the month, which translates to annual growth of 6.4%. Those number were higher than the expected 0.4% and 6.2% forecasts. Casting a further shadow on the report was December’s revision to show a small gain rather than a decline.
Even though the report was better than dreaded, it also caused anxiety due to the Fed likely not being willing to take its foot off the rate hike accelerator, as it now appears that inflation may not have peaked yet, which had been hoped for by the always optimistic Wall Street crowd.
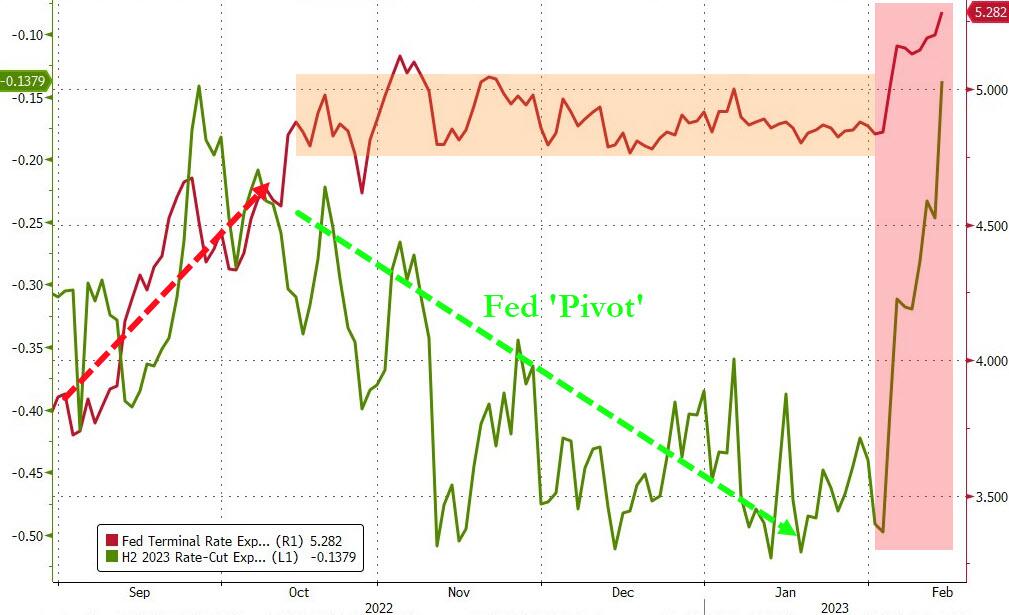
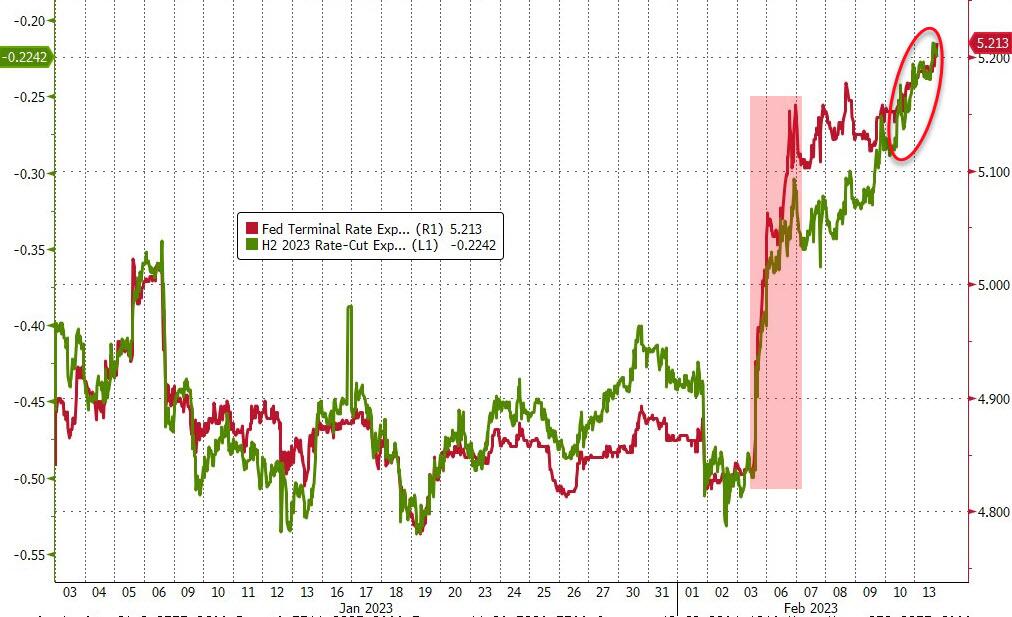
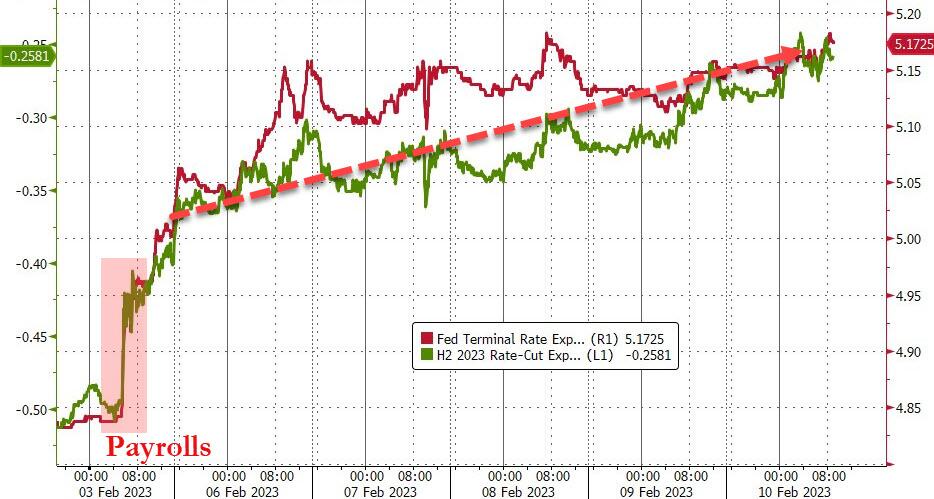
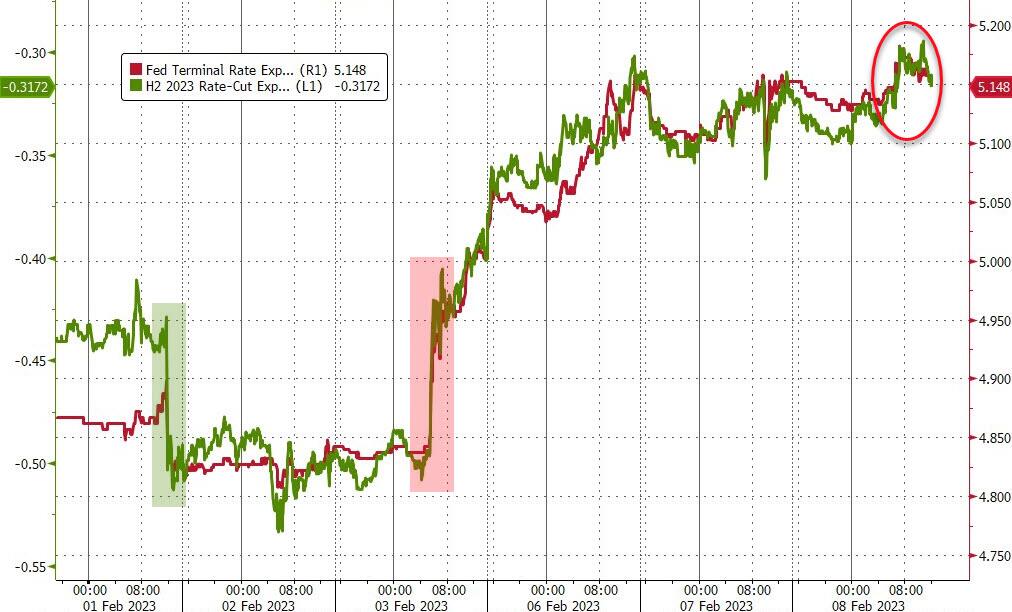
The Fed pivot narrative seems to have died a sudden death, at least for the moment, as rate cut expectations soared, thereby aligning with the Fed’s terminal expectations rate, which now has climbed to 5.3%, as ZeroHedge reported.
Traders did not have to wait long for the usual parade of Fed speakers (Barkin, Logan, Harker, Williams) to appear, to spew the words that Wall Street dislikes with a passion and has fought for months.
Some of the abbreviated highlights contained phrases I have quoted over the past year, things like “leaving Fed rates higher for longer,” “more hikes may be needed than previously seen,” “we are not done yet,” and “our work is not done yet.”
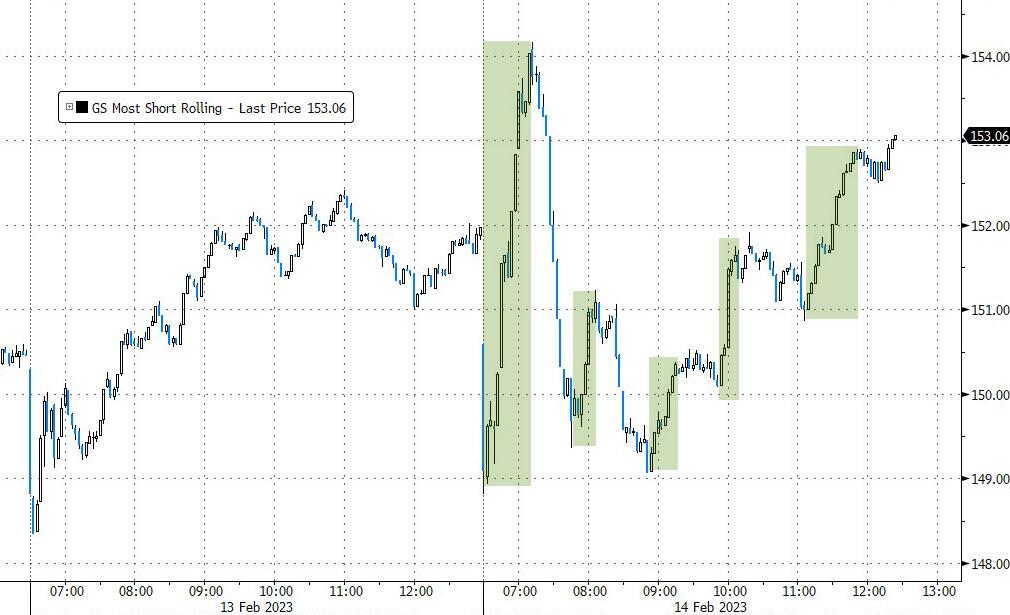
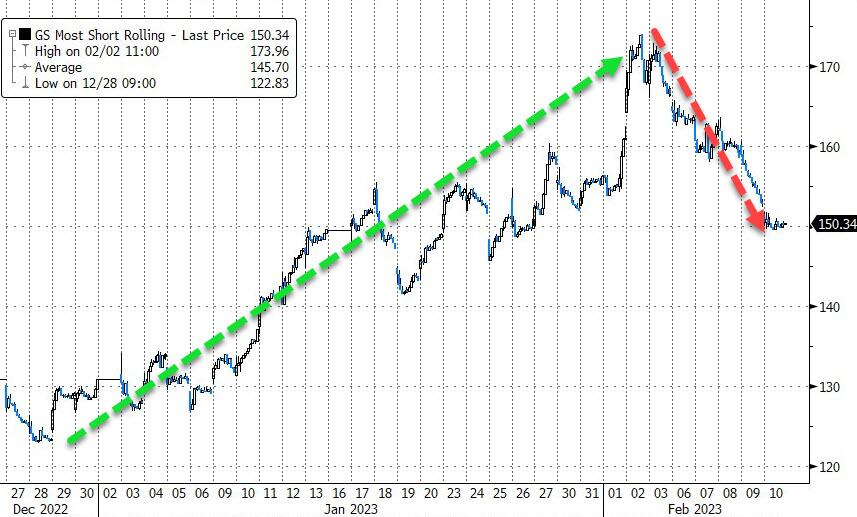
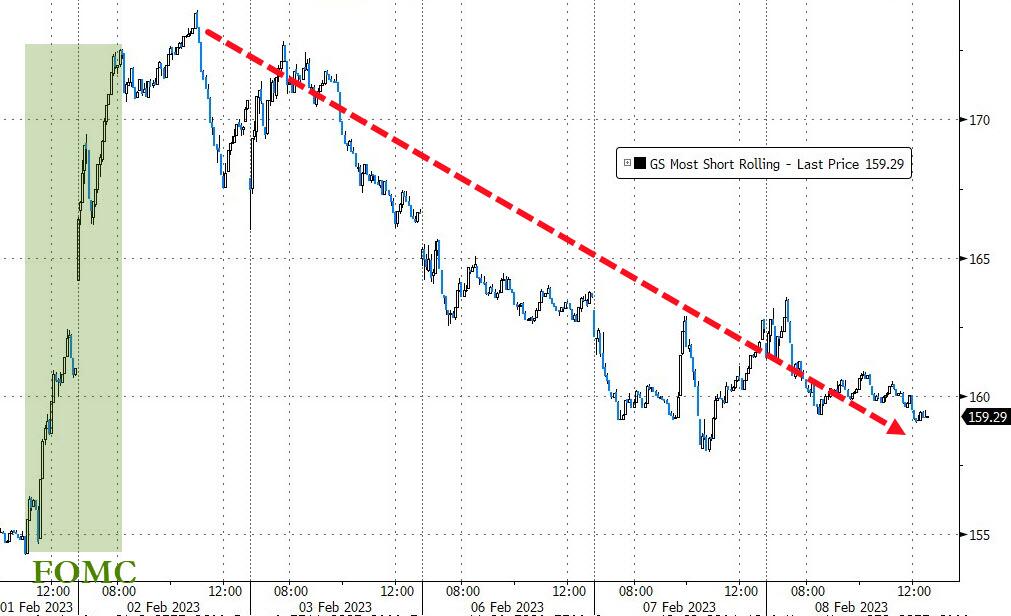
Several efforts to incite a short squeeze worked out in the end and propelled the indexes out of a deep hole.
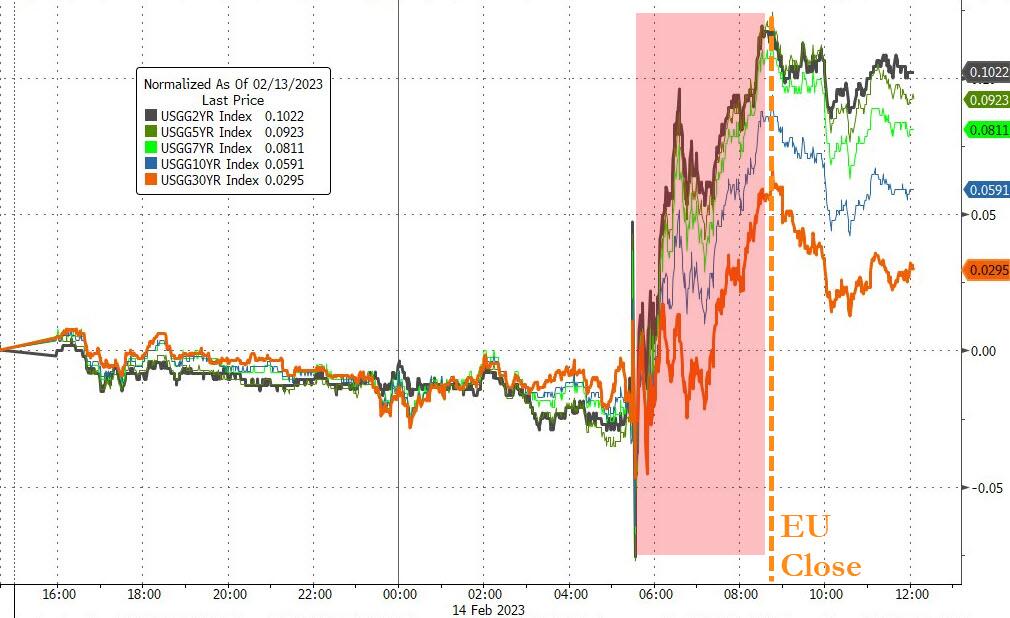
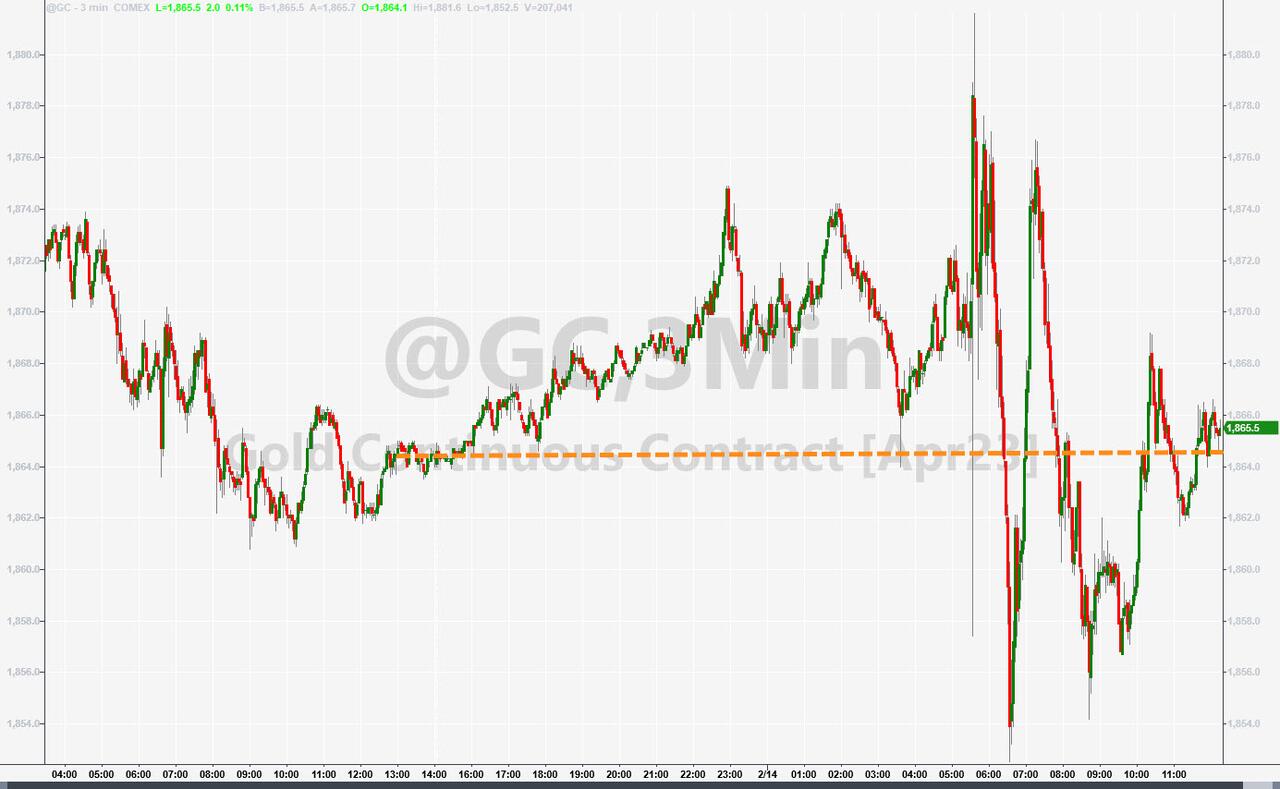
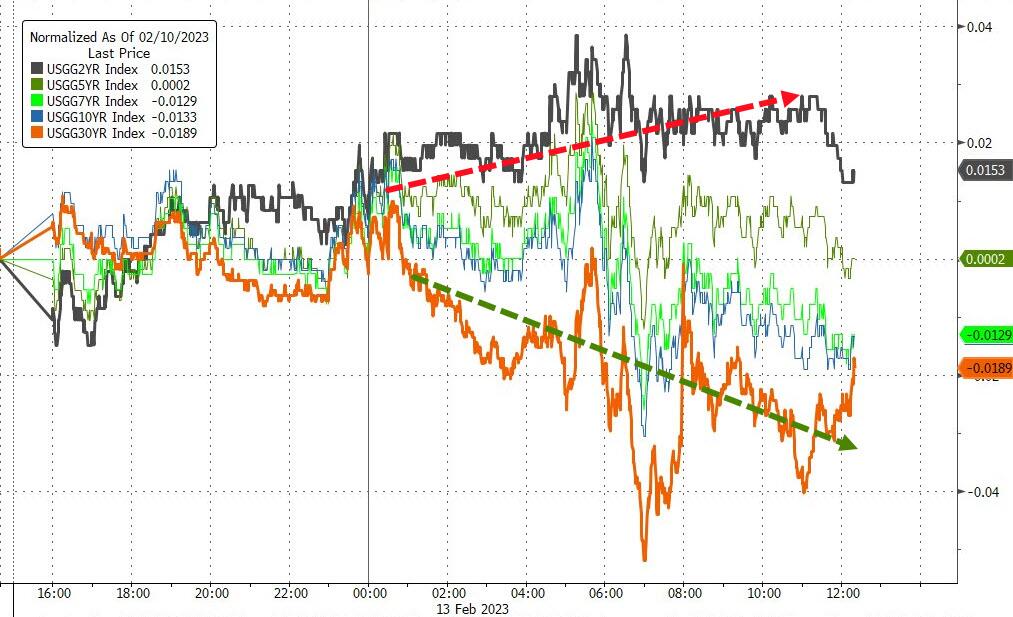
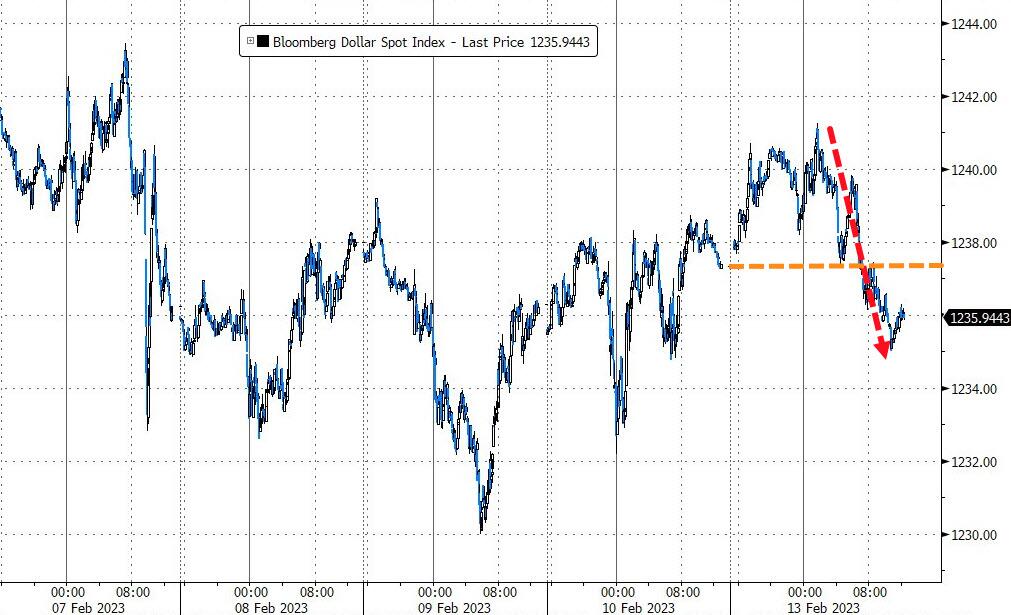
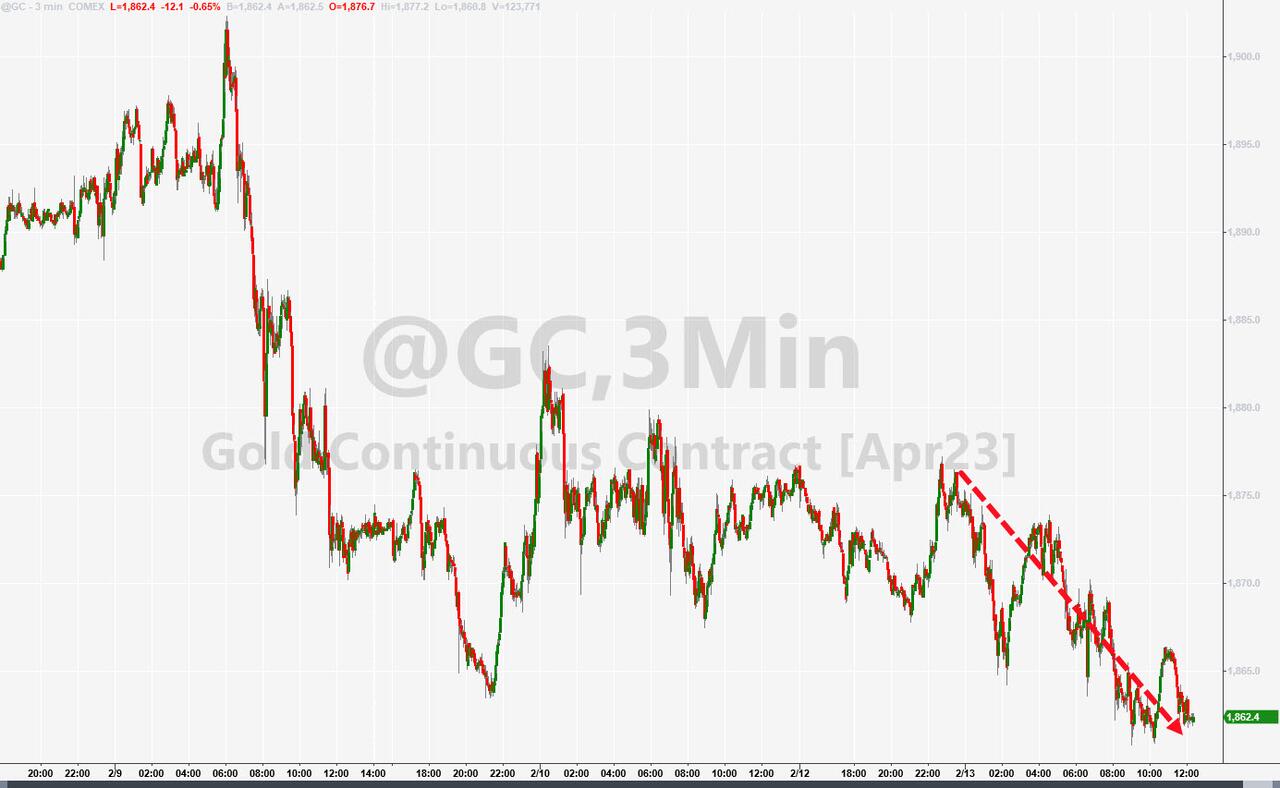
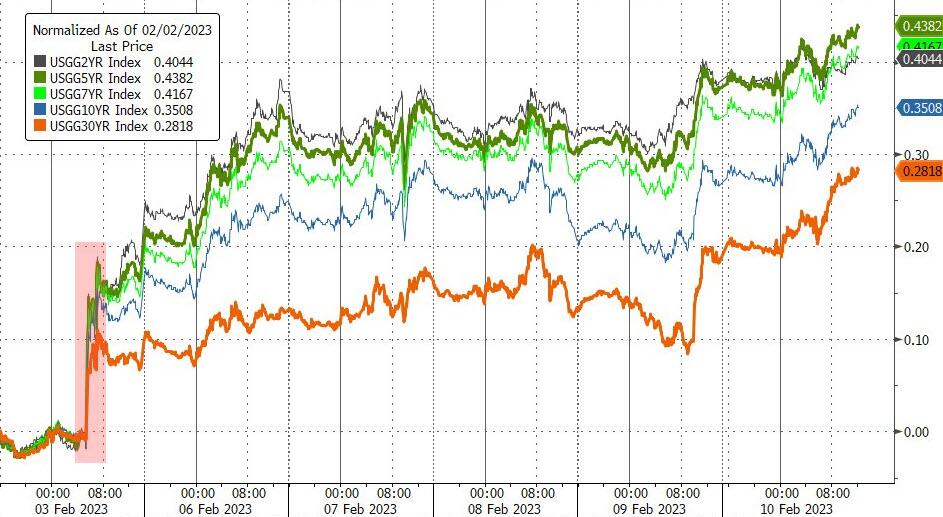
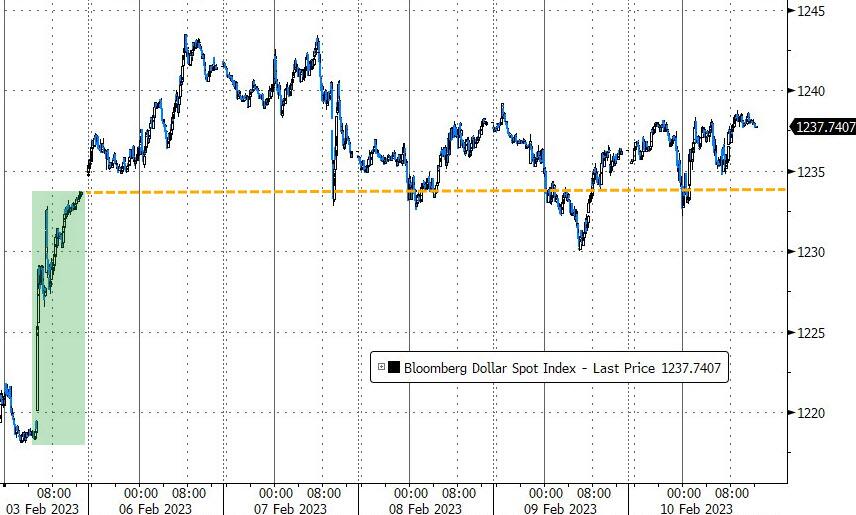
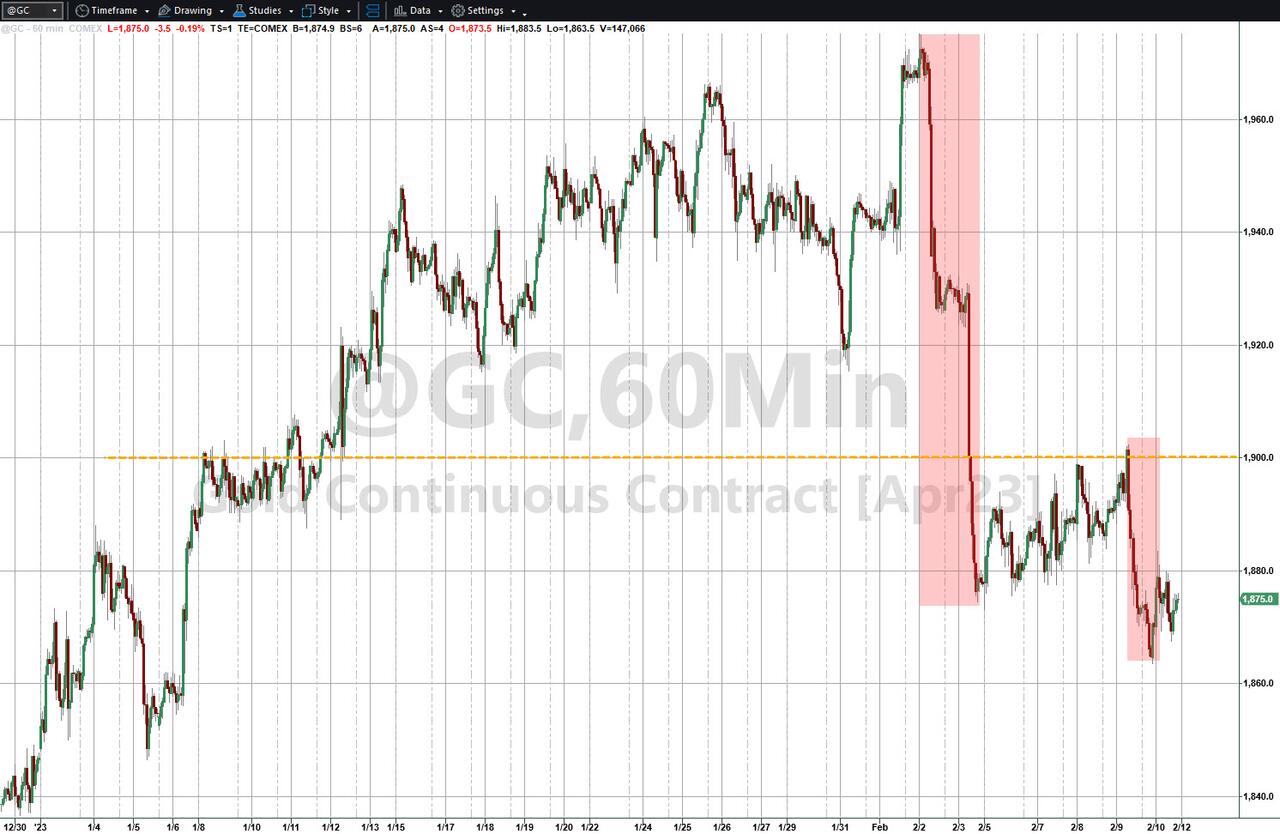
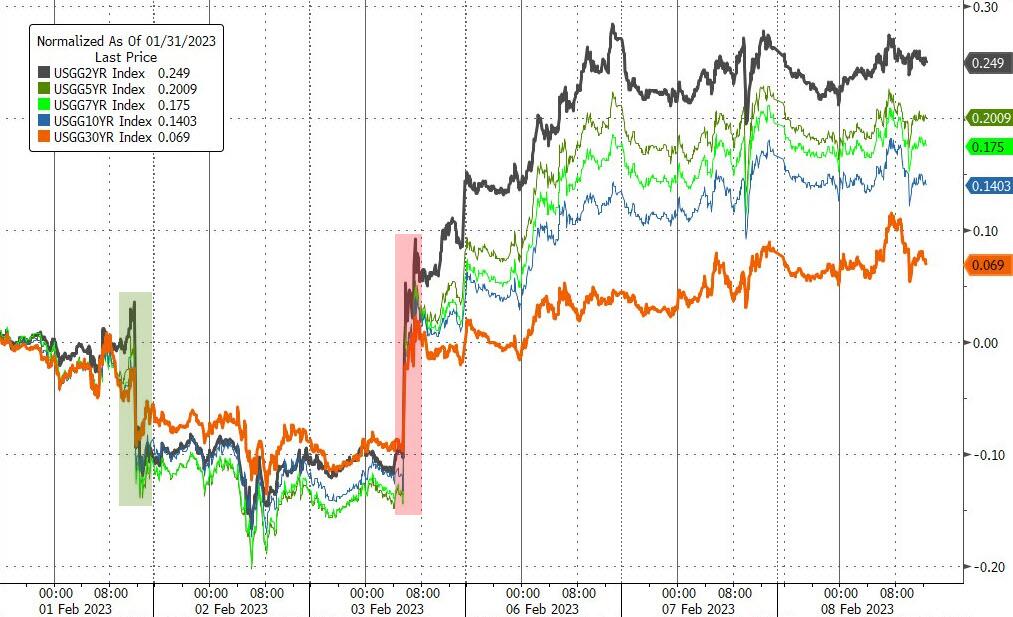
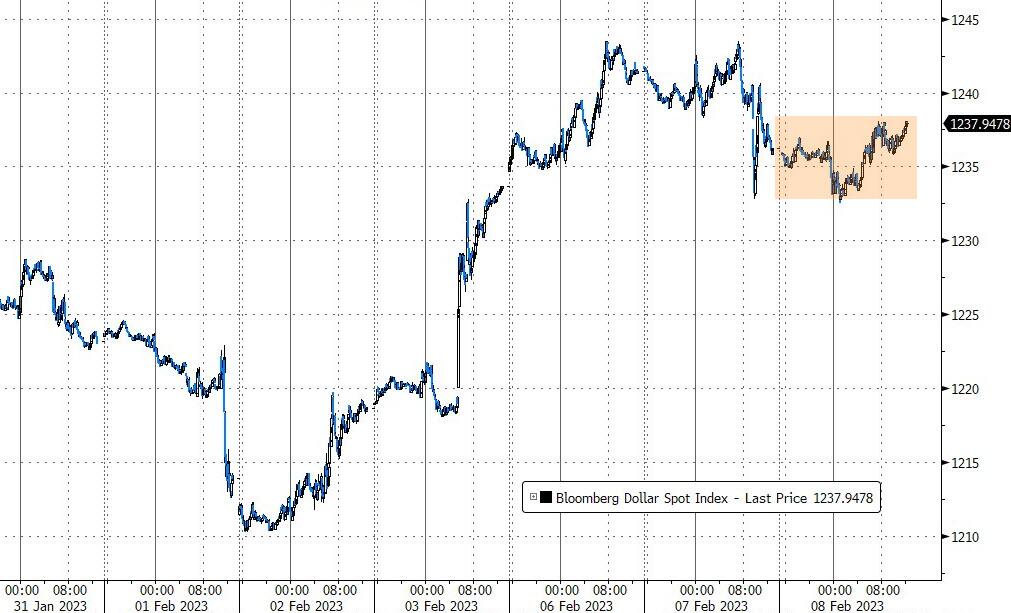
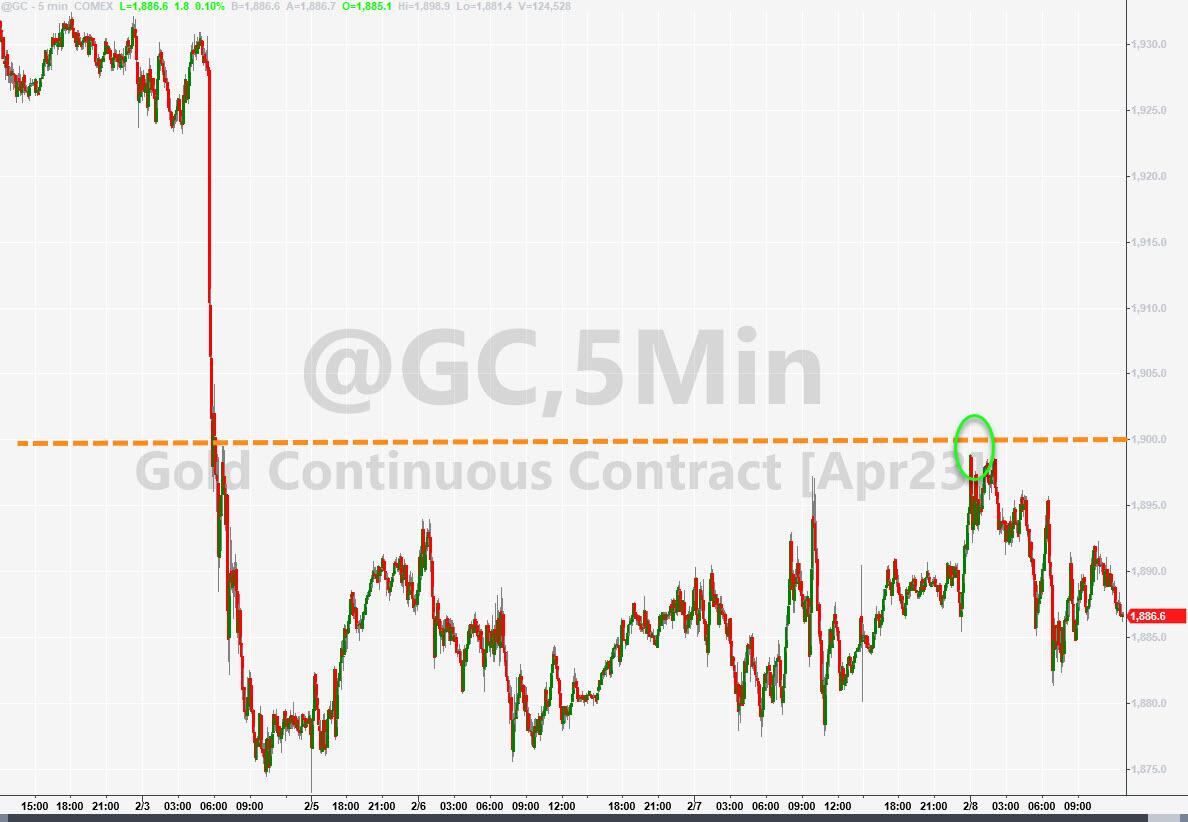
Bond yields soared, but the US Dollar only managed to roundtrip, with nothing gained, while Gold swung wildly and only edged out a tiny gain.
Retails sales are on the main menu tomorrow. A blowout positive number would be bad for equities, because it would confirm the Fed’s hawkishness to be the right cause of action for the time being.
Read More