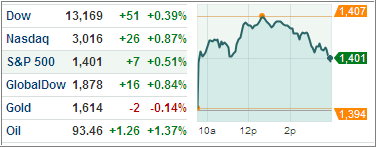
Continued optimism that the ECB would act ‘real soon’ to contain the euro debt crisis powered equities higher over the past week with the S&P 500 closing slightly above the 1,400 level for the first time since May.
Obviously, as is always the case at this time of the year, trading volume has been extremely light, which can easily exaggerate moves in both directions.
As I have said before, we may now have reached ‘goldilocks’ territory, where just about all potential positives have been priced in the markets, and where any disappointment in regards to expected outcome or actions by the ECB/FED will have dire consequences.
I believe that there is limited upside potential but accelerated downside risk, which could come into play at anytime. That means, unless you are a very aggressive investor, you would be well served by not adding new money at these levels.
Of course, EU politicians in charge could prove me dead wrong by coming up with more new and innovative ways to postpone the inevitable and, as a result, push markets higher; but so be it.
Looking at the big picture, this is the time to be more concerned with capital preservation rather than capital gains as the downside can come in quickly and without much warning.
In the meantime, here’s the latest model portfolio update: