08-05-2012

Ulli Newsletter Archives Contact

The ETF/No Load Fund Tracker—Monthly Review—July 31, 2012

Super Mario’s Pledge Pulls Stocks Out Of The Doldrums

The European Central Bank President Mario Draghi’s pledge to do “whatever it takes” on July 26 to restore investor confidence in the euro zone triggered a global market rally.

Speculation was rife the ECB will initiate another round of LTRO, restart the Securities Market Program to buy Spanish and Italian bonds from the secondary market and cut the key interest rate further to boost growth.

The initial euphoria over Draghi’s bullish pledge, however, proved fleeting in the absence of clarity from the central bank, and markets remained cautious on the last two trading days of the month.

Nonetheless, all of the three major indexes finished higher in July with the Dow posting its ninth monthly gain in 10. The S&P 500 finished 1.3 percent higher over June while the NASDAQ ended near flat with a paltry 0.4 percent gain.

An important development in July was the downgrading of Germany to ‘AAA-negative’ from ‘Stable’ along with Netherlands and Luxemburg by Moody’s citing growing risk from a possible Greece exit or bailout for Spain and Italy.

US economic recovery remained steady though the pace fluctuated slightly. Data released on July 27 showed that GDP for the second quarter grew at a meager 1.5 percent against an estimated 1.2 percent. The economy had grown at 1.9 percent in the first quarter.

US Consumer Confidence rose for the first time in six months as Americans grew more hopeful of employment prospects. A separate report from the Commerce Department showed US wages climbed in June while consumer purchases slowed, indicating consumers are still pretty cautious about spending.

Economists expect growth to accelerate modestly in the third quarter due to continued recovery in the housing sector. The closely watched S&P/Case-Shiller 20-city composite index of US home values showed home prices rose 2.2 percent in May with all the 20 cities recording monthly gains. The Fed’s Beige Book also supported the recovery stating the residential housing indicators were largely positive though drought is a worry for crops and livestock.

The Q2 earnings season remained ho-hum with roughly two thirds of the 300 companies that announced results till July 27 managing to beat sharply reduced earnings forecasts. However, nearly 60 percent of the firms missed revenue forecasts, more than twice of that in Q1.

In terms of trends not much changed as the Domestic Trend Tracking Index (TTI) remains on bullish side of the trend line by +2.72% as the chart shows:
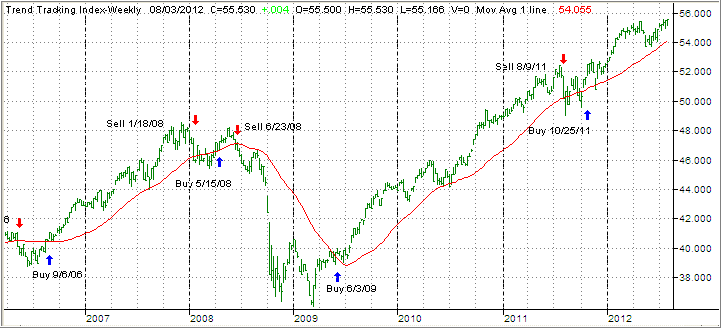
While we have distanced ourselves a bit from a possible trend line break, as opposed to where we were last month, we also have reached extremely lofty market levels not due to sound underlying economic fundamentals, but only due to the ever present Fed and its financial weaponry ready to be deployed to prop up the markets.

As we’ve seen this past week, just empty jawboning without substance by the likes of ECB head Draghi proved sufficient to move the markets higher—at least for the moment!

There were no changes to our invested positions, and I continue to observe market behavior with a very skeptical eye, especially when it comes to Europe. Since there is no sound policy in place to reduce debt and deal with insolvency, all plans are simply calling for more debt to postpone the inevitable. If can kicking were to be an Olympic sport, the Europeans would very likely take gold, silver and bronze.

Once the first domino falls (default), which to me is not a question of ‘if’ but ‘when,’ there will be consequences to markets around the world and those who believe the US can decouple are just not thinking clearly. I plan on being prepared for when that happens via our exit strategy; although the timing of such an event remains the big unknown.
New ETFs On The Block: ALPS Sector Dividend Dog ETF (SDOG)

Ulli Dividend ETFs Contact

ALPS, the Denver-based small ETF issuer known for its commodity focused products, introduced a fund that combines high dividend yielding stocks with equal sector-weighting methodology.

The new product, the Sector Dividend Dog ETF (SDOG) offers exposure to the highest yielding 50 stocks by applying the well-known “Dogs of the Dow” methodology from a wider set of stocks instead of the S&P 500.

SDOG selects stocks across all the 10 sectors of the market and picks five highest yielding stocks from each sector, ensuring diversification at both the stock and sector level. The “Dogs of the Dow” strategy, made famous by Michael O’Higgins in 1991, is based on the premise that blue-chip companies don’t adjust dividends to reflect current trading prices, and therefore while stock prices fluctuate through business cycles, dividends in contrast, is an indicator of average worth of the company.

This means companies trading at a high-dividend yield ratio are at the bottom of their business cycles and hence are likely to appreciate faster than low yield stocks when the business cycle changes.

Read More

08-02-2012

Ulli Newsletter Archives Contact

ETF/No Load Fund Tracker Newsletter For Friday, August 3, 2012

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2012/08/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-08022012/

————————————————————

Market Commentary

Friday, August 3, 2012

AFTER FOUR DAYS OF LOSSES, US EQUITIES RALLY ON IMPROVED JOBS DATA; EWI FLIES, VXX CRASHES

US equities rallied for the second straight session Friday following a forecast-beating July jobs data report that indicated a gradual but robust healing of the jobs market. The Dow Industrials extended its longest weekly winning streak this year amid speculations the European Central Bank will soon restart its bond purchase program to bring down high Spanish and Italian borrowing costs.

The Dow Jones Industrial Average (DJIA) surged 217 points to 13,096, its fourth up week in a row. 27 of the 30 components within the blue-chip index advanced, ending the week higher 0.2 percent.

The S&P 500 Index (SPX) climbed 26 points to 1391 with financials leading the gainers and telecommunications lagging among its 10 business groups. This was a welcome reprieve after 4 days of losses with traders hanging their hat on the positive spin of the employment numbers forgetting for the moment that the market driver of the recent past, namely QE hopes, may have just vanished for the time being.

Treasuries fell the most in a week as safe-haven assets lost allure after a report showed the economy created 163,000 jobs in July, a significant improvement over the 63,000 that was added in the prior month and diminished possibilities of another round of quantitative easing by the Federal Reserve, at least not in the near future. It makes me wonder what will lift the markets from here as the ho-hum earnings season winds down.

Risk sentiment improved after media reports suggested Angela Merkel’s coalition partners will not create hurdles to ECB President Mario Draghi’s plan to restart the Securities Market Program (SMP). Treasury 10-year benchmark yield jumped nine basis points to 1.56 percent. 30-year bond yield also soared nine basis points to trade at 2.65 percent by late afternoon.

ETFs in the news:

Positive developments in Europe on Friday triggered a rally in Spanish and Italian ETFs, pushing both the iShares MSCI Spain Index Fund (EWP) and the iShares MSCI Italy Index Fund (EWI) higher by more than 7 percent.

Media reports suggested Madrid has submitted a plan to the European Council on Friday to save $125 billion over three years. The Iberian country also expects the economy to start growing by 2014. Also leaders of Italy and Spain met in Madrid this week and pledged to work together to resolve the debt crisis.

Agricultural commodity linked funds also rallied as drought and subsequent crop failure looms over vast swathes of the country. Wheat futures rallied 3 percent due a weak dollar and better outlook over corn and soy. The Teucrium Wheat Fund (WEAT) vaulted 3.43 percent on the day as September futures gained 3.2 percent Friday to trade at $8.92 per bushel.

As risk sentiment improved, the fear-tracking CBOE Volatility Index (VIX) crashed. The ProShares VIX Short-Term Futures ETF (VIXY) was one of the biggest decliners, shedding 6.84 percent on the day. Other VIX tracking funds also posted dismal results, the Barclays iPath S&P 500 VIX Short-Term Futures ETN (VXX) slumped 6.68 percent as positive US jobs data cooled off market volatility.

Our Trend Tracking Indexes (TTIs) retreated during the sell-off early in the week and then rallied with the major indexes today:

Domestic TTI: +2.72% (last week +2.86%)

International TTI: -0.03% (last week -0.41%)

Have a great week.

Ulli…

Disclosure: No holdings

————————————————————-

READER Q & A FOR THE WEEK

All Reader Q & A’s are listed at our web site!
Check it out at:

http://www.successful-investment.com/q&a.php

A note from reader Roger:

Q: Ulli: I have been a long term observer of your daily newsletter since 2007, and I enjoy your insight into the Market and investments. You saved me a lot of pain by convincing me to get out of the Market before the 2008 crash.

I was wondering if you could provide your latest insight into the market. It seems to me that it will continue to move sideways until September, due to the uncertainty in the world economy and erratic housing recovery. What is your earnest opinion and outlook for the rest of the year?

A: Roger: As in 2008, my views are based on the trends in the market place. Right now, we are still in buy mode on the domestic side after having slipped below the line in the international arena back on 5/15/12.

With the global slowdown accelerating, and the Europeans continuing to excel in talking but not in coming up with solid plans to solve their debt crisis, another sharp market pullback is a distinct possibility. As I have commented many times, the only thing that keeps the domestic market at these levels is the hope for more QE by the Fed.

I would expect another sharp selloff but we need to cross below the Domestic TTI trend line to the downside first, before I become very bearish. At that time, anything is possible and a domino effect will be likely. Actually, there are many trigger points that could cause a sudden market reversal. One is Spain, a country that seems to have run out of money and may be defaulting on their debt well before Greece does. That’s just a guess right now, but stay tuned to the direction of the Domestic TTI, as it has been a great guiding light in avoiding major market crashes since the 80s.

———————————————————-

WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?

Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly or get more details at:

https://theetfbully.com/personal-investment-management/

———————————————————

Back issues of the ETF/No Load Fund Tracker are available on the web at:

https://theetfbully.com/newsletter-archives/

ETF/No Load Fund Tracker Newsletter For Friday, August 3, 2012

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2012/08/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-08022012/

————————————————————

Market Commentary

Friday, August 3, 2012

AFTER FOUR DAYS OF LOSSES, US EQUITIES RALLY ON IMPROVED JOBS DATA; EWI FLIES, VXX CRASHES

US equities rallied for the second straight session Friday following a forecast-beating July jobs data report that indicated a gradual but robust healing of the jobs market. The Dow Industrials extended its longest weekly winning streak this year amid speculations the European Central Bank will soon restart its bond purchase program to bring down high Spanish and Italian borrowing costs.

The Dow Jones Industrial Average (DJIA) surged 217 points to 13,096, its fourth up week in a row. 27 of the 30 components within the blue-chip index advanced, ending the week higher 0.2 percent.

The S&P 500 Index (SPX) climbed 26 points to 1391 with financials leading the gainers and telecommunications lagging among its 10 business groups. This was a welcome reprieve after 4 days of losses with traders hanging their hat on the positive spin of the employment numbers forgetting for the moment that the market driver of the recent past, namely QE hopes, may have just vanished for the time being.

Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 08/02/2012

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, August 2, 2012

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


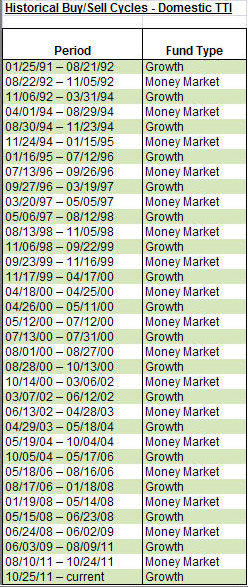
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

The domestic TTI broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities went into effect.

As of today, our Trend Tracking Index (TTI—green line in above chart) has broken above its long term trend line (red) by +2.20%. A break back below it will generate a Sell signal to move out of all domestic equity positions. Be sure to tune into my blog for the latest updates.

Read More

Draghi Drags Down Major Indexes—Confirms He Is ‘All Hat And No Cattle;’ KWT Rallies, UNG Slips

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

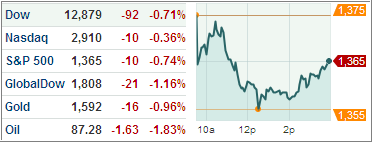
US major indexes extended their losing streak for the fourth straight day Thursday after the European Central Bank failed to deliver on its earlier pledge to halt a further decline of the ongoing sovereign debt crisis.

ECB president Draghi, who last week single handedly ignited a rally in equities with talk of upcoming bazooka like actions, retreated today by announcing….no action at all. Given his chest pounding speech of last week, he now has cried ‘wolf’ one too many times and may very well have lost his credibility in the process.

This really should come as no surprise to you, as European policticians have refined the art of holding countless meetings and summits over the past year without accomplishing a thing.

Read More