ETF/No Load Fund Tracker Newsletter For May 22, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/05/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-05212015/

————————————————————

Market Commentary

MARKETS CLOSE LOWER FRIDAY, BUT ROUND OUT A SOLID WEEK
Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

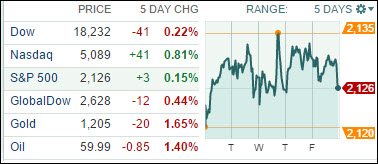
Stocks ended lower ahead of the Memorial Day holiday weekend as Fed Reserve Chair Janet Yellen reconfirmed that the central bank remains on track to raise interest rates this year.

Today, in the release of the minutes of its April 28-29 meeting, the Fed suggested that it was “unlikely” that they would hike rates in June. Financial markets began speculating the Fed would delay a rate hike given the weak spate of economic data that has been released recently.

Although Friday stocks ended lower, markets finished the week higher, reaching a fresh all-time high on Thursday. Performance across sectors was mixed as well. Telecom and health care stocks were the strongest upward movers, while energy and materials moved lower.

Markets will be closed on Monday for Memorial day, however, the week will start with a busy Tuesday, with durable goods orders, the Case-Shiller house price index, new home sales, and consumer confidence all being released. Weekly jobless claims and pending home sales will both be released on Thursday.

All of our 10 ETFs in the Spotlight slipped today with the Financials (IYF) holding up the best with a tiny 0.03% loss, while the Global 100 (IOO) fared the worst by giving back 0.57%.
Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 05/21/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, May 21, 2015

TOC021915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/22/2014

TTI

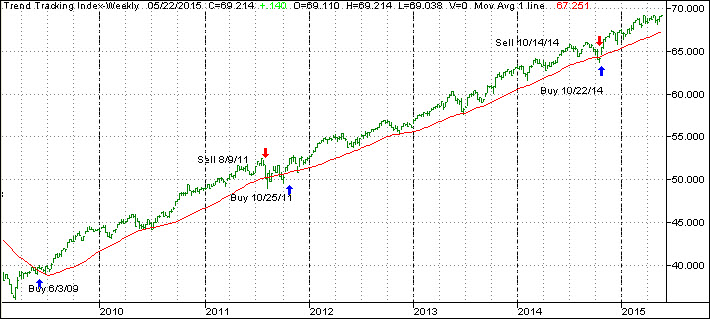
Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a “Sell” for this arena effective 10/14/2014, which was followed by a violent break back above the line on 10/22/14 generating a new “Buy.” It was a classic whipsaw signal, and you can read more on my blog as to the events as they were unfolding.

As of today, our TTI (green line in above chart) is positioned above its long term trend line (red) by +3.06% keeping us in the market with our established positions.

Read More

Best Buy Posts Higher Earnings; CVS To Buy Omnicare

Ulli Uncategorized Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

U.S. stocks closed modestly higher on Thursday, with the Nasdaq outperforming, as investors eyed slightly lower bond yields and mostly shook off the morning’s mixed economic data.

In M&A news, CVS Health (CVS) said today that it has agreed to buy pharmacy services provider Omnicare (OCR) for $12.7 billion. The acquisition is foreseen to be a move to expand its presence in the senior care market. Omnicare, the nation’s largest provider of pharmaceutical services in nursing homes, has 160 locations in assisted living and long-term care facilities in 47 states in the U.S. To complete the deal, CVS said it has secured a $13 billion short-term loan from Barclays and will eventually issue a debt or get term loans before the deal closes.

In earnings news, shares of Best Buy (BBY) surged 3.9% today after reporting earnings and revenue that easily beat Wall Street estimates. The consumer electronics retailer reported net income of $129 million, or 36 cents a share, in the first quarter. That was down from $461 million, or $1.31 a share, a year ago.

And, as for the economy, the consumer price index will be released tomorrow. Let’s stay tuned to see how Friday will turn out.

8 of our 10 ETFs in the Spotlight inched higher as Consumer Discretionaries (XLY) took the lead with a 0.39% gain. On the downside, Financials (IYF) lost 0.32%.

Read More

Stocks Fall From Intra-Day High

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks ended mixed after a short-lived bump, caused by the release of the minutes from the last Federal Reserve meeting, which showed a June rate hike was unlikely. Federal Reserve policymakers said last month that they were unlikely to raise interest rates in June because of the economy’s recent sluggish performance, according to minutes of the Fed’s April 28-29 meeting. Since the April meeting, reports on trade and retail sales have been surprisingly weak, and economists now estimate the economy shrank in the first quarter, further reducing the prospects for a June rate increase

Flying back to the world of airline stocks, shares of airline companies have been taking a hit across the board recently due to speculation that airlines are going to expand capacity, which could lead to lower fares and lower revenue per available seat mile. This may be a case where growth may not be in the best interest of shareholders. It will be interesting to see how this unfolds in the months to come.

In earnings news, we heard today that Salesforce (CRM) reported slightly better-than-expected quarterly earnings and revenue as its cloud computing segments rose year over year. At the same time, Salesforce raised its full-year revenue guidance to a range of $6.52 billion to $6.55 billion, which would mark an increase of more than 20 percent from the previous year.

Again, 3 of our 10 ETFs in the Spotlight gained on the day with the leader being the Global 100 (IOO), which added 0.37%, while on the downside the Financials (IYF) gave back 0.33%.

Read More

Losing Steam

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

It was a struggle for the indexes today, as the upward momentum of the last few days waned and even a last hour rebound lacked spunk and turned out not to be enough for the S&P and Nasdaq to cross above the unchanged line.

Energy stocks sold off sharply as oil prices hit the skids. Since nowadays good news is bad news, the sharp increase in housing starts was seen as a negative and stocks meandered. Why? Because it’s all about the Fed and if/when they will raise interest rates. That means positive economic data will be seen as aiding the Fed in potentially hiking the rates sooner rather than later.

3 of our 10 ETFs in the Spotlight managed to resist this non-directional trading day and closed up with the leader being the Financials (IYF) with a 0.50% gain. On the downside, Consumer Staples (XLP) fared the worst by giving back 0.26%.

Read More

Stocks Move Higher For Third Straight Day; M&A News Back In Headlines

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks jumped in afternoon trading Monday as investors sent the Dow and S&P 500 up for a third straight session and to new record closing highs. The market’s latest rise is due in large part to the idea that an interest rate hike from the Federal Reserve is still due later this year, coupled with companies continuing to buy back their own shares and use cash to other acquire companies. For now though, it seems that Wall Street is simply relieved that a rate hike isn’t coming in June and first-quarter earnings didn’t contract as feared at the start of April.

In M&A news, Ascena Retail Group (ASNA) bought Ann Inc., the parent company of Ann Taylor and Loft retail chains, for about $2.16 billion. Shares of Ann (ANN) surged 19.9% and Ascena fell 1%. Also, in the pharma world, Endo International (ENDP) announced it is buying Par Pharmaceutical Holdings in an $8.05 billion deal to expand its generics business. Shares of Endo fell 5.4%.

As for the economy, U.S. economic reports were generally weaker than expected this week. Thus far in 2015, the pace of economic growth in the U.S. has gotten off to a soft start. Analysts expect the economy to regain momentum though as the year unfolds, and U.S. growth expectations remain above average when compared with developed economies around the globe. Regarding inflation, which seems to be on everyone’s mind lately, the producer price index posted a modest decline in April, excluding the often volatile food and energy components.

8 of our 10 ETFs in the Spotlight joined the upward move and closed on the plus side. The leader of the day were the financials (IYF) gaining 0.61%, while lagging the pack were consumer staples (XLP) with a loss of 0.32%.

Read More