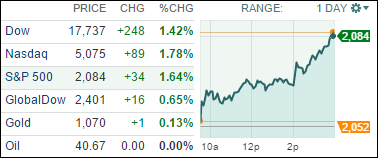
1. Moving the Markets
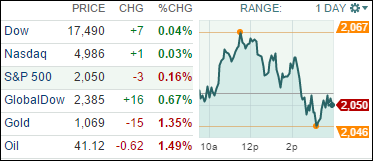
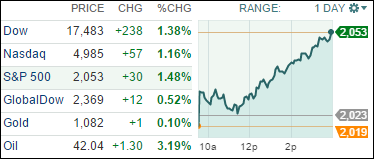
Financial markets have held up well so far this week after the attacks in Paris Friday that sparked global concern about the economic impact of terrorism. Stocks moved higher Wednesday after the release of the Fed minutes of October, as the Dow logged a third straight day of gains and the S&P 500 moved back into the black for the year.
According to minutes of its October 27-28 meeting, the Federal Reserve policymakers agreed that the economy and labor market “could well” be strong enough to withstand a hike in interest rates in December. The officials said global troubles had eased and a delay could increase market uncertainty and undermine confidence in the economy.
The Fed also has expressed concern about persistently low inflation and said it must be reasonably confident inflation will return to the Fed’s 2% goal in the medium-term. That’s all it took and equities went into rally mode. Of course, we know that the Fed and not economic data determine market direction, as general macro data are showing anything but strength. Some analysts seem to think that the Fed needs to hike in order to save face; after all, you can only cry “wolf” so many times before you lose credibility.
Be that as it may, the question for us is whether the reboud of the last 3 days will provide enough momentum in order to break us out of the trading range in which we’ve been stuck for several weeks. With the Domestic TTI now having ventured again above its trend line by a fraction, after spending only 5 days below it, I will want to see more staying power accompanied by a stronger piercing of the line before issuing a new “Buy.” Stay tuned for more details.
All of our 10 ETFs in the Spotlight jumped higher with the leader being Healthcare (XLV) with a gain of +1.95%, while the Dividend ETF (DVY) lagged a little but gained +1.34%.