1. Moving the Markets
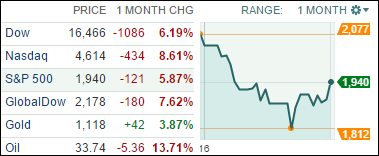
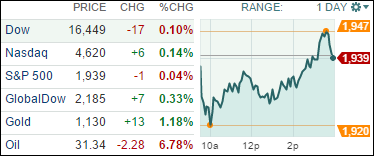
It did not look pretty at the opening with the major indexes taking a dive after Friday’s come back rally. Interesting to me was the break in correlation with oil prices, as oil got hammered at the tune of -6.78%, yet equities managed to dig themselves out of a hole and closed essentially unchanged.
If you thought there was some good news to function as a driver of this rebound, you would have been wrong. Domestic and global economic data were simply deplorable with China showing fresh signs of continued sluggishness and U.S. manufacturing data sinking into the basement. The latter was seen as “encouraging” in regards to the possibility of the Fed holding off further planned rate hikes.
Not to be outdone, Fed chairman Fischer, one of the hawkish types, commented that “the market’s expectations of barely any interest rate increases this year could turn out to be right.” Well, that was sufficient jawboning to talk the indexes out of their early doldrums and up we went. Obviously, whatever the Fed’s plans may be, their effects do supersede any economic realities for the time being.
Our 10 ETFs in the Spotlight were mixed with 5 of them rising and 5 of them falling. Leading to the upside was Consumer Discretionaries (XLY) with +0.61% while the US Financials (IYF) led to the downside with -0.47%.