1. Moving the Markets
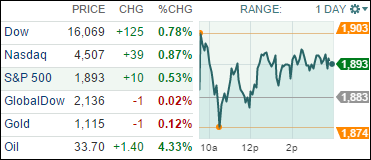
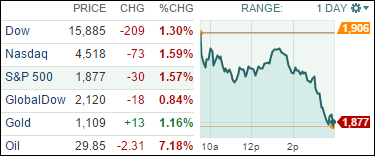
Stocks ended higher in choppy trading as oil prices rose for a third straight day and moved above $33 a barrel. The major indexes posted gains early as strong corporate earnings reports provided a boost which quickly evaporated before equities mounted another comeback.
In earnings news, Amazon (AMZN) missed Wall Street expectations, sending shares for a dive (-13%) in after-hours trading trading. The Seattle retailer reported $1 earnings per share on sales of $35.7 billion. The consensus earnings estimate has been $1.58 per share on revenue of $35.98 billion.
News in oil prices continued to grasp headline slots today, as the price of oil gained a whopping 4.33%. The bullish buy-in for oil futures came when swirling speculation that the Organization of the Petroleum Exporting Countries (OPEC) could slash production. Still, even if OPEC reduces production, macroeconomic concerns, such as the sluggish economy in China and the deteriorating situation in Brazil, are likely to continue to keep prices at low levels compared to recent yearly averages.
8 of our 10 ETFs in the Spotlight managed to close on the plus side with Consumer Staples (XLY) gaining +1.28%. The loser of the day was Healthcare (XLV), which got clobbered at the tune of -2.33%.
Let’s see if there is more fallout from the Amazon debacle tomorrow.
 Geopolitical risks can weigh heavily on capital markets, since investors that know less about China than the US are more concerned about the world’s second largest economy, said Leon Cooperman, CEO of Omega Advisors.