 Submitted by Peter Schiff via Euro Pacific Capital,
Stop me if you’ve heard this one before: A Fed official walks into a bar and says the economy is improving and rate hikes are appropriate. The patrons order another round to celebrate. Then disappointing data comes out, the high fives stop, and the Fed official ducks out the back…only to come back the next day saying the same thing. Anyone who pays even the smallest attention to the financial media has experienced versions of this joke dozens of times. Yet every time the gag gets underway, we raise our glasses and expect the punch line to be different. But it never is. Last week was just the latest re-telling.
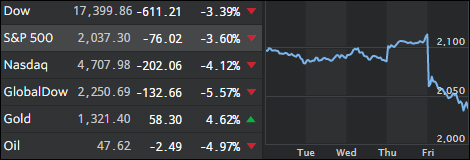
For nearly a month the Fed’s bullish statements stoked optimism on the economy and raised expectations, based particularly on the most recent FOMC minutes, for a summer rate hike. But these hopes were dashed by the May non-farm payroll report, which reported the creation of only 38,000 jobs in May, the worst monthly performance in six years, based on data from the Bureau of Labor Statistics (BLS). The number missed Wall Street’s estimate by a staggering 120,000 jobs. If not for the 37,000 downward revision reported for April (160,000 jobs down to 123,000), May could have shown a contraction. This would have constituted a major black eye to the Obama Administration’s favorite talking point that its policies have led to 75 months of continuous job gains. (6/3/16, Democratic Policy & Communications Center).