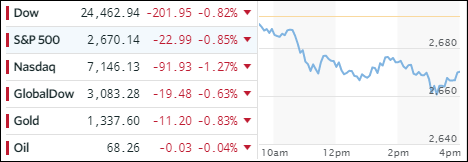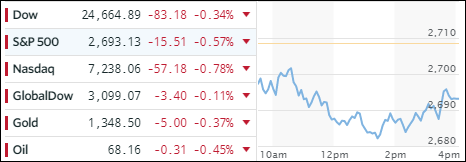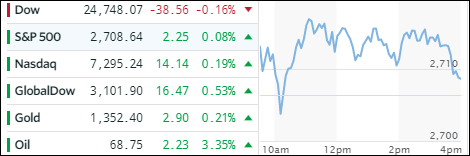
- Moving the markets
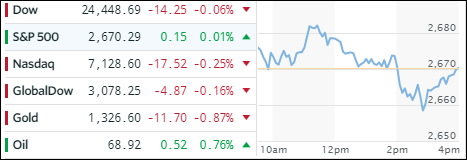
It was a mixed bag on the earnings front, as the latest reports can be best described as “so so,” which sent the major indexes initially higher but disappointment pulled the markets back below the unchanged line, with the exception of the S&P 500, which ended higher by a tiny fraction.
As I mentioned before, the 3% level of the 10-year bond yield will be a crucial point for equities. That became clear again today with weakness setting in as the yield surged towards that psychologically important marker but backed off prior to the end of the session saving equities from a sharper downturn. It now appears to be just a matter of time before we reach/cross that level which we last saw in January 2014.
Not helping matters was the fact that traders are now pricing in 4 interest rate hikes for 2018 rather than previously hoped for 3 increases.
The VIX pumped, dumped and pumped again helping the S&P 500 get back to its break-even point. Bank stocks tanked and FANGs stumbled, but the US Dollar (UUP) rallied for its 5th day in a row (crushing the shorts in the process) by gaining +0.63% and is now within spitting distance of conquering its 200-day M/A.