[Chart courtesy of MarketWatch.com]
- Moving the markets
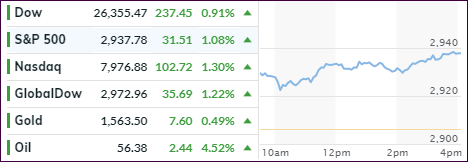
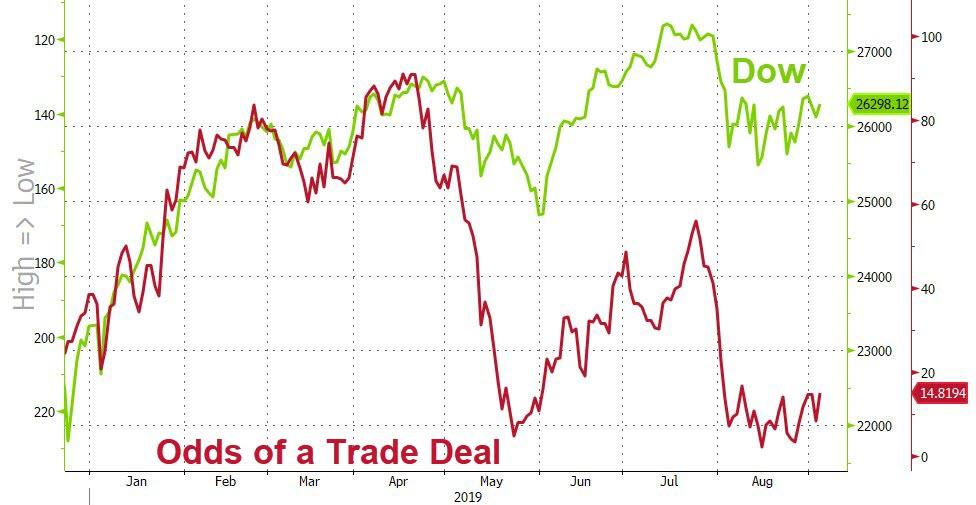
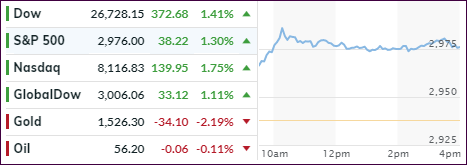
Just when you thought the trade deal was dead, news that US and Chinese officials declared a tentative resumption of tariff talks made the headlines, and off to the races we went with the computer algos pushing the indexes sharply higher.
Mind you that nothing worthwhile was accomplished. The warring parties simply agreed to talk again around “early October,” which these days is considered enough of a progress in the yearlong trade conflict for equities to surge.
To be fair, bullish sentiment was boosted by a couple of economic reports. First, ADP estimated that the private sector added some 195k jobs in August, which raised expectations for a good number tomorrow when the BLS releases its jobs report.
Second, despite recent surveys pointing to weakness in the manufacturing sector, the ISM rebounded, even though 60% of its components weakened. Nevertheless, for the day, the markets treated ‘good news’ as ‘good news’ with equities spiking.
That spike came in the face of sharply surging bond yields with the 30-year heading back above 2%, while the benchmark 10-year dashed 10 basis points to 1.58% before pulling back into the close.
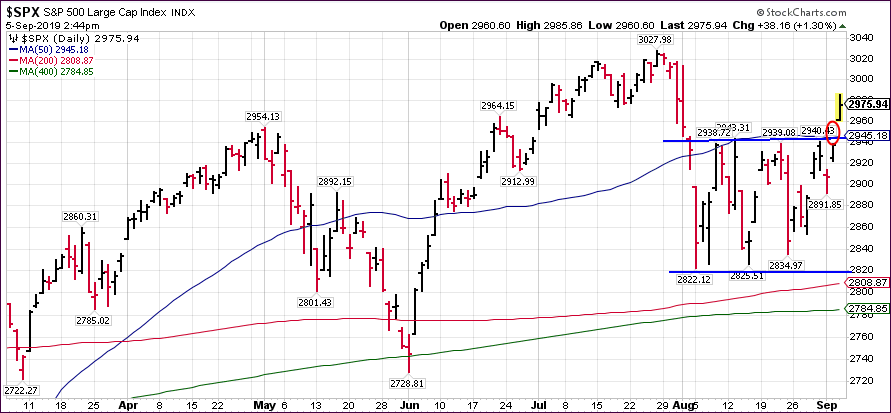
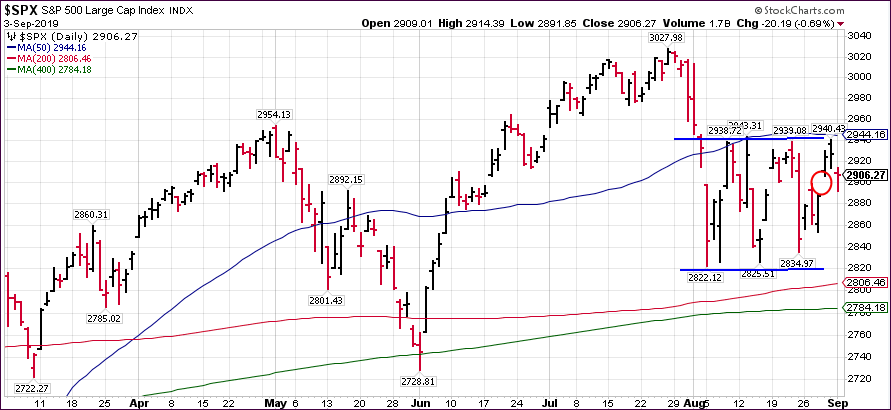
The S&P 500 broke out of its 5-week trading range (upper blue line) leaving a break-away gap behind (red circle). This gap will need to be closed at some point, so it’s questionable at this moment in time whether this breakout has enough legs to take out July’s highs.
This strong up move in the face of dramatically rising bond yields is unusual and, while this push benefited the S&P 500, it’s low volatility cousin SPLV, which I have preferred during this ‘Buy’ cycle, lagged and did not participate.
This means for this current cycle, which started on 2/13/19, the S&P 500 (SPY) has made up some ground and is now showing an +8.28% gain, which is still substantially behind the SPLV’s +12.89%.
Tomorrow’s jobs numbers are bound to affect market direction. The question is “which way?”
Read More