[Chart courtesy of MarketWatch.com]
- Moving the markets
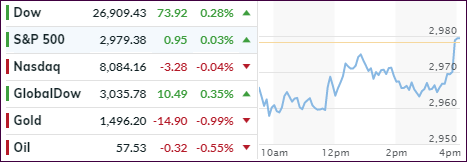
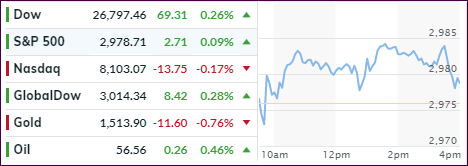
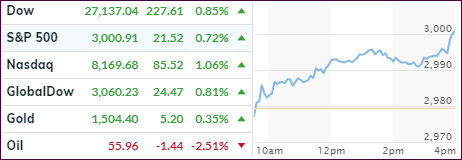
After a slow start, upward momentum picked up, and after a brief dip late in the session, the major indexes surged into the close led by the Nasdaq. The S&P 500 managed to barely reclaim its 3k marker, which it had surrendered at the beginning of August, while the Dow notched its 6th straight gain in a row.
The rotation from defensive and momentum driven stocks into cyclical and value-oriented ones continued. As I posted yesterday, during the recent spike in bond yields, traders had sold low volatility funds/ETFs to cash in on some outsized returns.
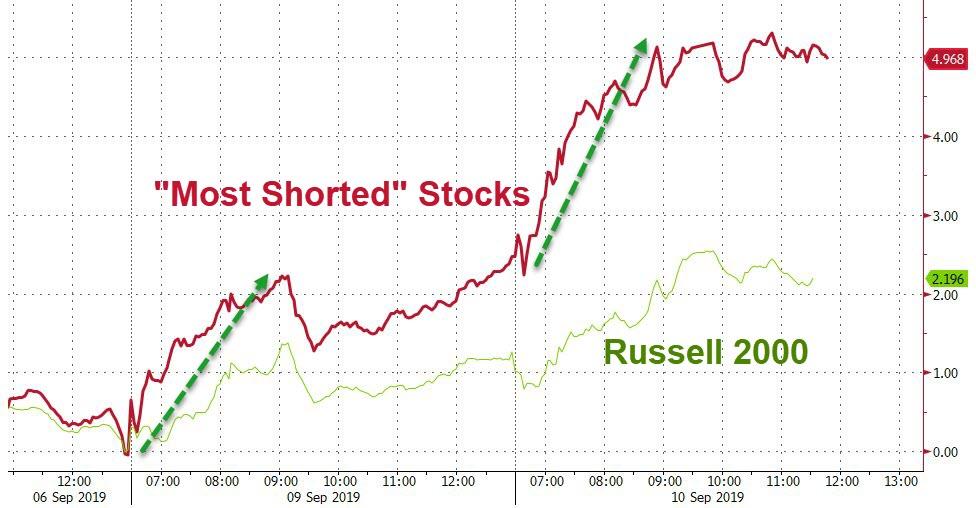
As a result, they lost a little bit of their luster, but in the case of SPLV, it still leads its more aggressive cousin SPY. It remains to be seen if the recent rally in SmallCaps can maintain current momentum, as its index, the Russell 2000, which has lagged the broader market for most of this year, is hovering more than 10% below its all-time high.
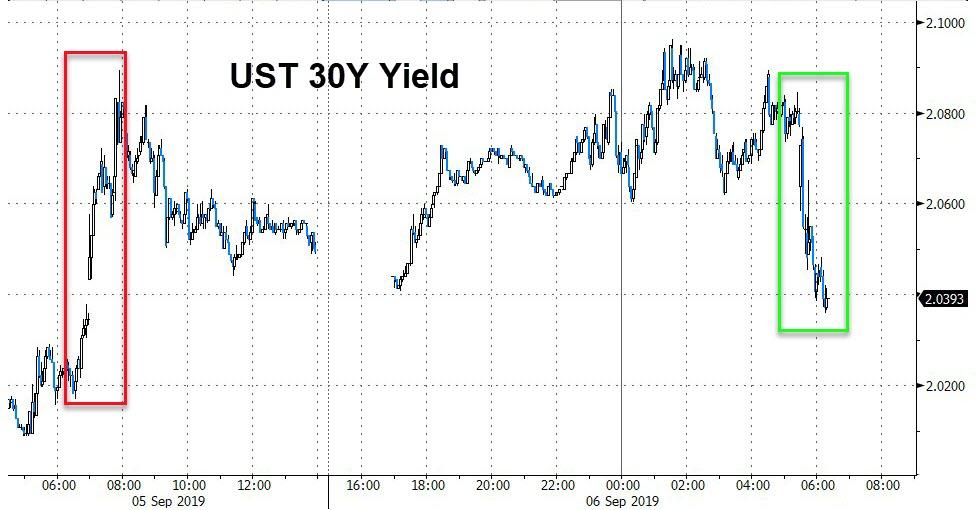
Meanwhile, bond yields headed higher again but a moderate pace with the 10-year adding 1.2 basis points to close at 1.746%.
Still, something seems out of whack in that equities should have reacted negatively to the sharp spike in bond yields over the past week. Rising yields indicate a strong economy, which on one hand is praised by the administration, while at the same time Trump is exerting tremendous pressure on the Fed (boneheads) to cut rates “to ZERO or less.” This makes me continue to ponder the question “why do we need rates at zero if the economy is so great?”
The assist for today’s push higher came again from the continued short-squeeze—up an incredible 12.75% in the last 6 days, according to ZH. This is the biggest short squeeze we’ve seen since August 2011, which explains why SmallCaps may have found a new life—at least for the moment, but how long can that last?
Read More