Torpedoing The Markets: Stocks And Bond Yields Tumble

Ulli Market Commentary Contact

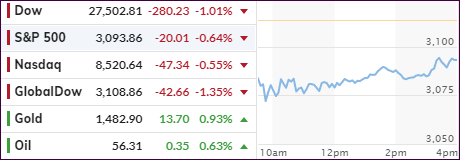
[Chart courtesy of MarketWatch.com]

  1. Moving the markets

As I pondered yesterday, the While House indeed fired the next salvo about the trade talks, but it was not what the markets expected. Stocks got hit hard when Trump announced that the idea of holding off on a US-China trade deal until after the 2020 election was appealing.

This undermined confidence and hope, by traders and computer algos alike, that a deal may be completed before new import tariffs are scheduled to be imposed by December 15.

At the same time, the US threatened 100% tariffs on some $2.4 billion in French goods over their digital tax, which has adversely affected US tech companies. Additionally, potential tariffs on countries like Brazil and Argentina were on the menu as well.

That seemed to conclude or end, at least for the time being, the game of endless headlines spouting the “a trade deal is close” theme designed to pump the markets to ever new highs.

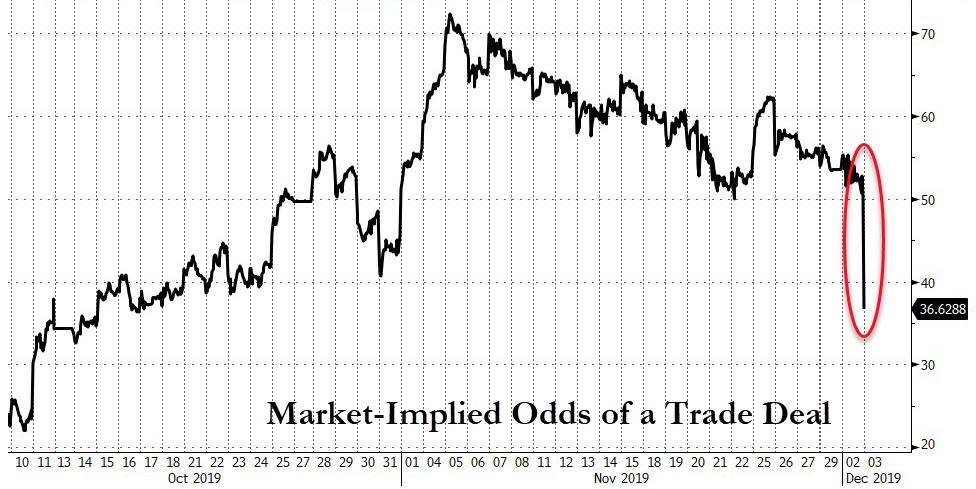
Especially the past two days have seen a sudden and dramatic reversal in sentiment, as a result of less-than-positive trade deal comments. The market implied odds of a trade deal have now plunged.

One of Nomura’s analysts summed it up this way:

“What forced self-reinforcing buying pressure on the way up is about to feed a vicious cycle of selling on the way down.”

That simply means some of the big players are chomping at the bit to short the markets, but only once a certain level has been hit. So, great news, such as the good old standby “a trade deal is close,” are sorely needed, in order to stem current downside momentum.

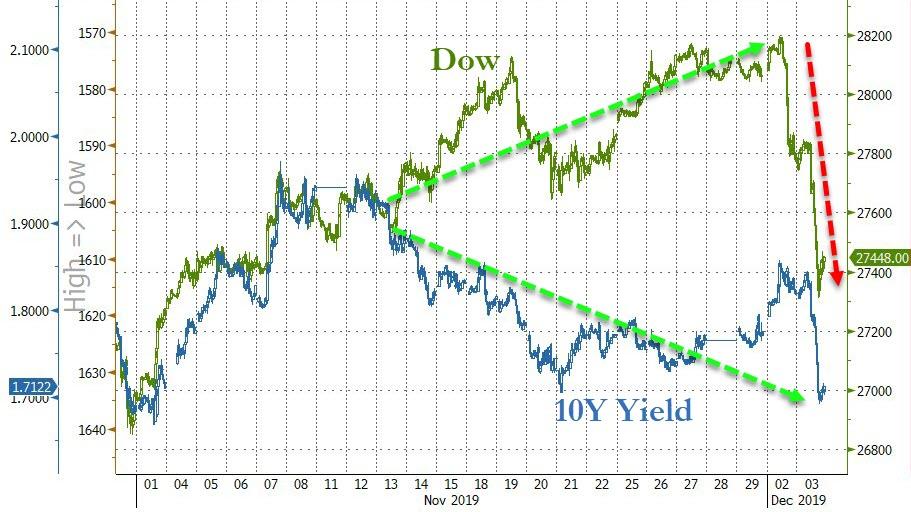
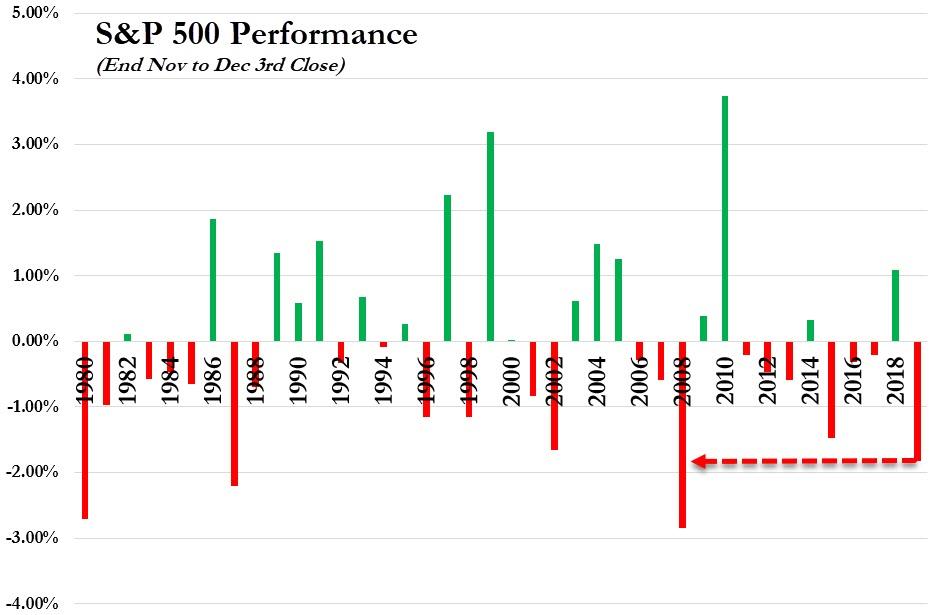
The 10-year bond yield collapsed 10.6 basis points to end at 1.72%. That’s a huge move, and it finally showed the discrepancy between bond yields and the Dow narrowing dramatically, as ZH pointed out with this chart. The S&P 500 had its worst start to a December since 2008. A tip of the hat goes to Bloomberg for this graph.

While we witnessed a slow crawl back from the day’s lows, it was not nearly enough to get back to even, as the possibility of a postponed trade deal was simply too much of a negative to overcome.

Read More
One-Two Punch Spooks Markets

Ulli Market Commentary Contact

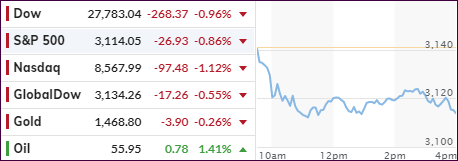
[Chart courtesy of MarketWatch.com]

  1. Moving the markets

Just as I posted the amazing fact last Wednesday that the S&P 500 had not corrected more than -0.5% in 35 days, it happened suddenly with the index shedding a moderate -0.86%.

The markets got hit right at the opening with a one-two punch in form of a worse-than-expected manufacturing report and mixed comments on the latest involving the US-China trade tensions.

The ISM manufacturing index dropped to 48.1% from 48.3% in October against expectations of an overly optimistic 49.2%. Readings below 50% indicate that business conditions are getting worse.

AS ZH reports, a quadruple whammy of not-awesome trade related comments gave an assist to the bears:

  • 0602ET *TRUMP TO RESTORE TARIFF ON STEEL SHIPPED FROM BRAZIL, ARGENTINA
  • 1035ET *TRUMP WILL INCREASE TARIFFS IF NO CHINA DEAL, ROSS TELLS FOX
  • 1200ET *TRUMP AIDE SAYS IT’S UP TO CHINA IF DEAL WILL BE MADE THIS YR
  • 1230ET *CHINA TO RELEASE ‘UNRELIABLE ENTITY LIST’: GLOBAL TIMES

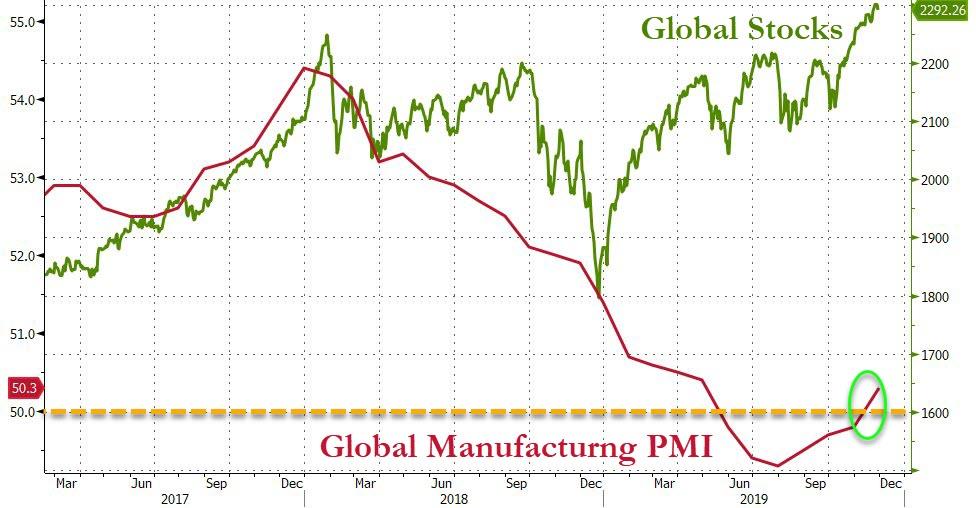
As a result, domestic equities were spanked and suffered their biggest drop in 6 weeks. As I commented on many occasions, not only does the global economy look murky at best, the US is not much better, as this chart shows.

On the other hand, the pullback was mild compared to the recent gains, and the bulls may have more to smile about, once the White House fires the next verbal salvo about how well phase 1 and 2 of the trade deal are progressing. Wait for it…

Read More

Weekly StatSheet For The ETF Tracker Newsletter – Updated Through 11/27/2019

Ulli ETF StatSheet Contact

ETF Data updated through Wednesday, November 27, 2019

Methodology/Use of this StatSheet:

1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.

2. Trend Tracking Indexes (TTIs)

Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use a 7.5% trailing stop loss on all positions in these categories to control downside risk.

3. All other investment arenas do not have a TTI and should be traded based on  the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending on your risk tolerance.

If you are unfamiliar with some of the terminology, please see Glossary of Terms and new subscriber information in section 9.     

1. DOMESTIC EQUITY ETFs: BUY — since 02/13/2019

Click on chart to enlarge

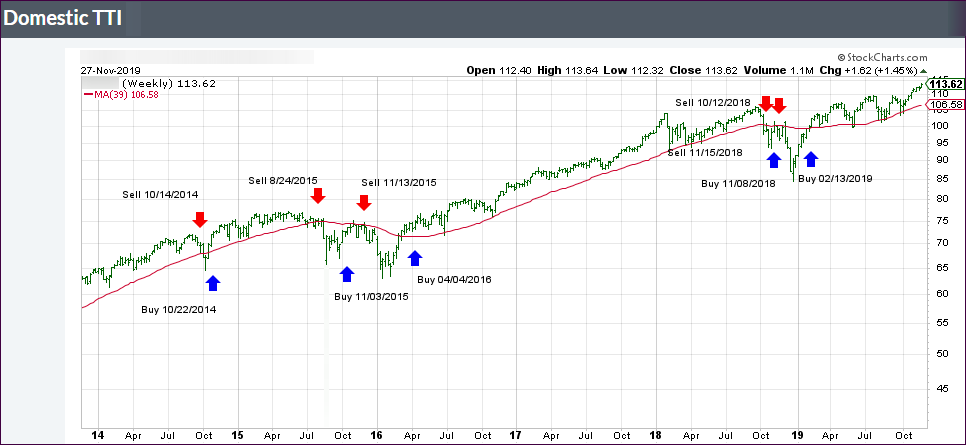
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is now positioned above its long-term trend line (red) by +6.87% after having generated a new Domestic “Buy” signal effective 2/13/19 as posted.

Read More

Bullish Sentiment Rocks

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

The markets continued to edge higher with the Dow and Nasdaq lagging early on but picking up steam mid-session to join the S&P 500 in green territory. Along the path, more records highs were set with positive economic data providing the necessary ammunition for the gains, which accelerated into the close.

There was little new information about the ongoing US-China trade war, so econ data had to carry the weight for this drive higher. We learned that Q3 GDP was unexpectedly revised up from 1.9% to 2.1% thanks in part to the Fed’s rate cutting efforts. At the same time, inflation remained subdued.

Home sales provide a mixed picture with new home sales being upwardly revised while pending home sales were showing a disappointing -1.78% MoM drop in October.

It’s I important to realize that over the past few weeks, since the dip in early October, markets have gone vertical with not even a 0.5% pullback in the S&P in 35 days. Obviously, the power to blast off like this came in the form of revving up the Fed’s printing presses (called ‘Not QE’) and Trump’s relentless tweets and comments of an imminent trade deal, which at this point does not look like it’s on the horizon. When reviewing the big picture, there are plenty of concerns that could have easily pulled down markets by 2-3%. But that did not happen—yet.

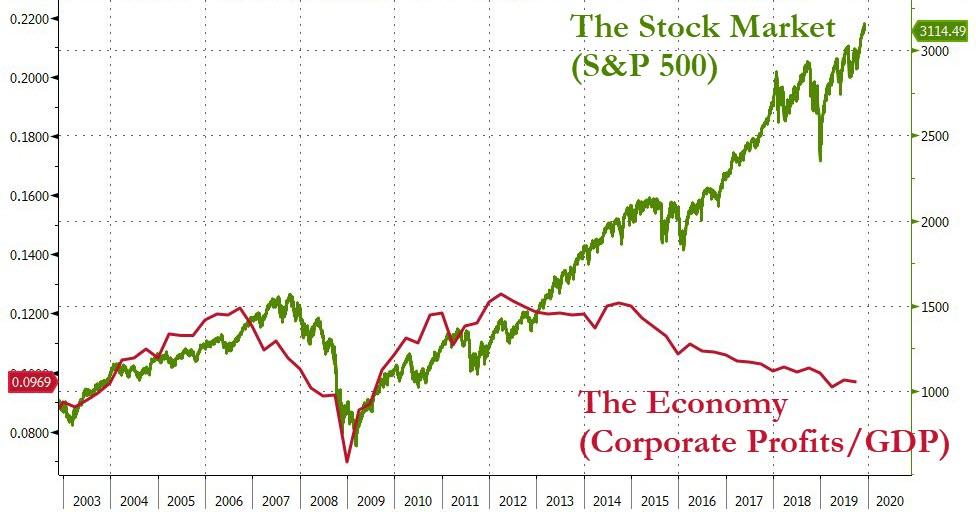
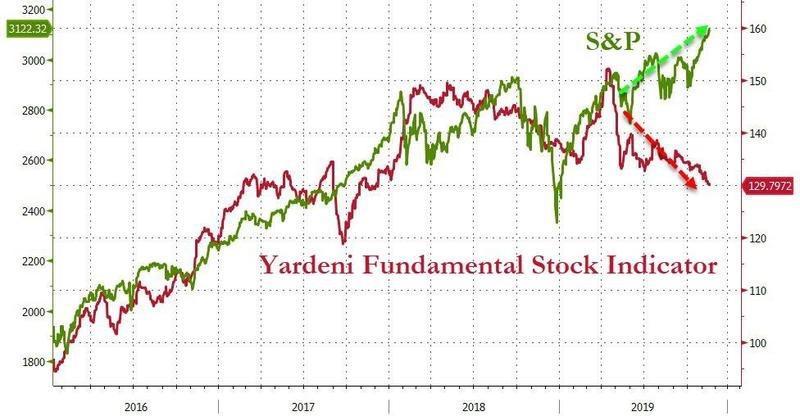
Which is why some analysts calling this extreme bullish optimism a “blow-off top.” This is especially concerning when considering that fundamentals are in total disconnect with stock market levels. Ed Yardeni’s indicator makes it all too obvious as to what could happen next.

The markets will be closed on Thanksgiving and are only open for short session on Friday. I won’t write a weekending report but will post the StatSheet later today.

I will resume regular posting on Monday. In the meantime, I wish you a relaxing and enjoyable Thanksgiving weekend.

Read More

Trade Optimism Keeps The Bullish Theme Alive

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

The major indexes managed to bounce back from early weakness and hovered safely above their respective unchanged lines bouncing in and out of record territory.

The fact that trade news said absolutely nothing new but mainly regurgitated the same old stuff as “we reached consensus on properly resolving relevant issues,” while the parties agreed to “stay in contact on the remaining points for a phase 1 trade deal.”

In other words, it’s amazing to me that the computer algos are still responding to the “artificial trade deal optimism,” which by now gets almost tiring to report on. One analyst wondered if this was just “a charade to keep stocks high, Trump happy, and China free to intervene in HK without angering the US president?”

Peak Prosperity’s Adam Taggert put it this way:

  • Fool us once, shame on you.
  • Fool us twice, shame on us.
  • Fool us daily for a year… what the hell is wrong with us???

Then Fed head Powell threw in some positives during remarks last night outlining an optimistic view of the US economy. He also signaled that low inflation would keep interest rates low and that home prices have been spurred by that policy.

In the end, for us trend trackers, the reason for the ramping of the markets is secondary, because we will stay on board for as long as we can. Once our directional indictors, or the trailing sell stops, give the signal to step aside, we will head for the safety of the sidelines.

Read More

Rosy Trade Outlook Powers Markets

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

The markets took another jump higher powered by some mega mergers and the good old stand-by, namely the trade talks. All last week’s concerns vanished over the weekend on China’s decision to issue guidelines and raise penalties for intellectual property theft.

This was immediately interpreted as a step in the right direction boosting the chances of a trade deal between the U.S. and China. Never mind that Reuters reported that a “phase 2” of the deal may not happen any time soon, if ever.

This was offset by a tweet by the Chinese mouthpiece, the Global Times, which said that the warring parties might be “very close” to reaching a “phase 1 deal,” according to the infamous and unknown experts close to the Chinese government.

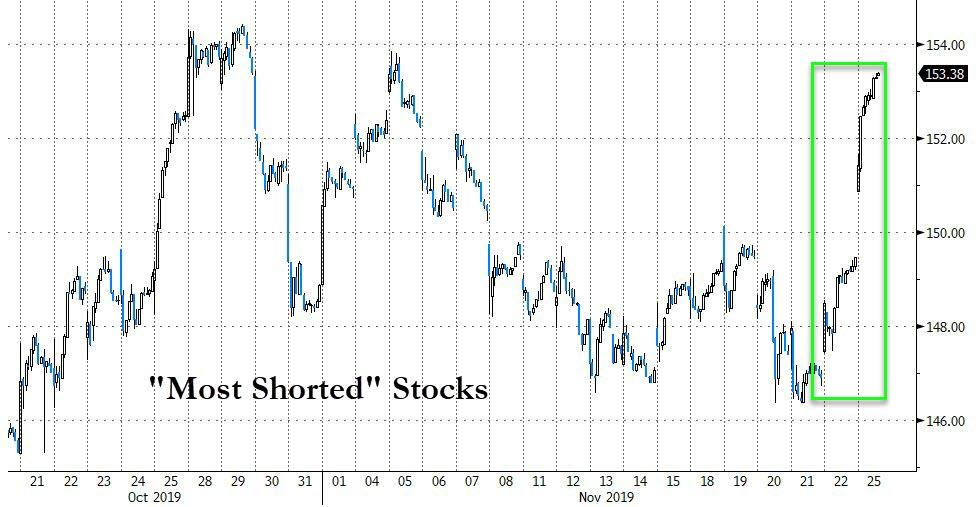
This got the rally started, and the major indexes never looked back with all three of them setting new intraday highs and/or surpassing previous records. As we’ve seen many time before, giving a huge assist was the biggest short squeeze we’ve seen since October which sent SmallCaps sharply higher.

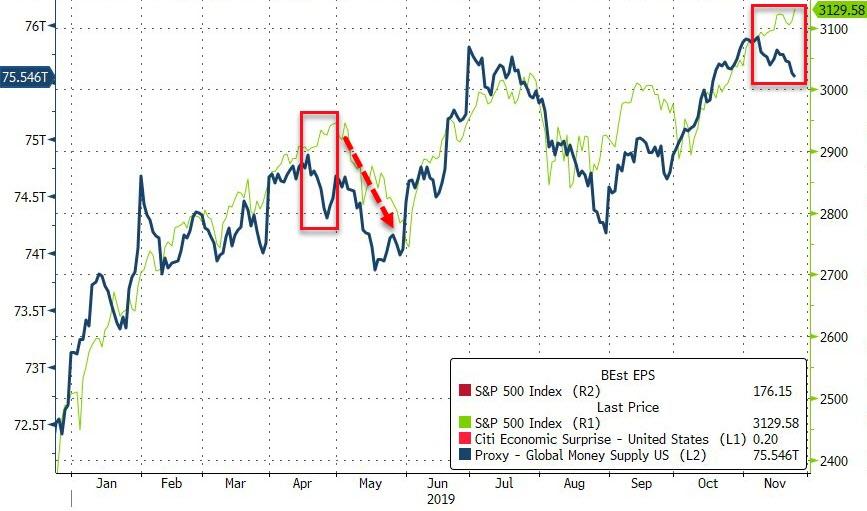
Surprisingly, and may be due to continued issues in the overnight lending market (repos), global liquidity started to reverse, just like it did in April. That brings up the question as to whether equities will follow. After all, as I have posted numerous times, the big driver of stocks is liquidity. If that continues in the direction this chart from Bloomberg indicates, we could see equity weakness ahead.

Read More