Below, please find the latest High-Volume ETF Cutline
report, which shows how far above or below their respective long-term trend
lines (39-week SMA) my currently tracked ETFs are positioned.
This report covers the HV ETF Master List from Thursday’s
StatSheet and includes 322 High Volume ETFs, defined as those with an average
daily volume of more than $5 million, of which currently 276 (last week 281)
are hovering in bullish territory. The yellow line separates those ETFs that
are positioned above their trend line (%M/A) from those that have dropped below
it.
In case you are not familiar
with some of the terminology used in the reports, please read the Glossary of Terms.
If you missed the original
post about the Cutline approach, you can read it here.
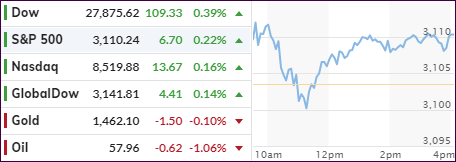
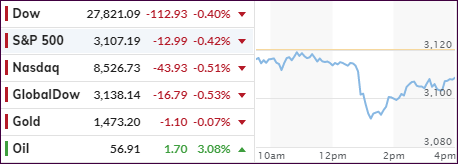
At
least for the S&P 500 and Nasdaq, today’s session was another one of the see-saw
variety, while the Dow managed to hover on the plus side the entire day.
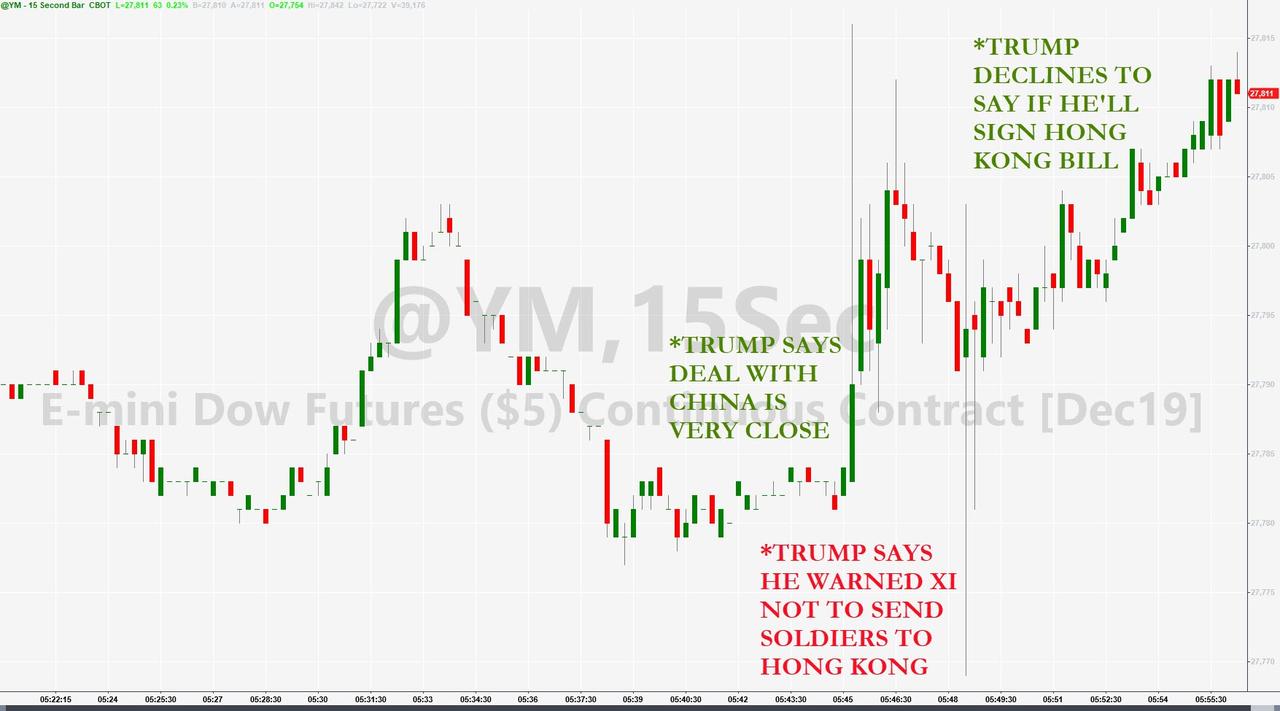
An
early pop followed by a drop set the early tone with Trump issuing what some
traders considered a “buy” signal by merely repeating the good old standby phrase,
namely that “a deal with China is close.”
This
was followed a threat when he “warned XI not to send soldiers to Hong Kong.”
But he made good on any fallout from his remark by pronouncing the he “declines
to say if he’ll sign Hon Kong bill.”
ZH
charted these market
moving effects, which simply demonstrates that the computer algos reacted
exactly as expected.
Of
course, the ongoing trade soap opera would not be complete without China’s Xi joining
the fray and chiming in with things like “Beijing wants to work for a trade
deal with the U.S. but is not afraid to ‘fight back,’” and that he holds a “positive
attitude” towards the talks, but that a deal requires “mutual respect
and equality.”
So,
the jawboning goes on without any concrete progress being made. Surprisingly,
the markets reacted positive with the indexes scoring a green close for the first
time in four trading days. However, the setback for the week was minor -0.32% for
the S&P 500—hardly a correction worth mentioning.
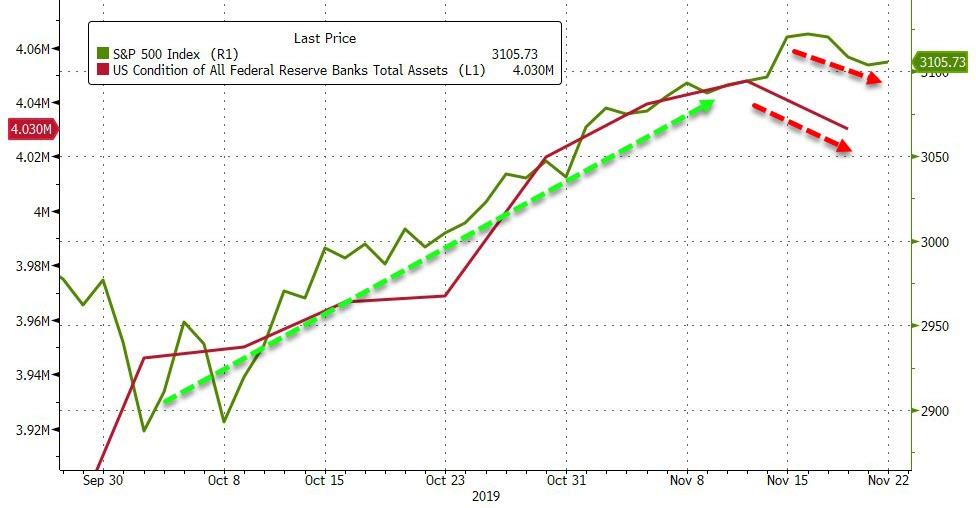
However,
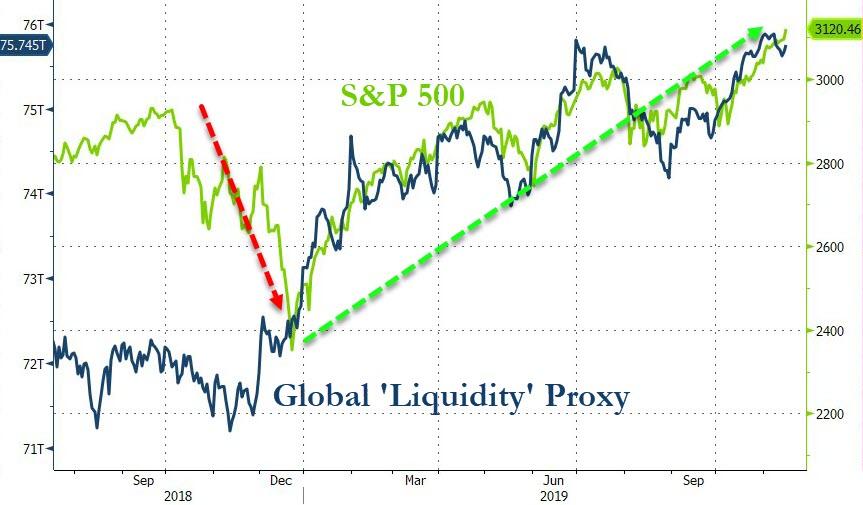
ZH pointed to
this chart showing that the real reason or this week’s “pullback” was simply
the unexpected contraction of the Fed’s balance sheet (Source: Bloomberg). Hard
to argue with the conclusion.
The
markets have been very turbulent over the past 2 years and many readers have
emailed me to clarify a variety of questions about the ever-changing investment
environment. A good way to enhance your understanding is this U-tube video,
during which host Greg Hunter goes one on one with author and analysist John
Rubino. It’s 30 minutes well spent.
ETF Data
updated through Thursday, November 21, 2019
Methodology/Use of this StatSheet:
1. From the universe of over 1,800 ETFs, I have selected only those with a
trading volume of over $5 million per day (HV ETFs), so that liquidity and a
small bid/ask spread are assured.
2. Trend Tracking Indexes (TTIs)
Buy or Sell decisions for Domestic and International ETFs (section 1 and
2), are made based on the respective TTI and its position either above or below
its long-term M/A (Moving Average). A crossing of the trend line from below
accompanied by some staying power above constitutes a “Buy” signal. Conversely,
a clear break below the line constitutes a “Sell” signal. Additionally, I use a
7.5% trailing stop loss on all positions in these categories to control
downside risk.
3. All other investment arenas do not have a TTI and should be traded
based on the position of the individual
ETF relative to its own respective trend line (%M/A). That’s why those signals
are referred to as a “Selective Buy.” In other words, if an ETF crosses its own
trendline to the upside, a “Buy” signal is generated. Since these areas tend to
be more volatile, I recommend a wider trailing sell stop of 7.5% -10% depending
on your risk tolerance.
If you are unfamiliar with some of the terminology, please see Glossary of Termsand new subscriber information in section 9.
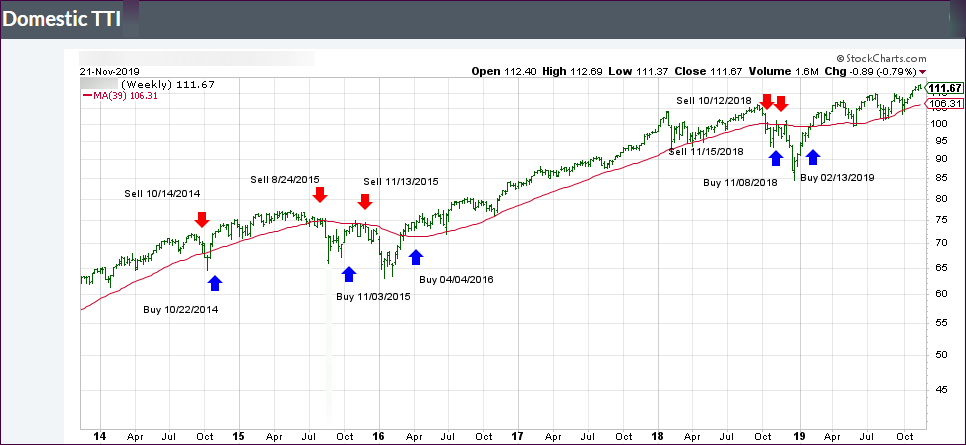
1. DOMESTIC EQUITY ETFs: BUY
— since 02/13/2019
Click on chart to enlarge
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) is now positioned above its long-term trend line (red) by +5.26% after having generated a new Domestic “Buy” signal effective 2/13/19 as posted.
Softness in the markets prevailed for the third day, as a
bunch trade news volleys made their way back and forth and kept the major indexes
in limbo. An early drop shifted into rebound mode, an occurrence we’ve seen
regularly in the recent past, but it fell short of conquering the unchanged
lines.
Even though we closed slightly in the red, the continued resilience
of the market, to shake off bad news and remain at ridiculously elevated levels,
is remarkable. The see-saw moves over the past few days continued with utter abundance,
with the market moving headlines being clearly recognizable in this
chart.
With a record “trade deal on/trade off” reversals being the
new norm, it now included “unnamed sources” saying that “the US would be
willing to delay the December 15 tariffs, even if there is no trade deal,” but
that the pro-Hong Kong human rights bill passed by Congress could be a major
obstacle to any agreements.
Despite equity weakness, bond yields rose, which hurt
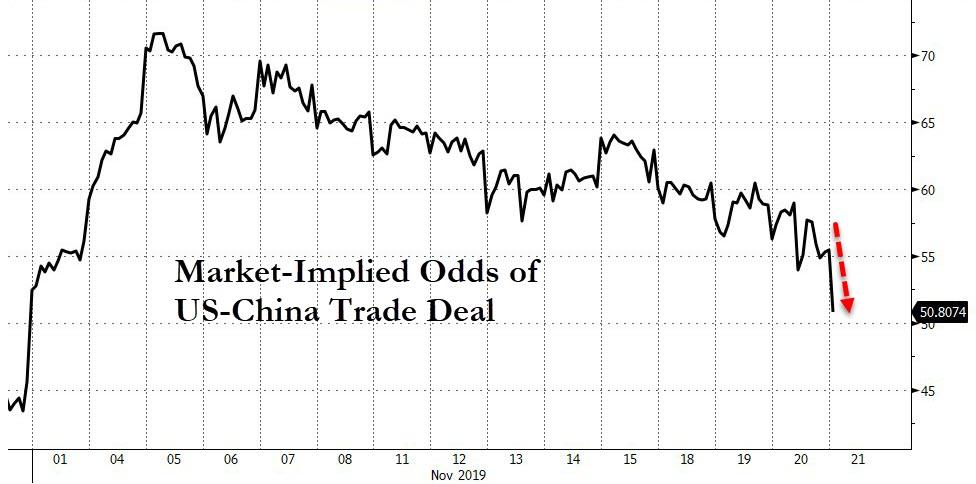
bond prices and low volatility ETFs the most. The odds
of a US-China trade deal plunged, which means, if those don’t reverse, a new
driver will be needed to keep stocks on their northerly path.
The markets started the session by meandering slightly below
their respective unchanged lines when a sudden dive took the starch out of any
existing support. As I posted yesterday, a new headline about how close the latest
trade deal might be was sure to be on deck.
Well, we got trade headlines, but they revealed exactly the
opposite of what was expected, namely that phase one of this much jawboned about
event may not be completed this year. To stoke the fire of discontent even
more, China condemned a US Senate resolution supporting human rights in Hong
Kong.
Then it was the US’s turn to emphasize that “rolling back
tariffs for a deal that fails to address core intellectual property and
technology transfer issues will not be seen as good deal for the US.” That
was the final nail in the coffin to seal the downward
trend of equities.
But the mocking continued, as the editor of China’s Global
Times, after his earlier threat that “China wants a deal but is prepared for
the worst-case scenario, a prolonged trade war,” proceeded to taunt the US farmers with “wait
for a trade deal before getting bigger tractors.” You just can’t make this
up, and it makes me wonder how long this soap opera will go on.
Despite all this negativity, a late day rebound lifted the
indexes off their lows but fell short of moving them into the green. Nevertheless,
the markets are showing tremendous resilience, especially when you consider
that the Dow has been down 2 days in a row for its biggest drop in 6 weeks, and
this very drop amounted to less than 1%.
The S&P 500 has not had 1% correction in 28 days and,
as ZH points out, it went 36 days in June/July without one. Of course, as I have
pointed out on many occasion, the main driver that controls market direction is
global liquidity, which this
chart (Source: Bloomberg) clearly demonstrates.
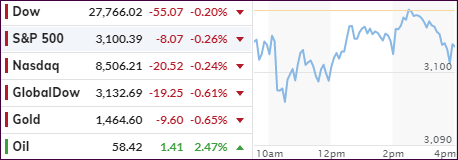
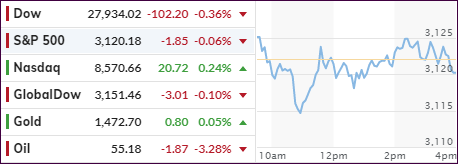
Today we experienced a market condition, which we have
not seen in a while, namely not just an intra-day sell off, but also a red
close of more than the occasional shocking -0.01%, at least for the Dow. Of
course, I am being facetious here, but the usual end of the day ramp saved the
S&P 500 and Nasdaq.
However, given the relentless march higher, today’s partial
retreat was more than overdue. A slightly positive opening gave way to a gentle
slide into the red zone, but the bullish theme remained strong enough to assist
in the recovery.
Not helping matters were disappointing earnings results
and the good old standby excuse that a US-China deal has become questionable.
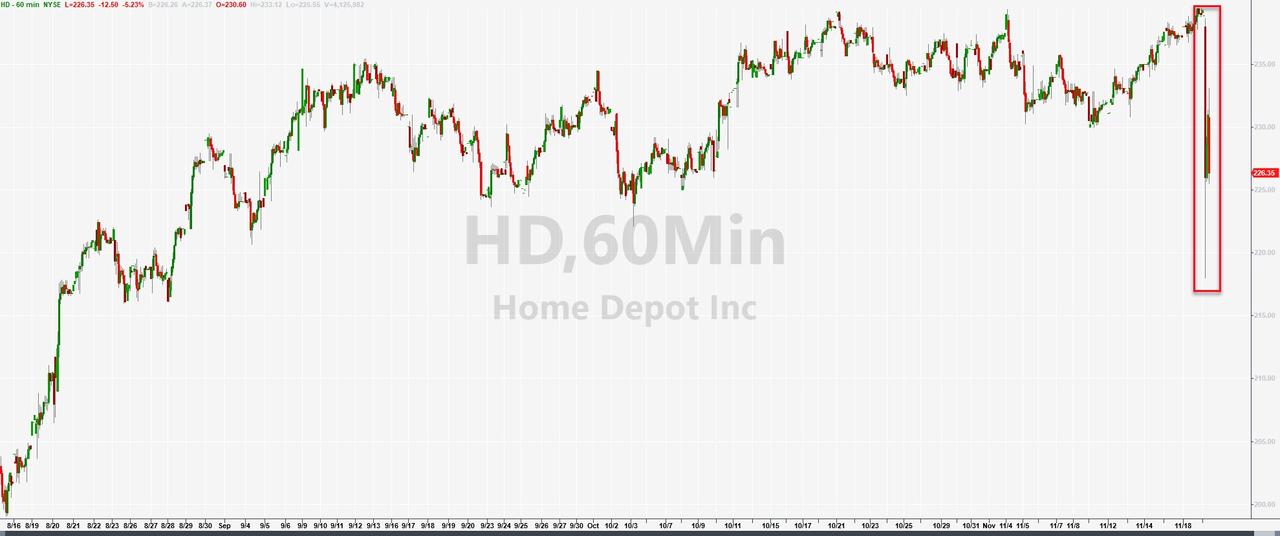
Home Depot’s shares took
a hit with the company not just posting a miss in Q3 sales,
but more importantly, they slashed their full-year sales guidance as well. Ouch!
However, offsetting that poor report was a rise in US home building and permits
for future construction.
Clearly, the economy, despite being hyped up, is mixed
bag at best. Even the Fed’s John Williams seems to agree as he posted things
like “the economy is clearly facing several challenges, primarily from
overseas, but the three rate cuts since July should help sustain growth,” on
which he elaborated further with the US “facing headwinds from slower global
growth.”
In the end, nothing much was gained or lost, except the
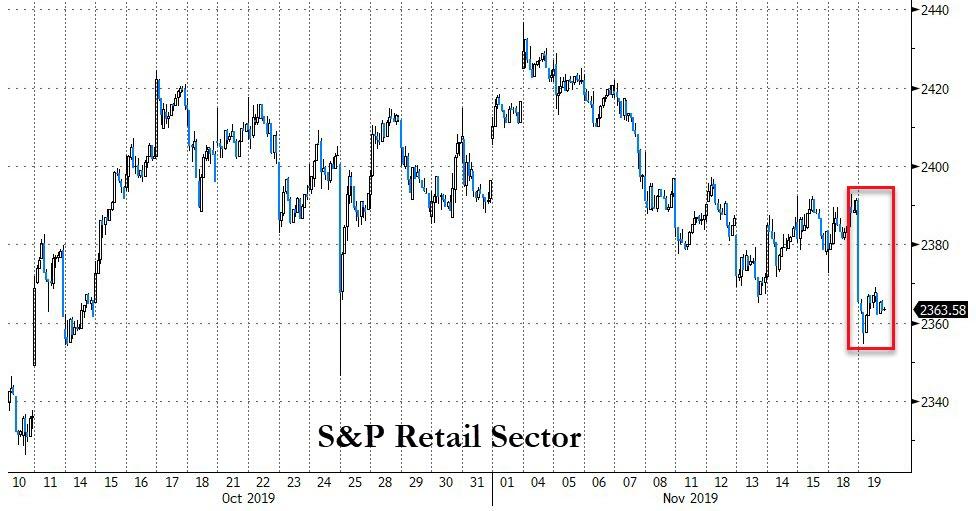
Nasdaq remained on the plus side all day and added +0.24%. At least the tech arena
showed signs of life in the face of a sinking retail
sector, where the stocks of Home Depot and Kohls were sent reeling.
With no obvious driver to help the markets today, I imagine
that we will see a new rollout of “the trade deal is close” headlines
latest by tomorrow, in order to pump stocks further into record territory.