ETF Tracker Newsletter For December 10, 2021

Ulli ETF Tracker Contact

ETF Tracker StatSheet          

You can view the latest version here.

PUMPING INTO THE WEEKEND
[Chart courtesy of MarketWatch.com]

  1. Moving the markets

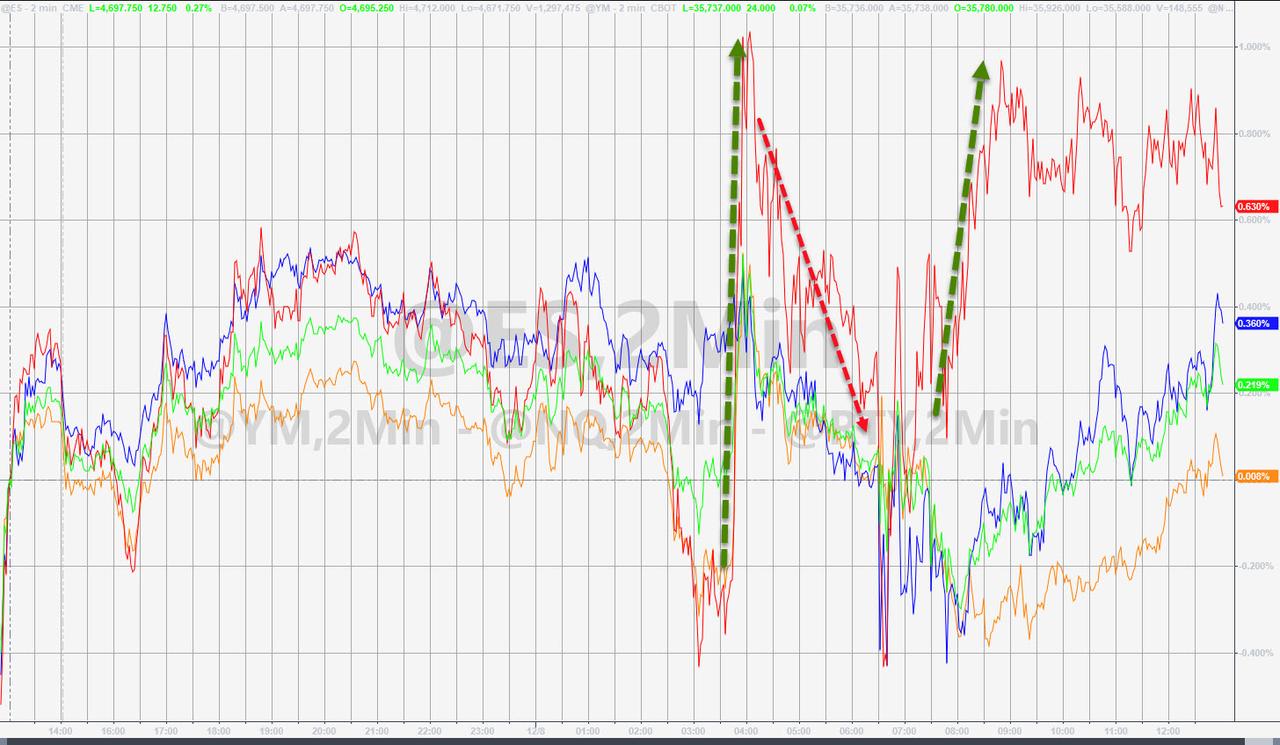
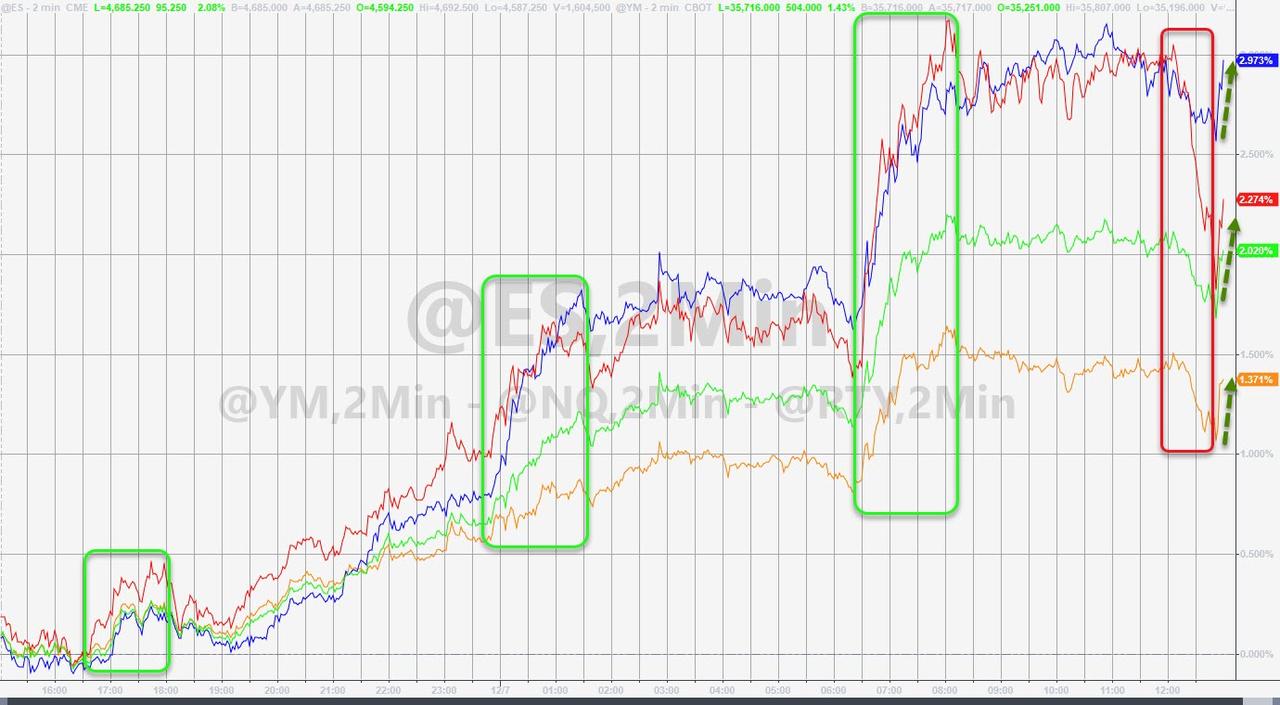
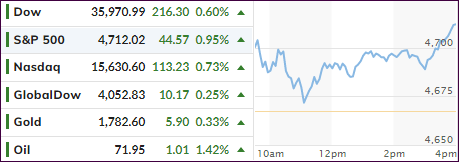
Aimless meandering, even though above the unchanged line, turned into a late session ramp with the major indexes pushing higher, led by the S&P 500, with all three of them ending the day with solid gains.

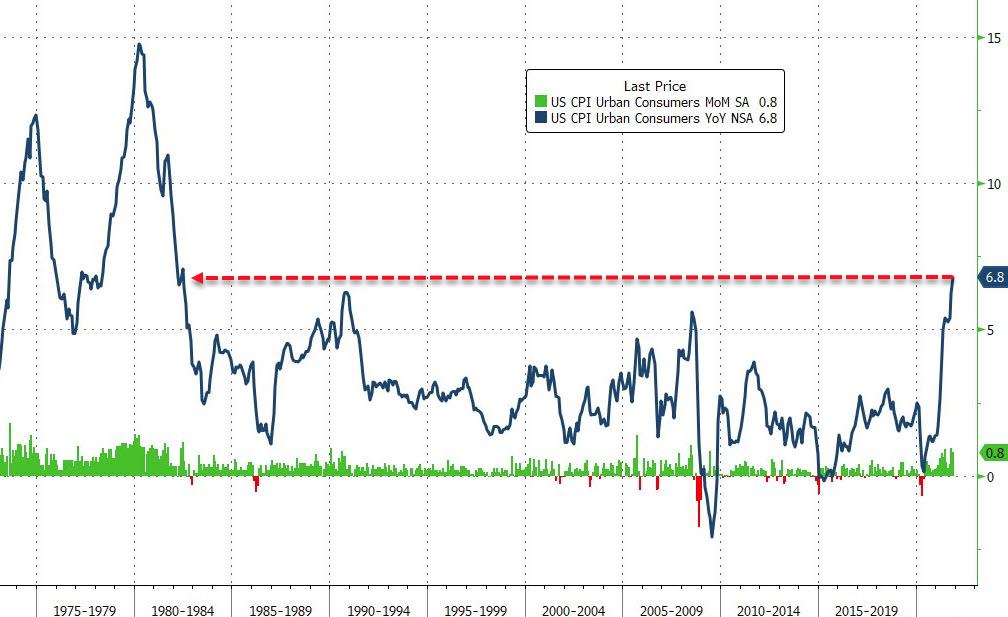
Despite a terrible CPI report, the S&P 500 managed to score another record high and posted its best week since February. Yes, inflation hit a 39-year high, as prices climbed at their fastest pace since 1982.

As ZeroHedge noted, this morning’s CPI, after having surged faster than expected in 7 of the last 8 months, is the last big release ahead of next Wednesday’s Fed decision on interest rates and possibly an increase in tapering.

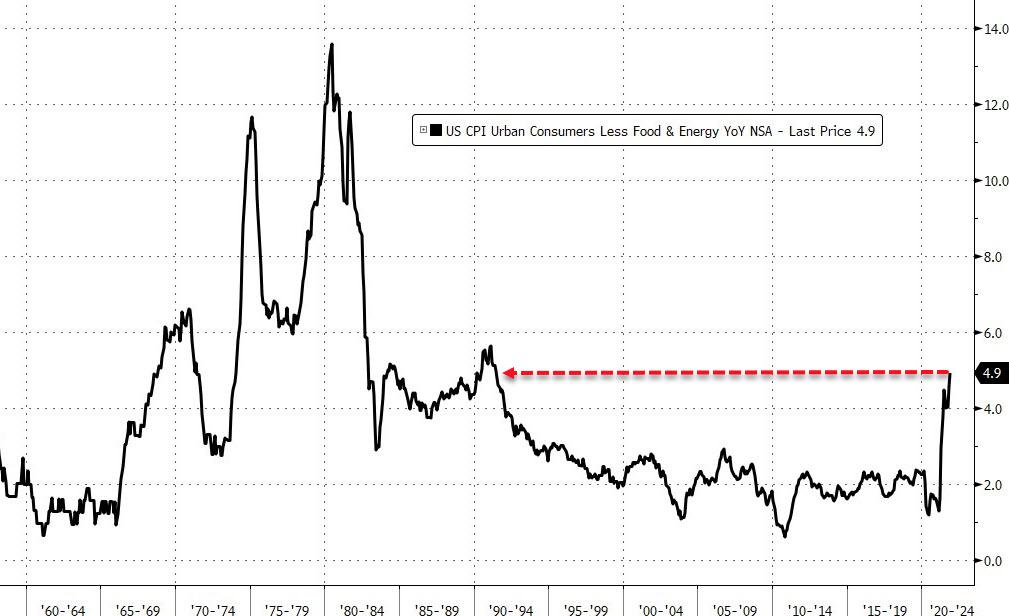
The Consumer Price Index printed at +6.8% YoY, which was a tad better than expectations of 6.9%. The Core CPI, without food and energy, still rose at a 4.9% clip, its highest since 1991.

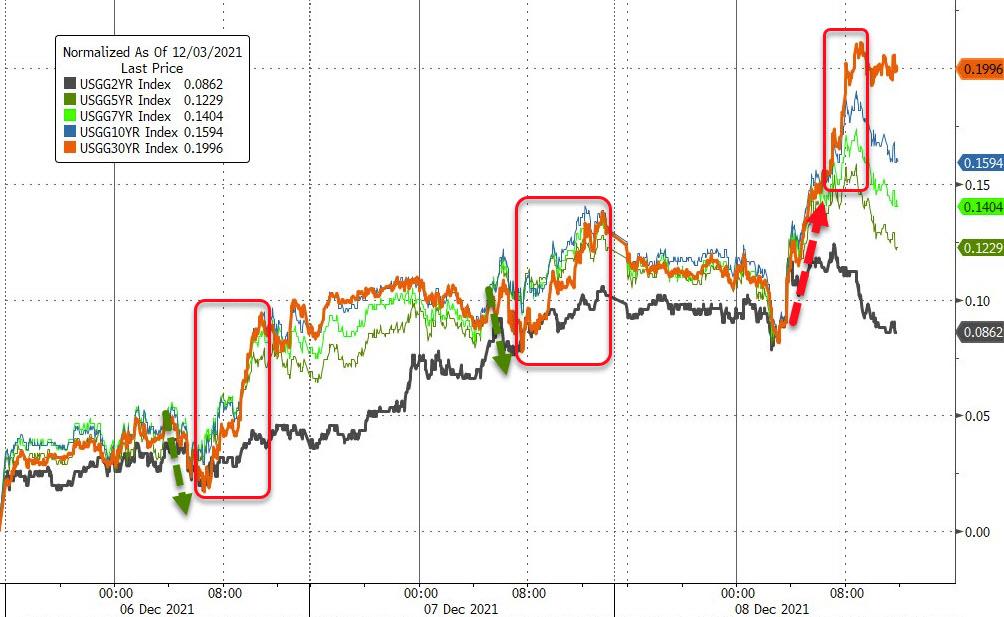
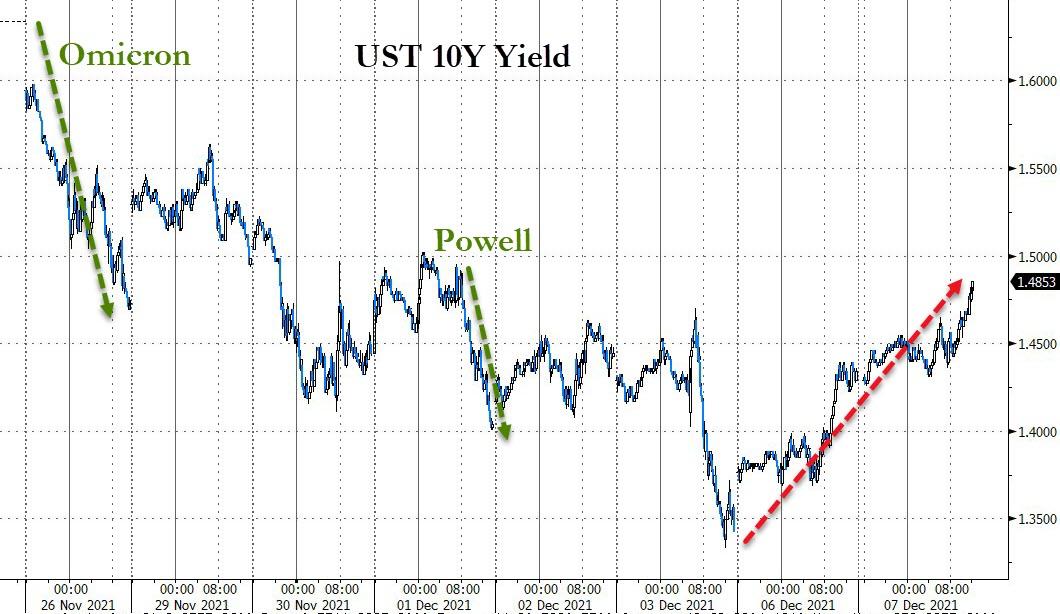
Bond yields swung wildly with the 10-year almost touching 1.45% at the low end and 1.52% at the high end, but it settled at 1.485%, just about below the unchanged line.

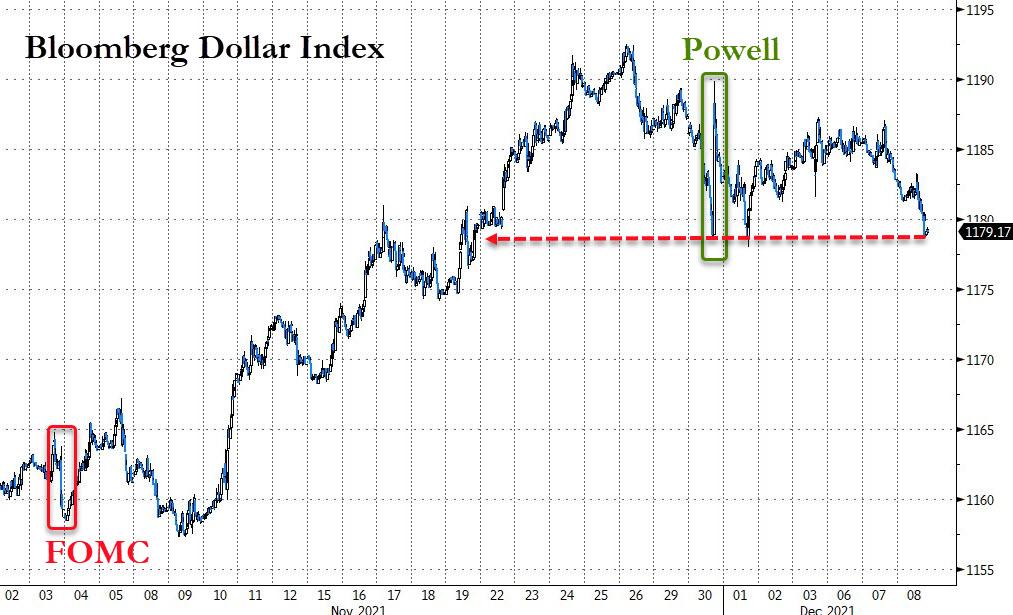
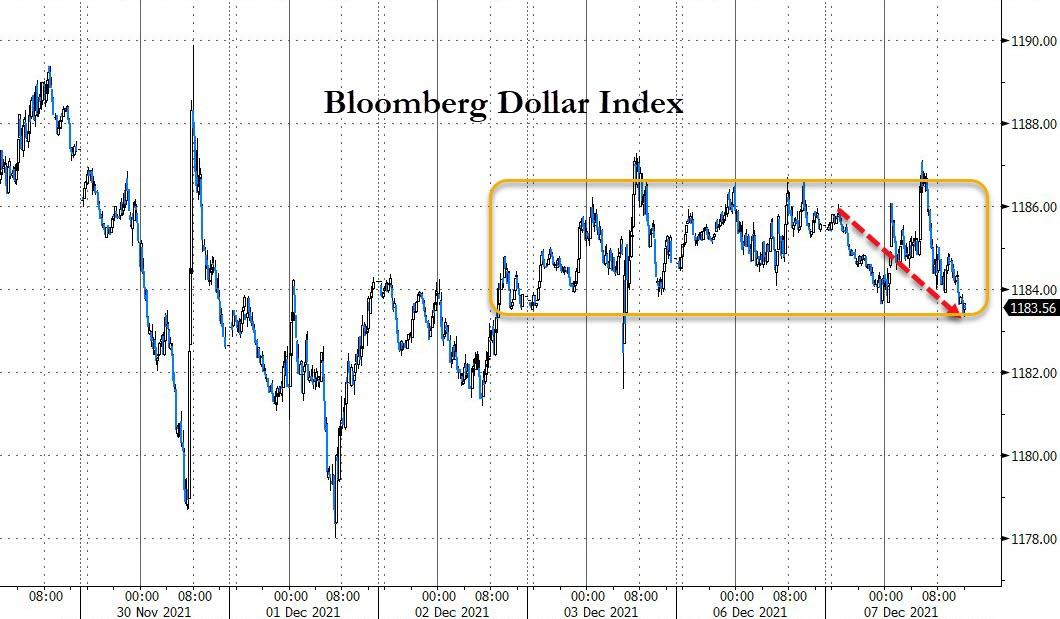
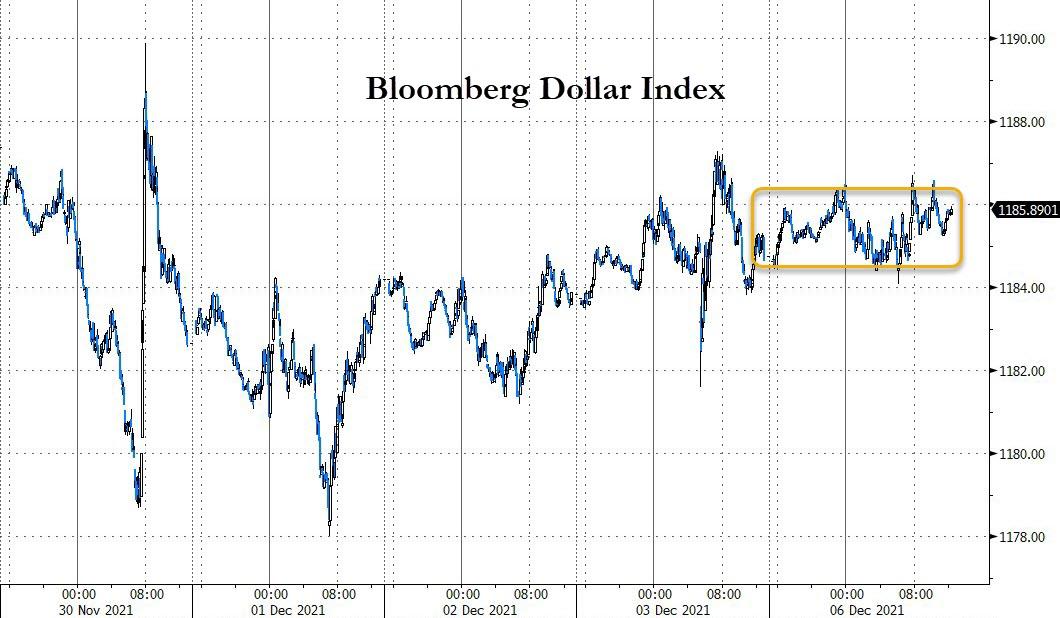
The US Dollar followed a similar pattern but ended close to its lowest level of the session and gave back 0.22%.

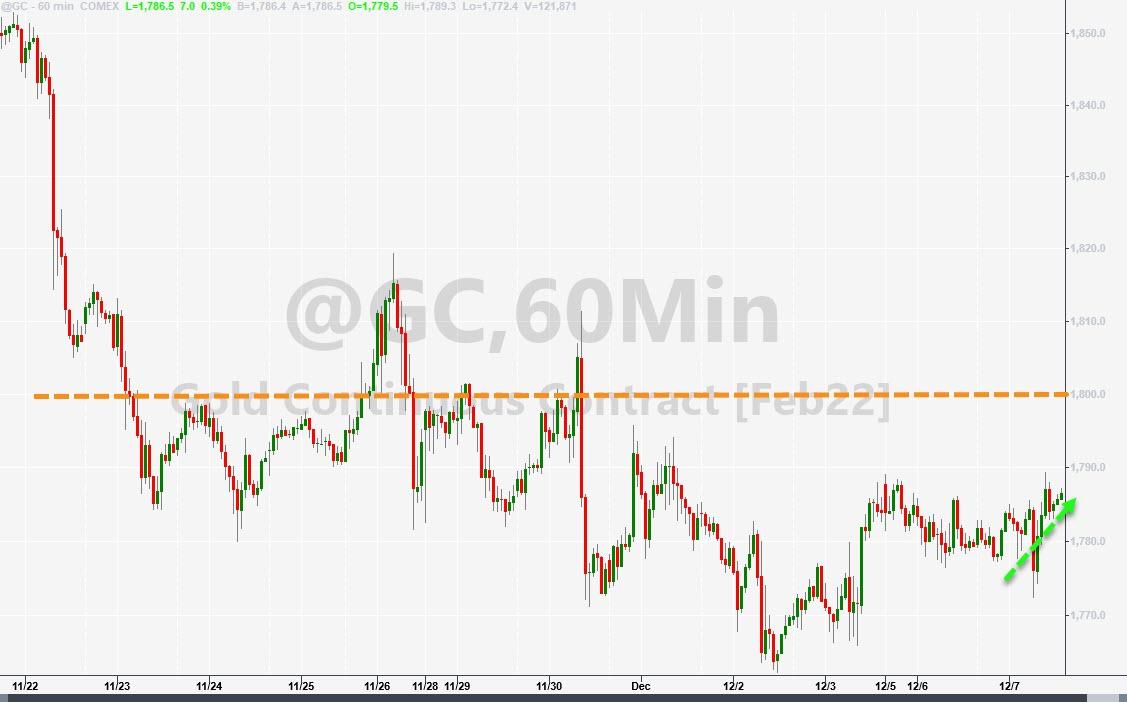
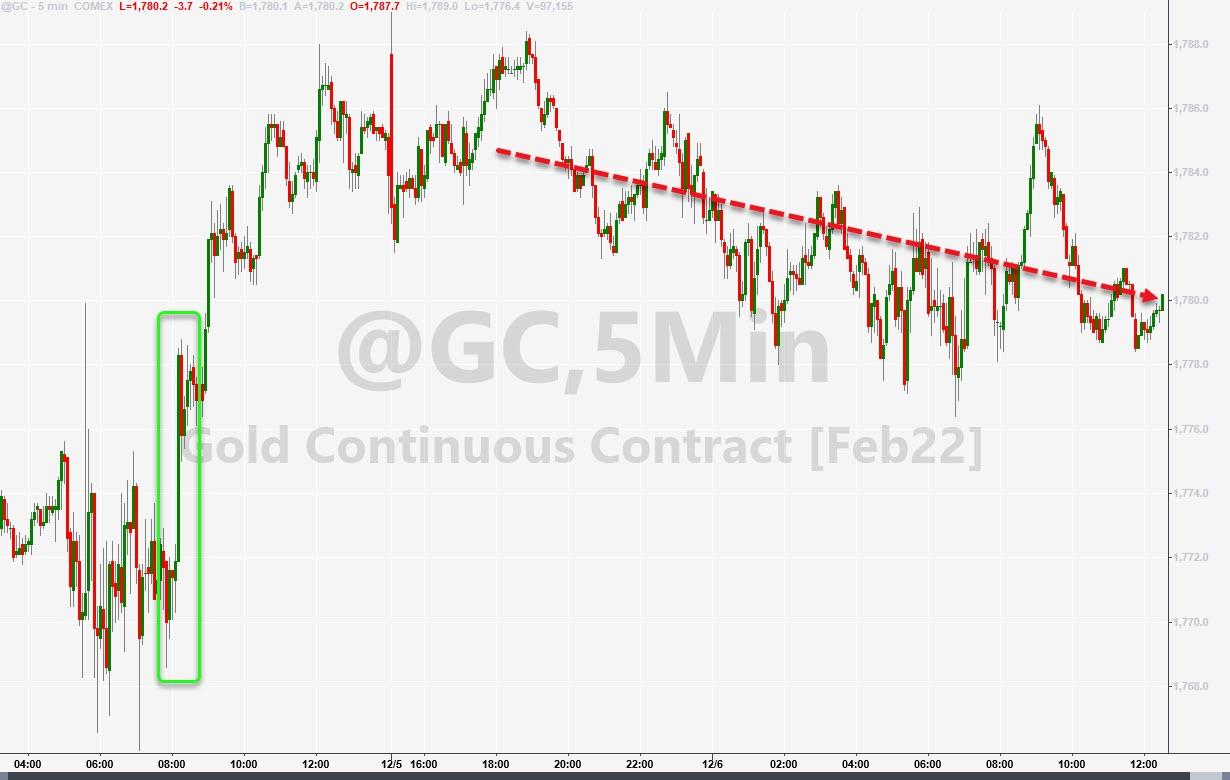
Gold, after some early weakness, suddenly dashed higher mid-day and gained 0.34%. However, the move was not enough for the precious metal to recapture its $1,800 level.

As I posted before, during early periods of rising inflation, stock markets will benefit but, once this process accelerates causing bond yields to spike out of control, markets will collapse.

That’s why we must be prepared to execute our exit strategy, whenever our Trend Tracking Index (TTI) signals that critical moment in time.

Read More
Weekly StatSheet For The ETF Tracker Newsletter – Updated Through 12/09/2021

Ulli ETF StatSheet Contact

ETF Data updated through Thursday, December 9, 2021

Methodology/Use of this StatSheet:

1. From the universe of over 1,800 ETFs, I have selected only those with a trading volume of over $5 million per day (HV ETFs), so that liquidity and a small bid/ask spread are assured.

2. Trend Tracking Indexes (TTIs)

Buy or Sell decisions for Domestic and International ETFs (section 1 and 2), are made based on the respective TTI and its position either above or below its long-term M/A (Moving Average). A crossing of the trend line from below accompanied by some staying power above constitutes a “Buy” signal. Conversely, a clear break below the line constitutes a “Sell” signal. Additionally, I use an 8% trailing stop loss on all positions in these categories to control downside risk.

3. All other investment arenas do not have a TTI and should be traded based on the position of the individual ETF relative to its own respective trend line (%M/A). That’s why those signals are referred to as a “Selective Buy.” In other words, if an ETF crosses its own trendline to the upside, a “Buy” signal is generated. Since these areas tend to be more volatile, I recommend a wider trailing sell stop of 8%-10% depending on your risk tolerance.

If you are unfamiliar with some of the terminology, please see Glossary of Terms and new subscriber information in section 9.     

1. DOMESTIC EQUITY ETFs: BUY — since 07/22/2020

Click on chart to enlarge

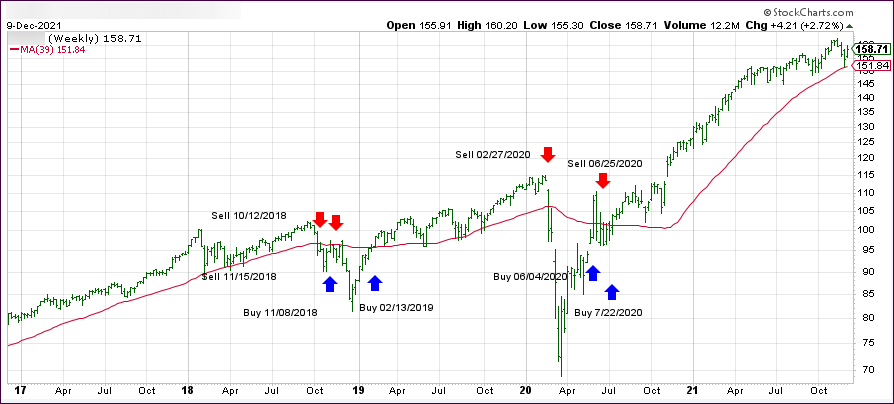
Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in the above chart) has now rallied above its long-term trend line (red) by +4.86% and remains in “BUY” mode as posted.

Read More

Keeping The Bullish Theme Alive

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

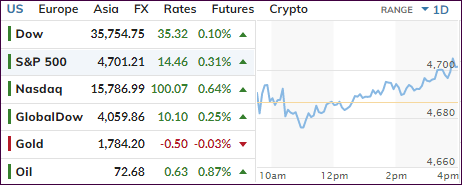
Despite some early wobbling, with the major indexes dipping below their respective unchanged lines, dip buyers stepped in late in the session and drove equites to a green close. The rebound effort was led by the Nasdaq with a 0.64% gain, while the Dow lagged but managed to advance by a tiny 0.10%.

The positive mood was the result of traders viewing the influence of the Omicron variant not as frightening as originally thought, thereby crossing one item off the worry list—that is for the time being.

Aiding the late afternoon rebound were announcements by Pfizer and BioNTech saying that “three doses of their vaccine are effective at neutralizing the omicron variant,” according to their own lab tests. They also pronounced that taking two doses still protect against the disease.

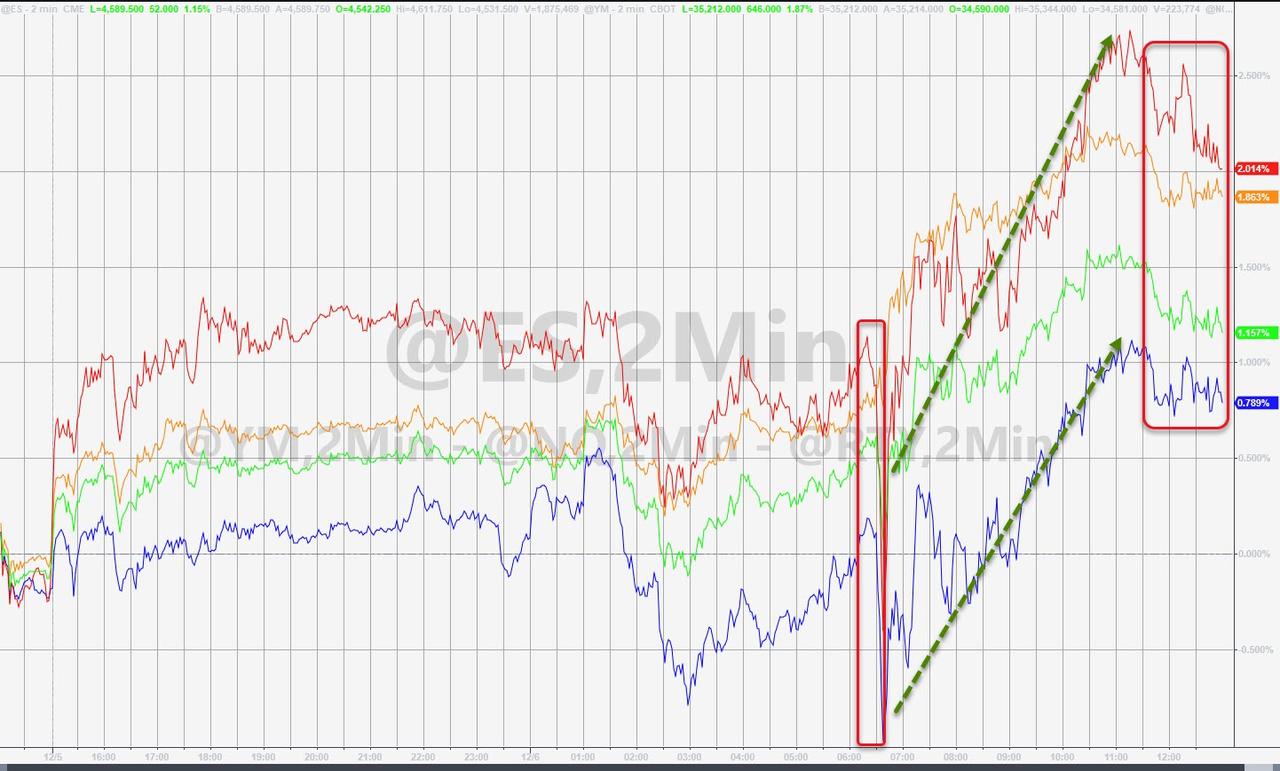
The award for the most chaotic roller coaster ride of the day goes to SmallCaps, which pumped, dumped and pumped and outperformed. Bond yields took an early dive, recovered, and stormed higher with the 10-year ending the day at 1.52%.

The US Dollar took a drop today by losing 0.48%, which allowed gold to built on yesterday’s bounce-back. The precious metal also was stuck on a wild ride, gave up mid-session gains, and closed just about unchanged.

I will be out tomorrow but will be back on Friday to write the week ending commentary.

Read More

Bulls In Chest Pounding Mode

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

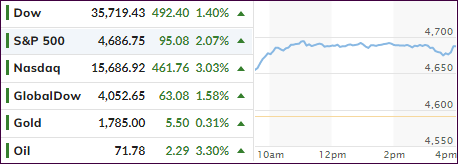
Yesterday’s strong recovery set the tone for further advances, as the bulls proved to be the dominating force after the opening bell rang. There was no hesitation as to the direction with higher prices being in clear focus for this session.

As a result, it was a one-way street with buyers being in charge because of lessening fears of any potential negative economic impact caused by the Omicron variant. In the absence of such worries, at least for this day, the major indexes stormed higher with especially the beaten down Nasdaq sporting a solid comeback of over 3%.

The revival was broad based, but it remains to be seen if any reappearance of Omicron headline news will keep traders in the game, or if we’ll be heading back from a one-way street to a two-way street.  

“Growth” trounced “Value” by a huge margin with RPG gaining 3.58% vs. 1.43% for RPV. SmallCaps had a good showing too with VBK gaining 3.12%.

Posted Zero Hedge:

Omicron’s ability to evade vaccine and infection-induced immunity is “robust but not complete,” said the research head of a laboratory at the Africa Health Research Institute in South Africa.

That news item took the starch out of upward momentum late in the day, with markets dipping and then ripping, a phenomenon that was especially apparent and unexplainable in the Nasdaq due to the index gaining 100 points in 4 minutes. Huh?

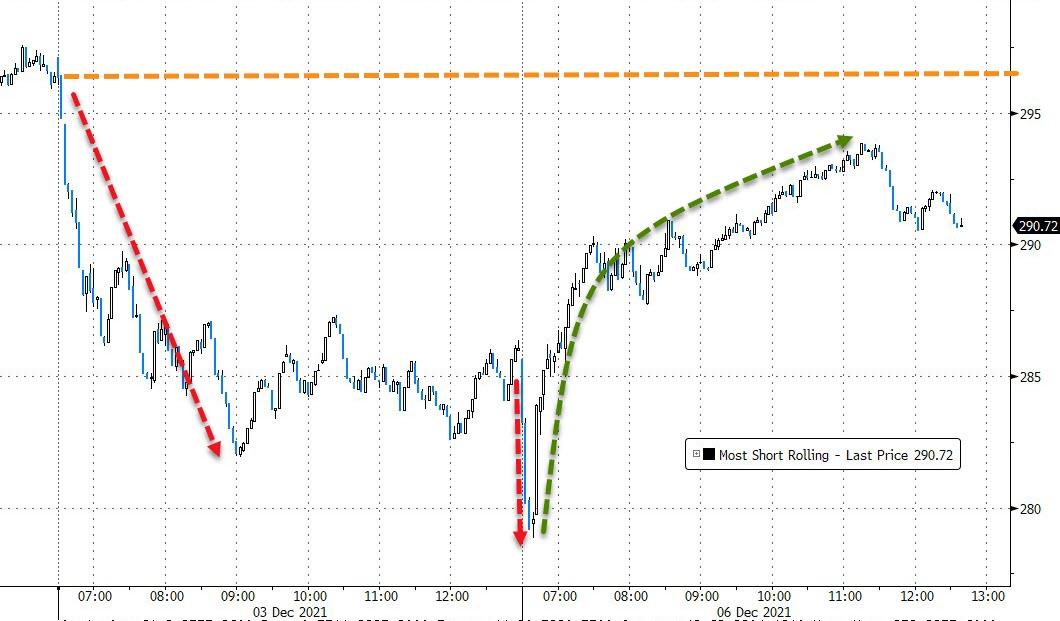
Of course, none of the above would be possible without solid support from another short squeeze, which was simply a continuation of yesterday’s ramp.

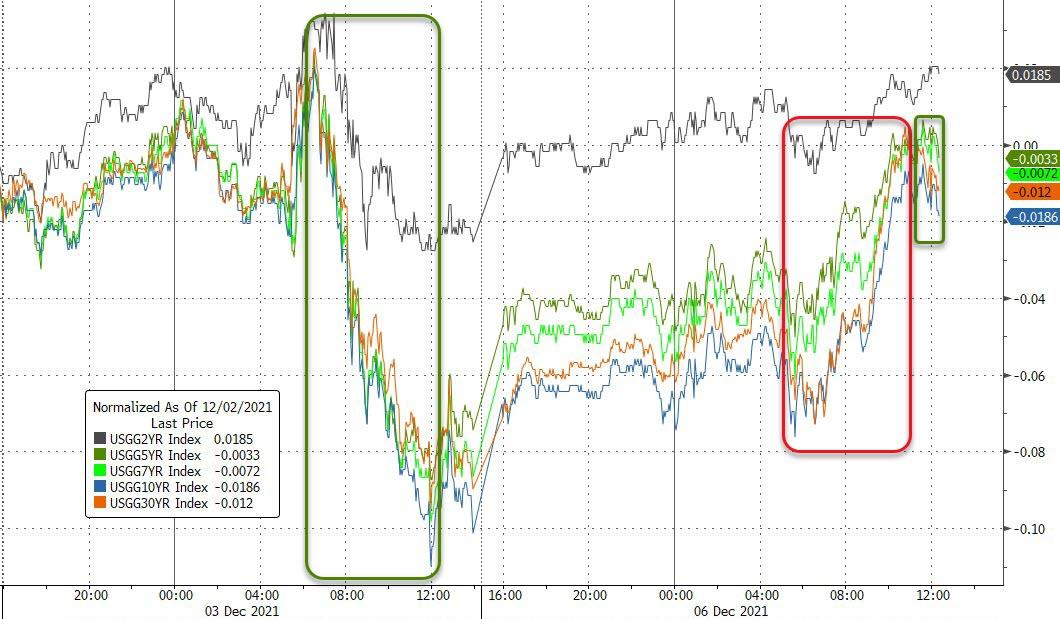
Bond yields rallied with the 10-year digging itself out of a deep hole for the second day in a row. The US Dollar danced within its recent trading range but closed slightly lower. Gold ended near its intra-day highs and gained a modest 0.30%.

It was another good day for the bulls. Is this the much hoped-for Santa Claus rally?

Read More

Conquering Friday’s Puke-A-Thon

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets

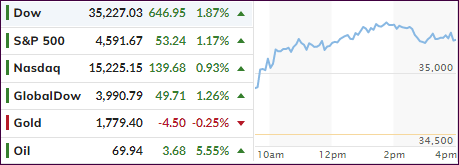
After wild rides in the markets last week, which saw early rallies wiped out later in the session, we finally witnessed an opening surge that improved throughout the day and did not peter out in the afternoon. Sure, momentum slumped a little into the close, but that can be expected.

In the process, the Dow managed to erase all last week’s losses, while the S&P 500 just fell a fraction short. MarketWatch summed up today’s influencing forces like this:

  • Shares linked to the economic reopening gained in Monday trading, including energy, industrials, and airlines.
  • Investors continued to sell tech stocks with relatively high valuations. Those shares dragged the market down to a losing week on Wall Street last week.
  • The 10-year Treasury yield rebounded after falling last week amid the omicron threat.
  • There’s a major shift underway at the Federal Reserve to bring about a faster end to its pandemic easing policies.

The Nasdaq lagged the other two major indexes as the health care and tech sectors were weighing down the indicator, with Moderna being the biggest decliner by shedding 15%.

Anxiety about the new Omicron variant remains, despite continuous reports of its symptoms being less severe, but fearmongering in the MSM seems to be always in high gear. It appears that any economic data are playing second fiddle to the latest headlines dealing with Covid 19 or its variants.

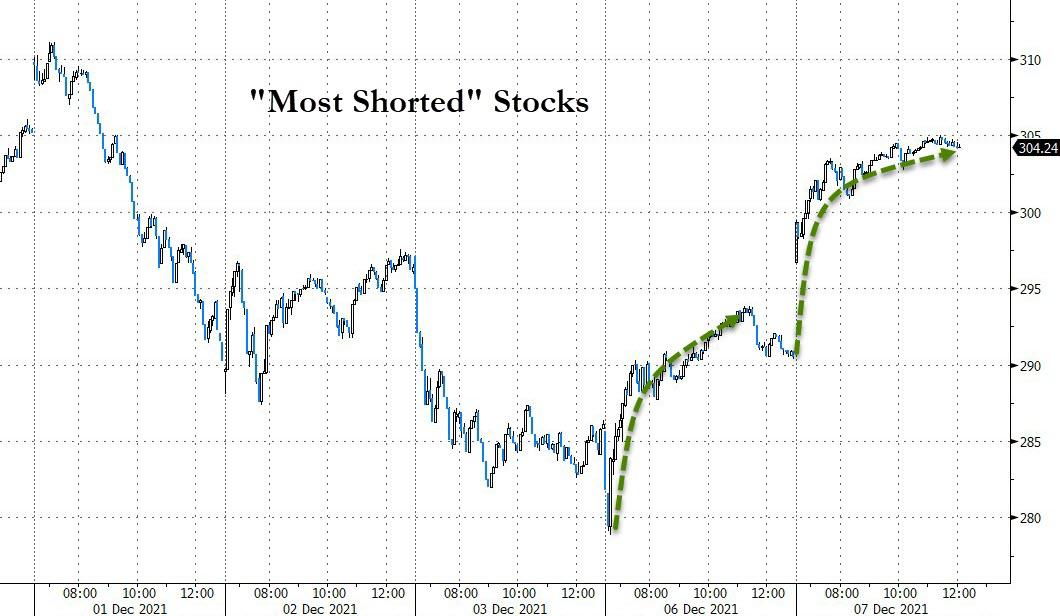
Finally, the short squeeze came back to life again, after being suspiciously absent during last week, and gave a much-needed assist to insure the rebound would not run out of steam.  

Bond yields surged after an early dump, with the 10-year eking out a small gain and closing the session at 1.48%. The US Dollar went sideways for most of the day but ended up higher by a modest 0.19%.  

Gold drifted lower after Friday’s strong rebound with the precious metal giving back 0.24%, while still attempting to permanently conquer its much fought for $1,800 level.

I expect the recent volatility to stay with us, especially when on Friday the much-anticipated US CPI will be released.

Read More

ETFs On The Cutline – Updated Through 12/03/2021

Ulli ETFs on the Cutline Contact

Below, please find the latest High-Volume ETF Cutline report, which shows how far above or below their respective long-term trend lines (39-week SMA) my currently tracked ETFs are positioned.

This report covers the HV ETF Master List from Thursday’s StatSheet and includes 312 High Volume ETFs, defined as those with an average daily volume of more than $5 million, of which currently 140 (last week 170) are hovering in bullish territory. The yellow line separates those ETFs that are positioned above their trend line (%M/A) from those that have dropped below it.

Take a look:                                                                   

The HV ETF Master Cutline Report

In case you are not familiar with some of the terminology used in the reports, please read the Glossary of Terms. If you missed the original post about the Cutline approach, you can read it here.