[Chart courtesy of MarketWatch.com]
- Moving the markets
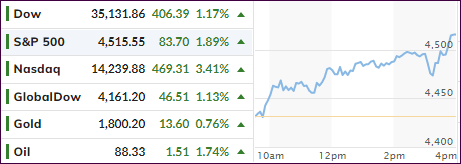
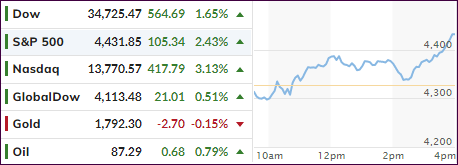
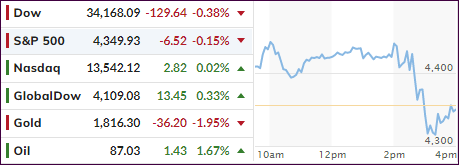
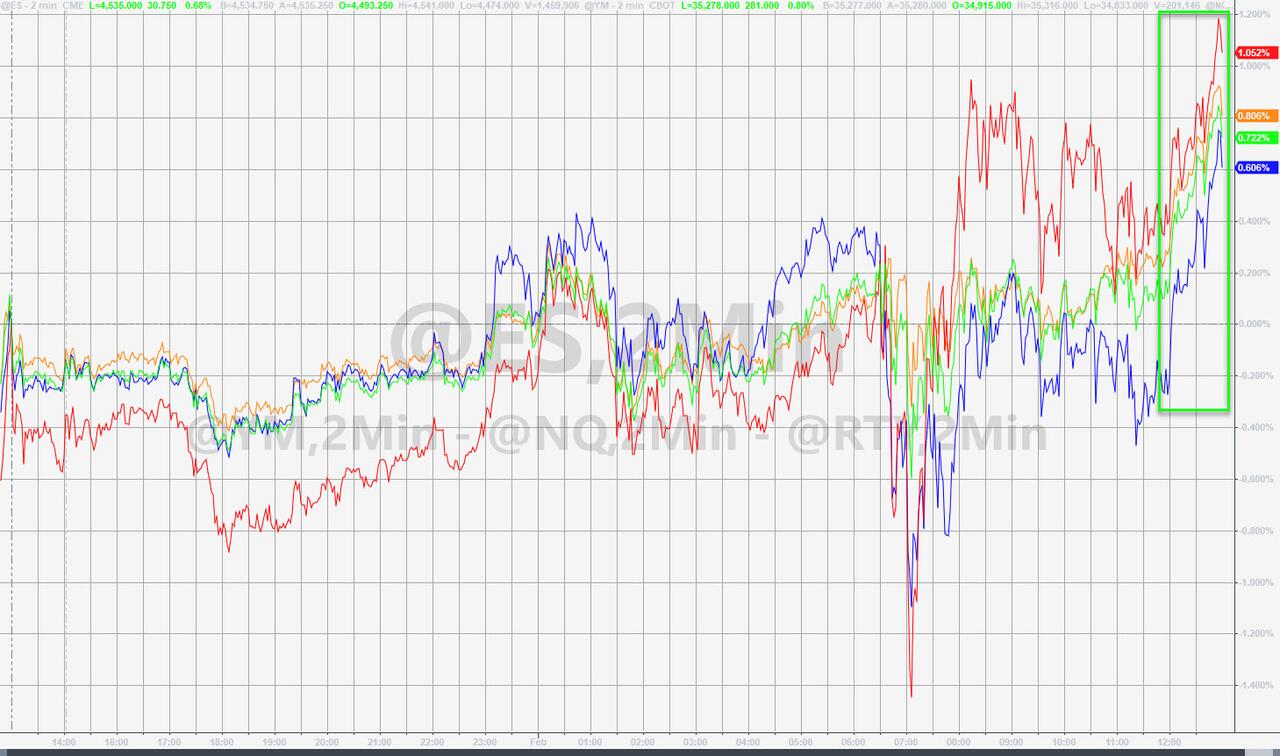
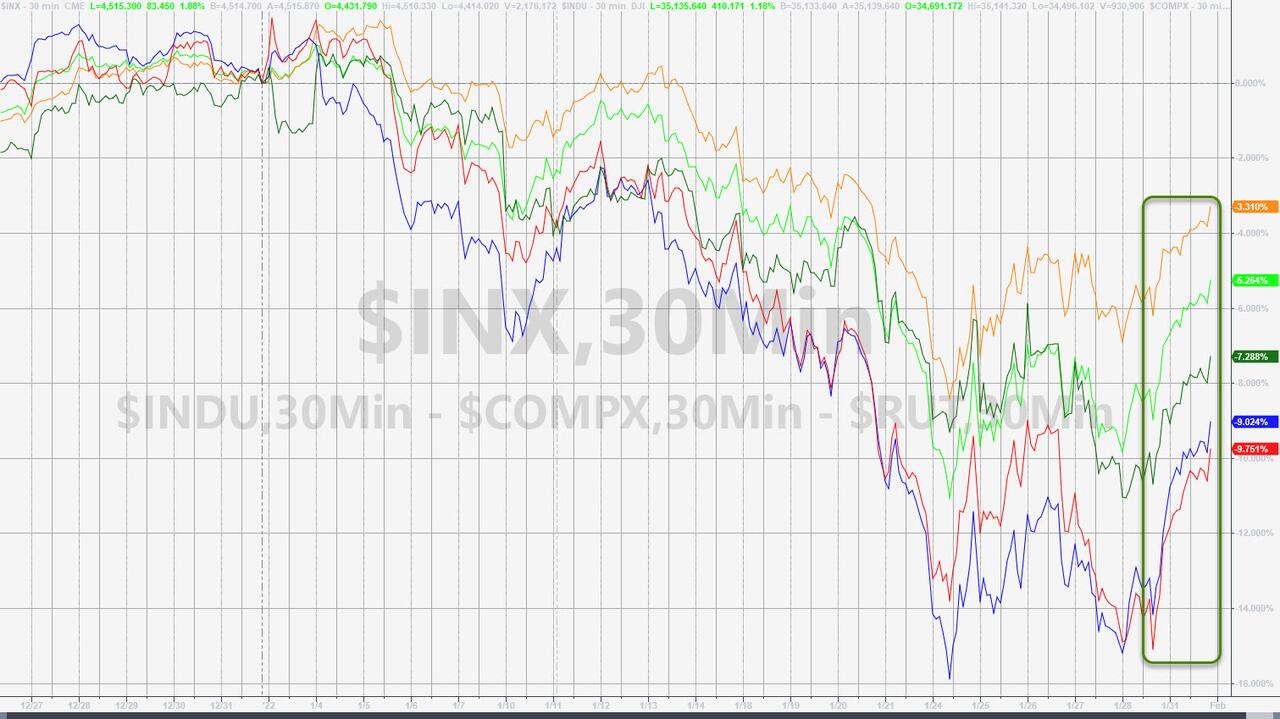
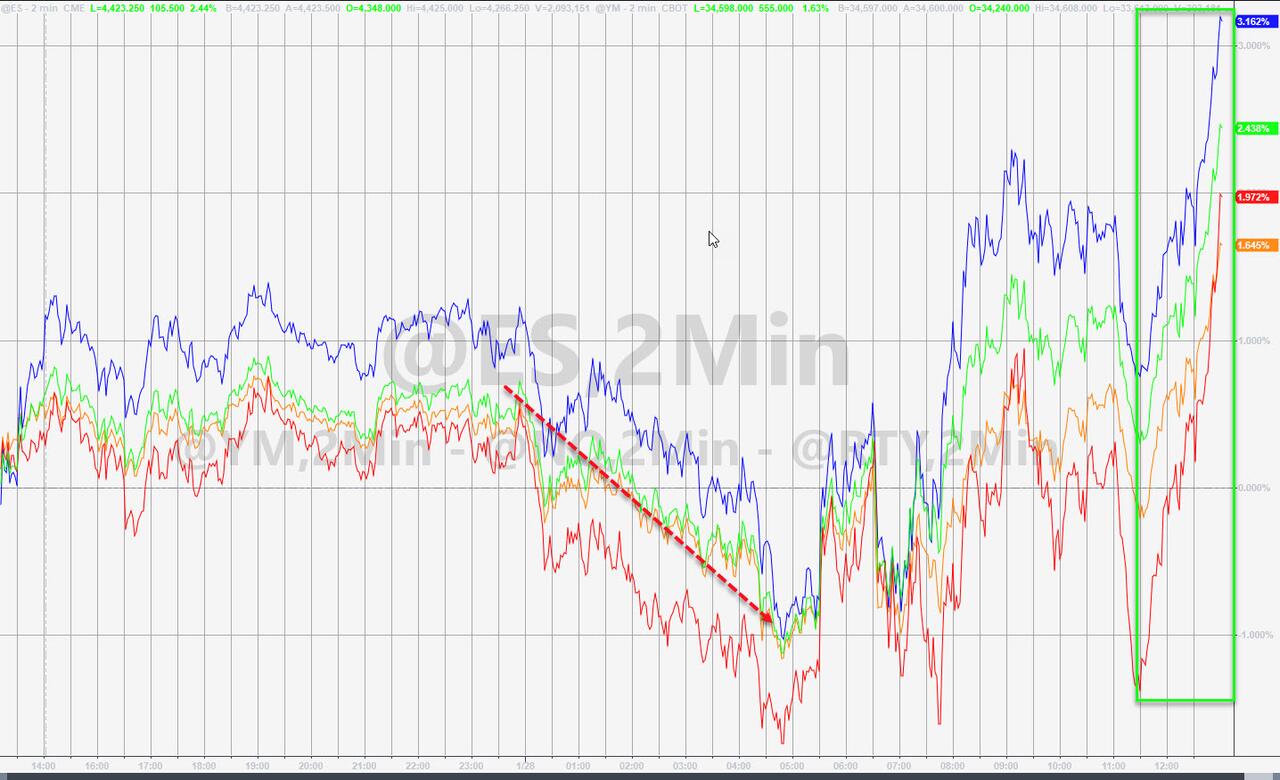
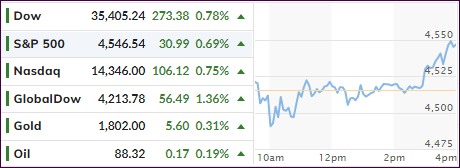
The major indexes meandered for most of the day looking for direction and found it during the last hour, as the attempt to climb back from January’s sell-off continued. Traders’ focus seemed to have suddenly changed from the Fed towards the earnings season and those companies’ beating expectations while issuing improved forward guidance.
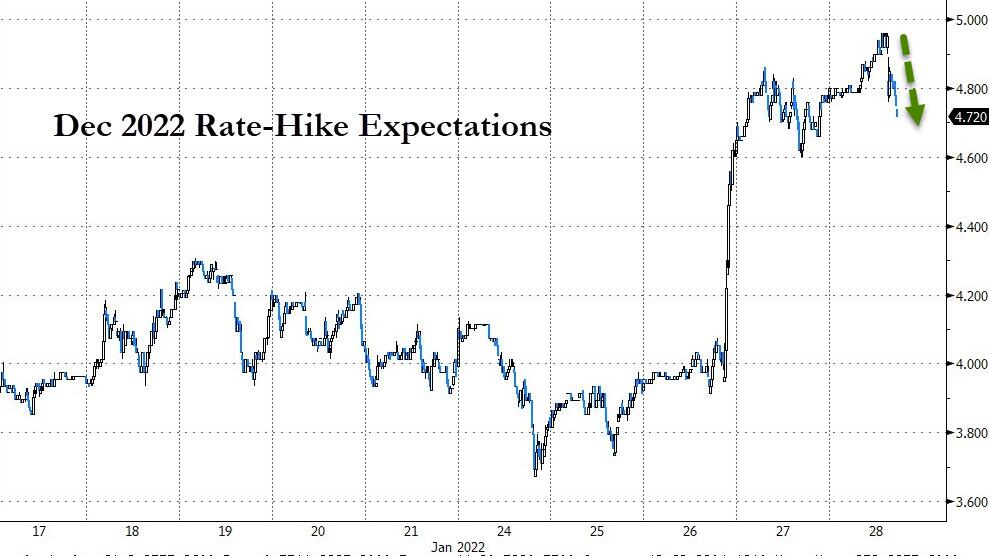
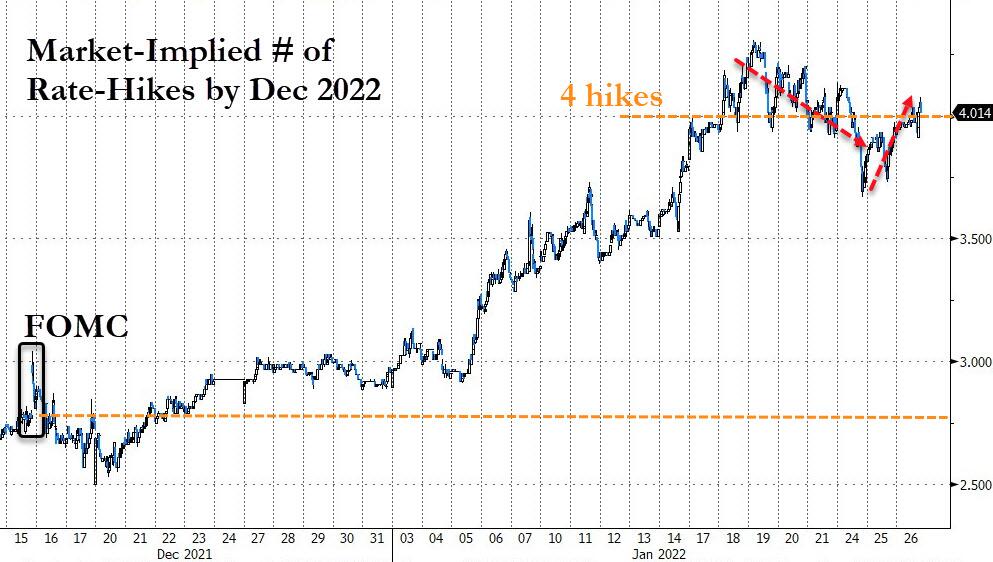
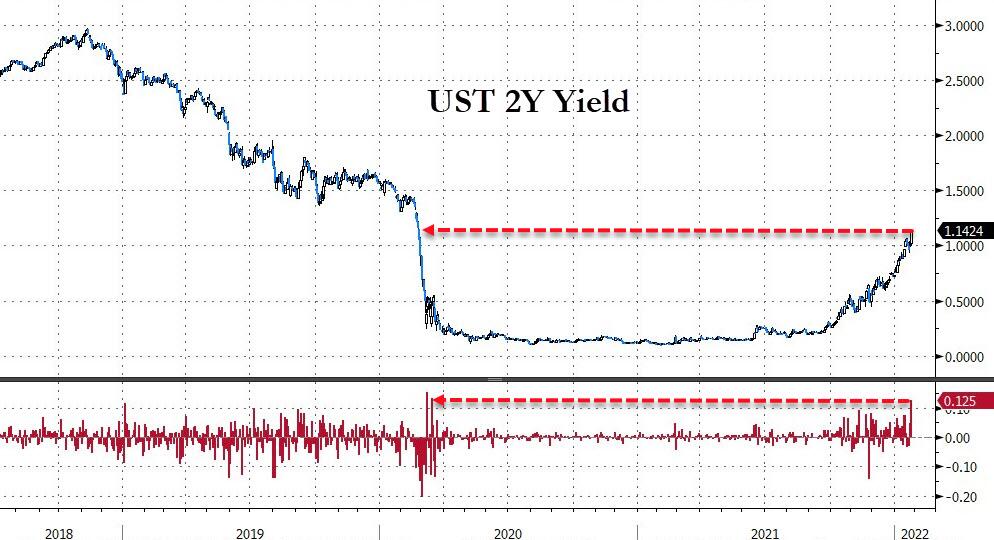
At least that was the meme for the day, which may last only until that moment in time when the Fed steps up to the plate and reconfirms its readiness to tighten monetary policy.
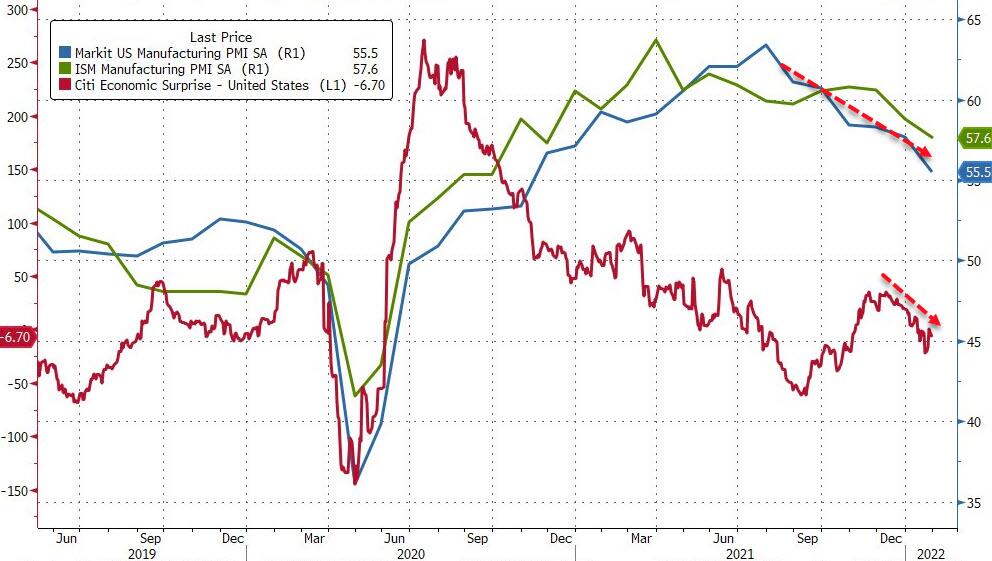
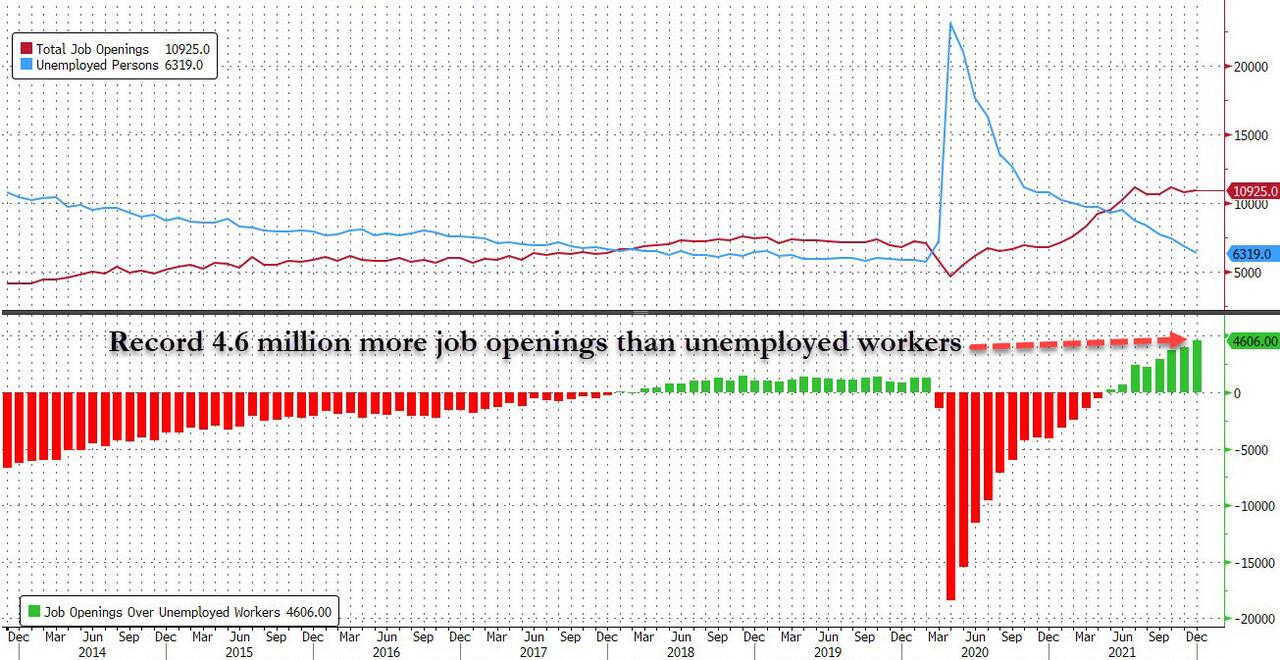
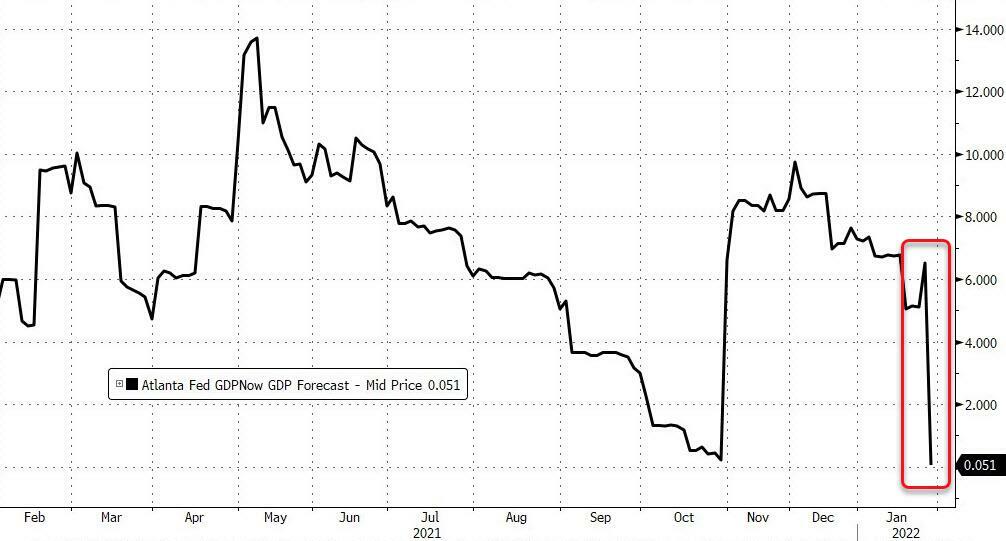
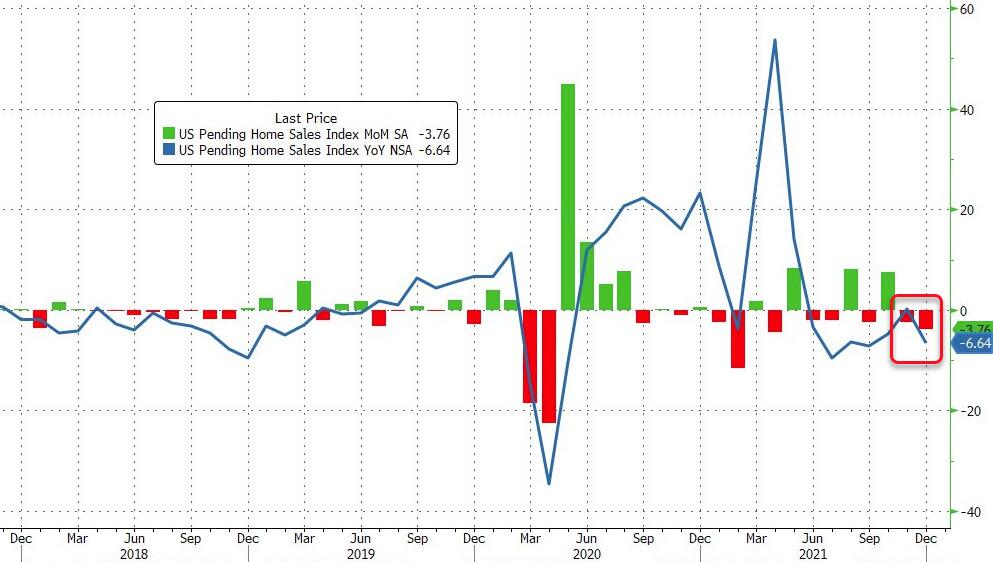
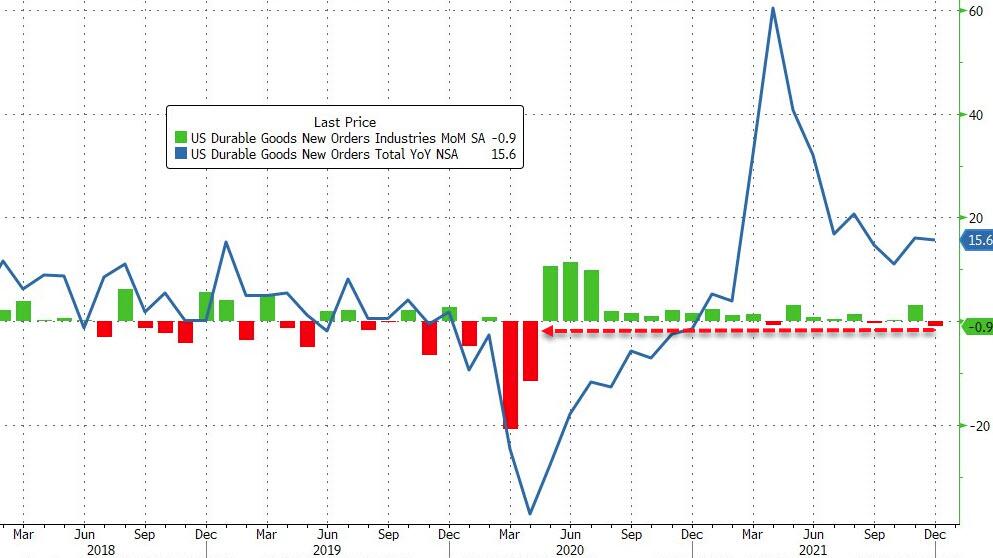
For sure, it was a session that lacked positives, as we learned that US Manufacturing weakened even more in January, which was followed by “Labor Insanity,” as ZH called it, which means that there are now a record 4.6 million more job openings than unemployed workers. Then investment powerhouse Goldman Sachs slashed its 2022 GDP forecast again, while warning of a “sharp deceleration in growth.”
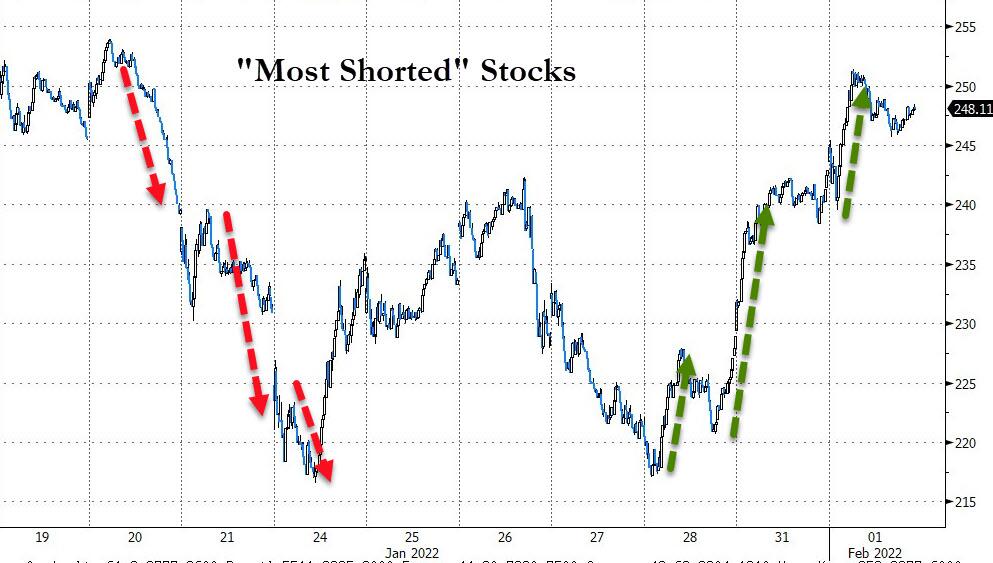
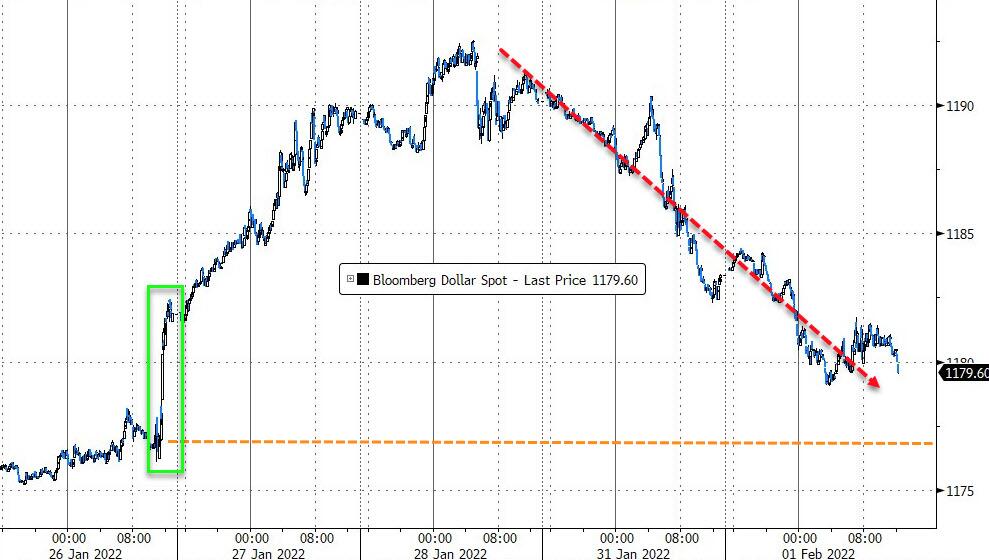
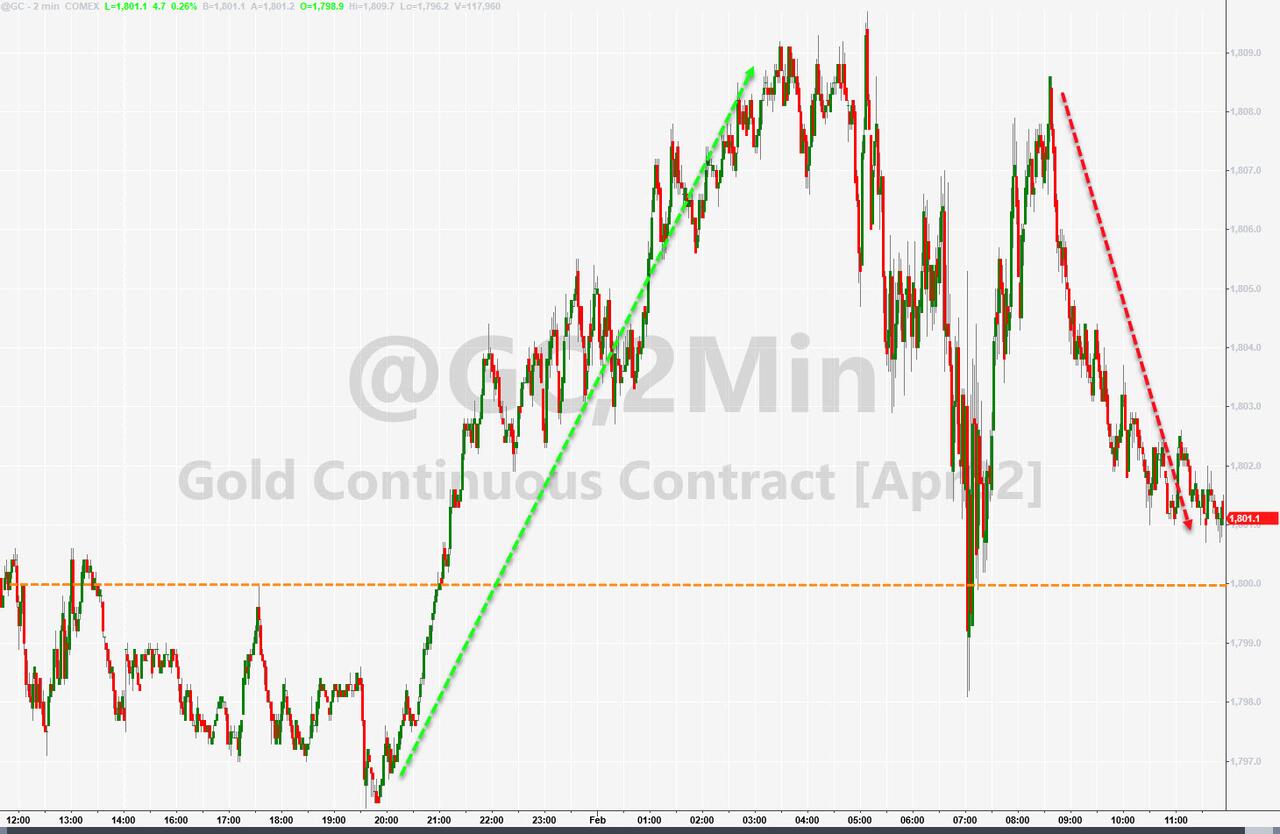
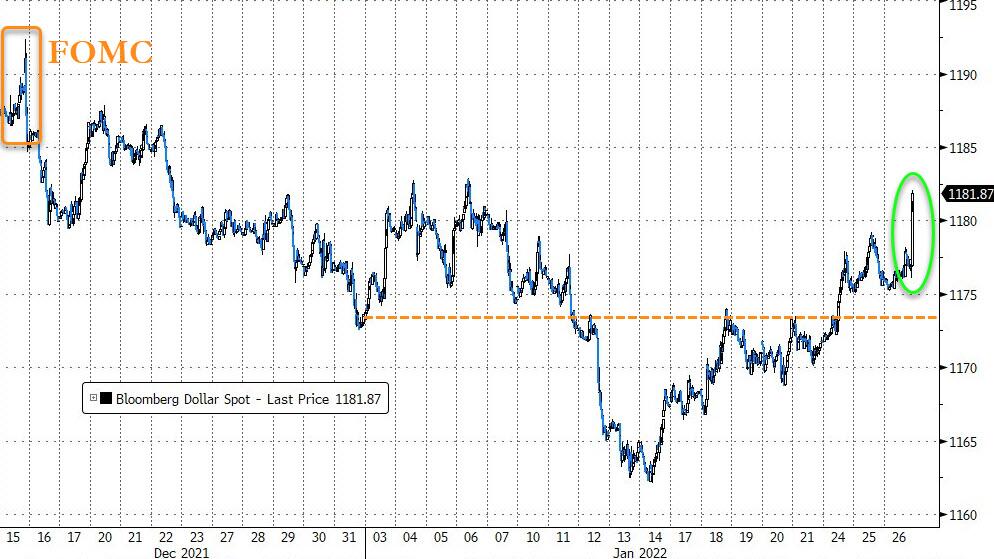
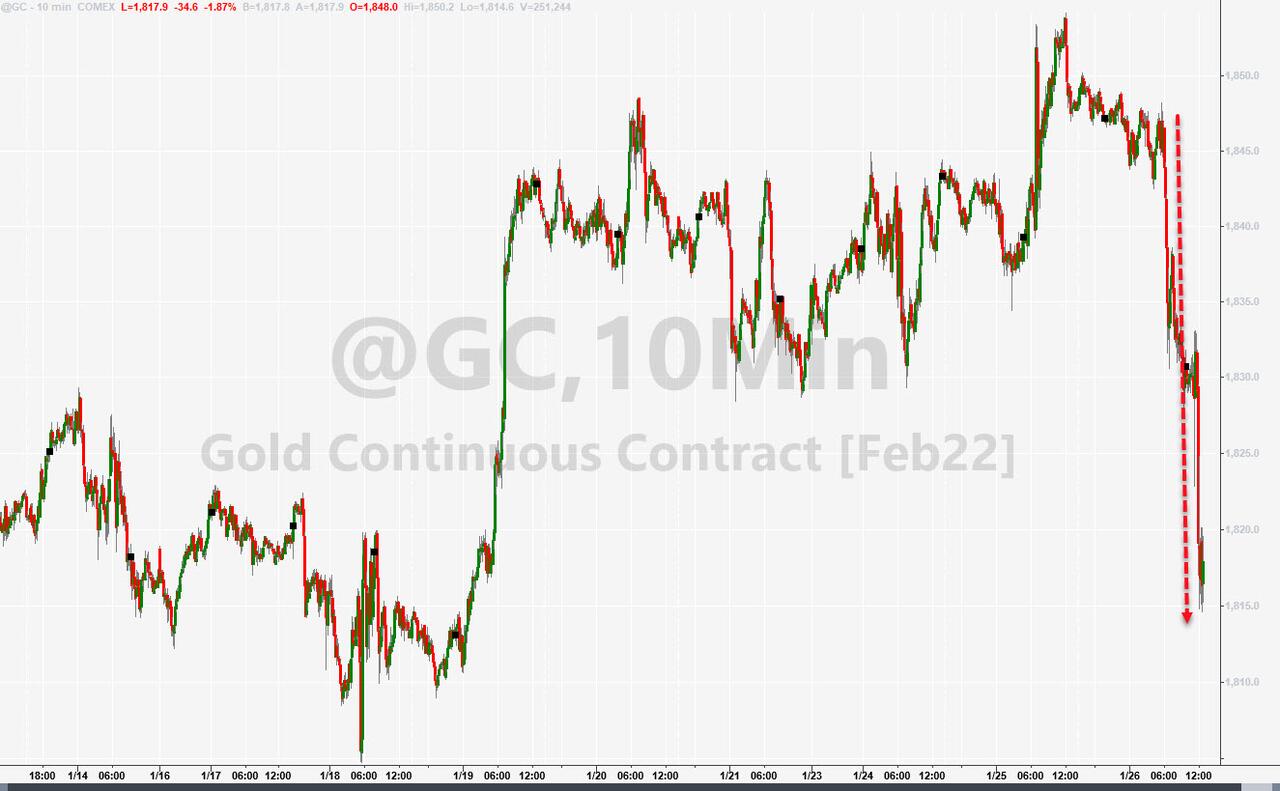
The most shorted stocks were squeezed again for the third day in a row and contributed to the rebound. The US Dollar continued its puke-a-thon and slipped off its January 28th highs, while Gold pumped and dumped but not only closed up but also reached its $1,800 level again.
And just maybe, we are seeing a repeat of the same old theme that says, ‘bad news is good news.’ In context to the above, it simply means that worsening economic data may sway the Fed from following through with their interest rate hiking agenda, thereby keeping their loose monetary policy intact.
That’s the hope on Wall Street.
Read More