Market Celebrates Thanksgiving With A Feast Of Gains, But Will It Face A Reality Check Soon?

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

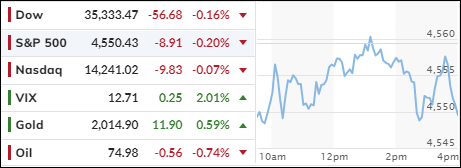
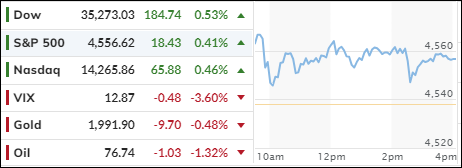
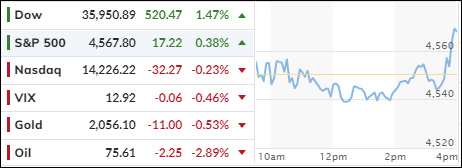
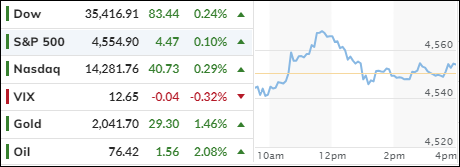
The stock market celebrated Thanksgiving with a feast of gains, as the Dow Jones Industrial Average hit a new high for 2023 on Thursday. The index was boosted by inflation data that raised hopes of a Fed rate cut next year.

The S&P 500 also managed to end the day in positive territory, while the Nasdaq lagged. Both indexes were still within striking distance of their 2023 peaks.

The S&P 500 had a stellar November, rising 8.9%. However, this was partly a rebound from a dismal September and October when it lost 7.1%. So, over a three-month period, the gain was less impressive.

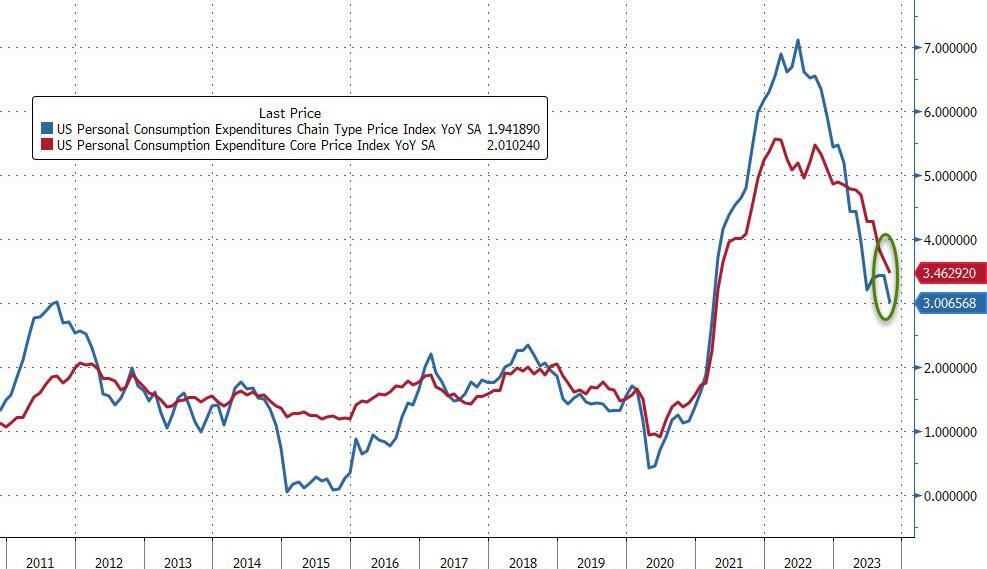
The inflation data that cheered the market was the personal consumption expenditures price index (PCE), which is the Fed’s preferred measure of price changes. The PCE rose 0.2% in October, matching expectations, and 3.5% year-over-year. This suggested that inflation was cooling down, but not too much to hurt growth. Traders hoped that this would give the Fed enough reason to keep rates steady, before lowering them in 2024.

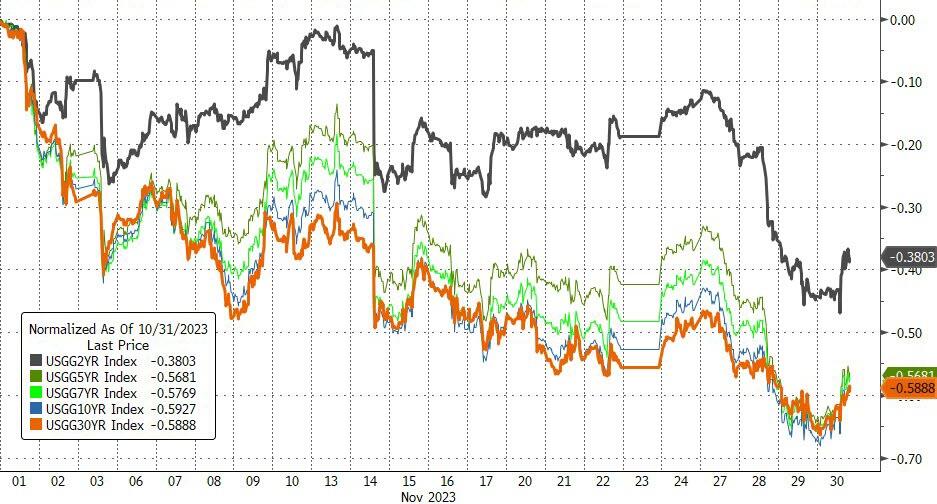
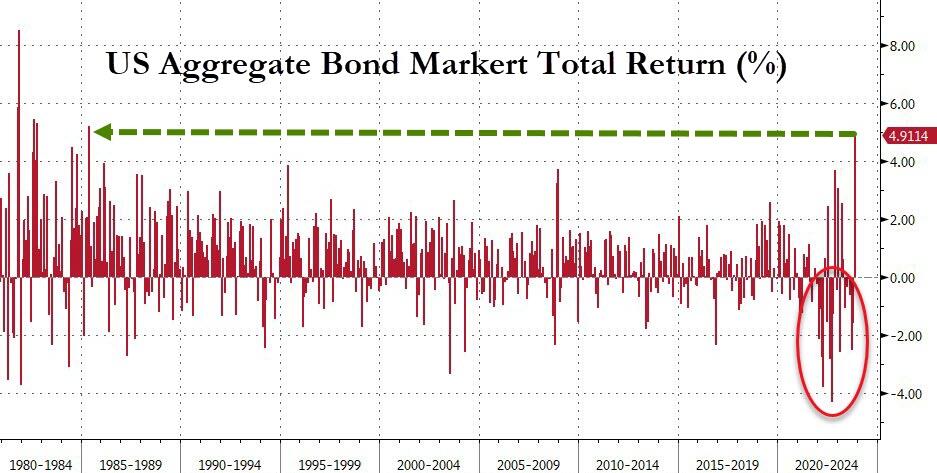
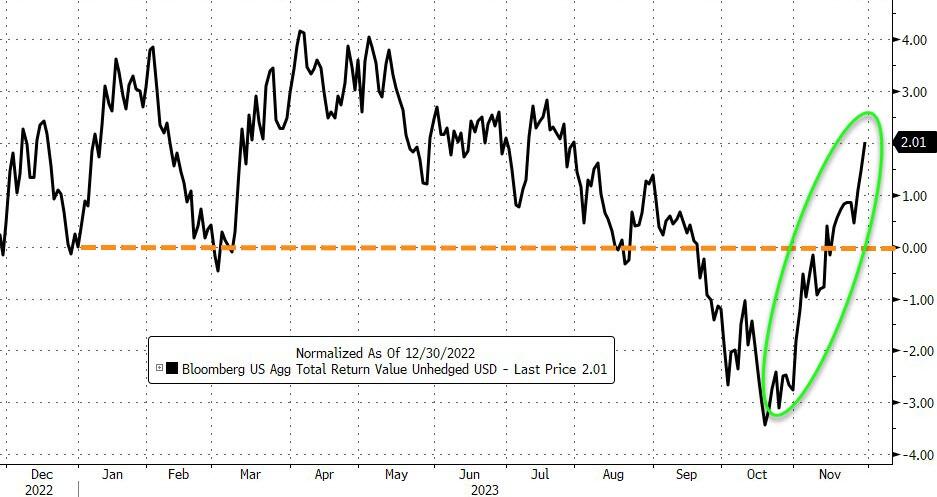
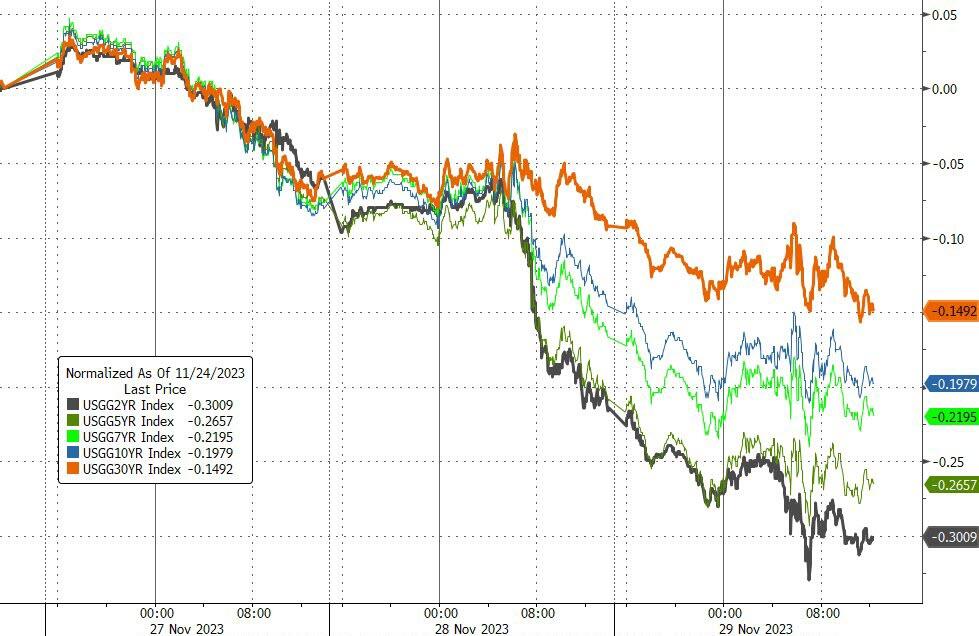
The bond market also had a great month, as yields dropped in November. US bonds had their best month since May 1985 and turned positive for the year. As one analyst remarked, “suddenly 5% yields on the 10-year have become a distant memory.”

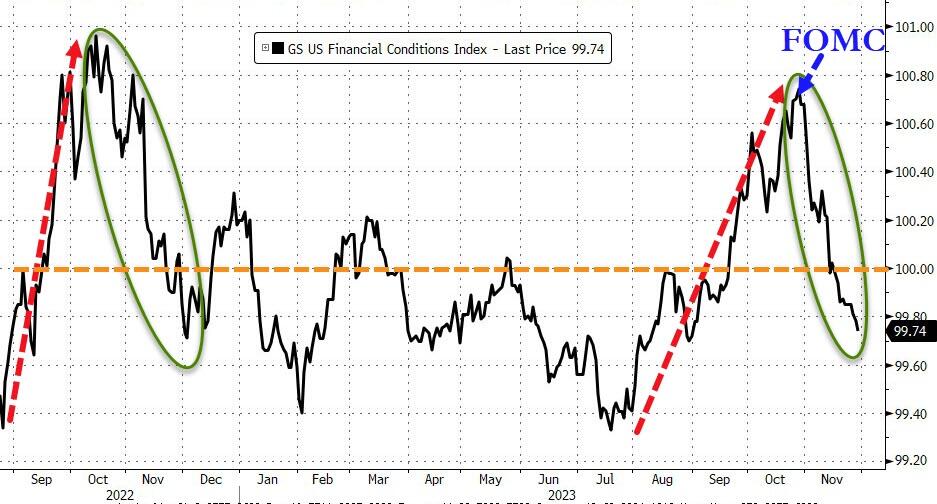
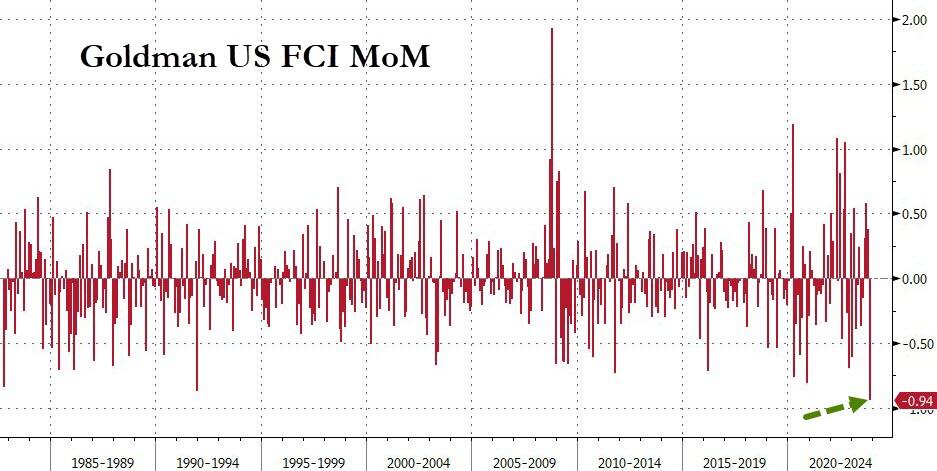
The rally in bonds and stocks made financial conditions much easier, in fact, October saw the biggest absolute monthly loosening of financial conditions in history (back to 1982).

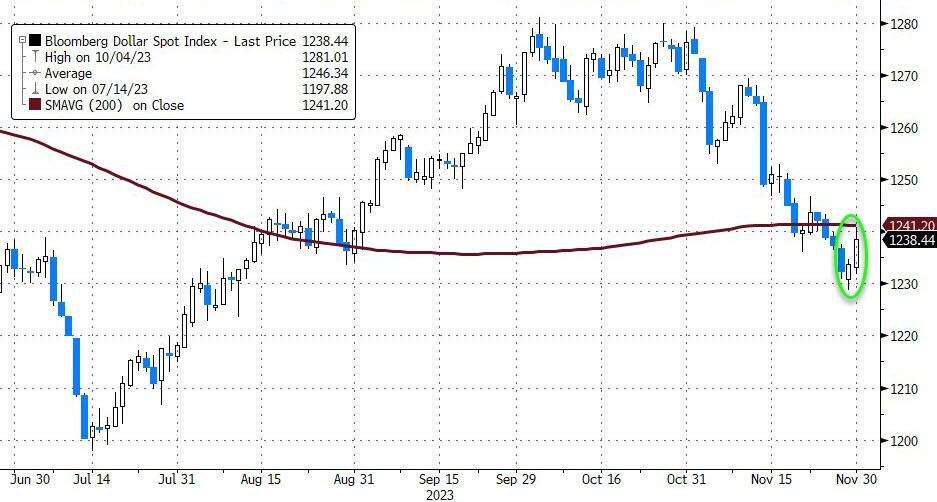
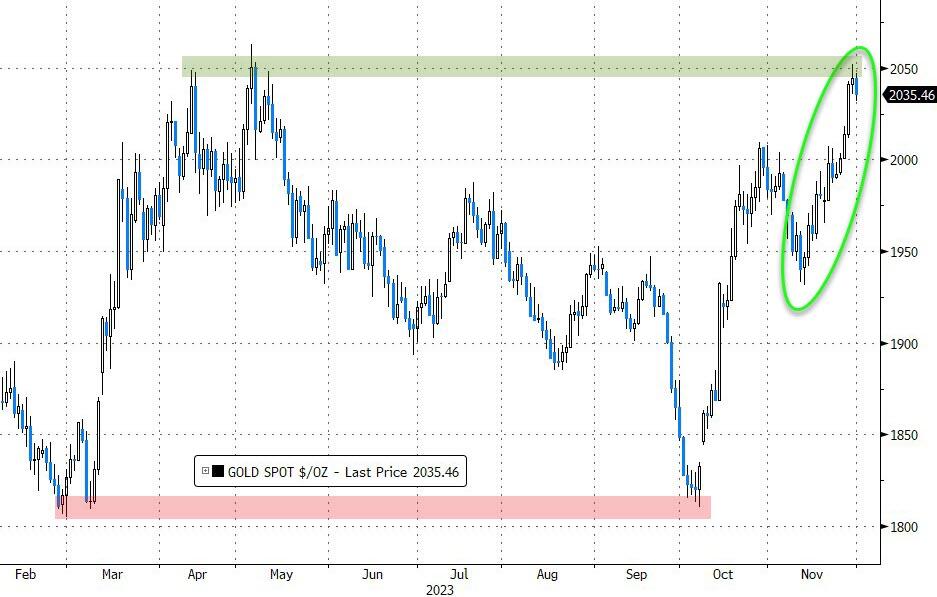
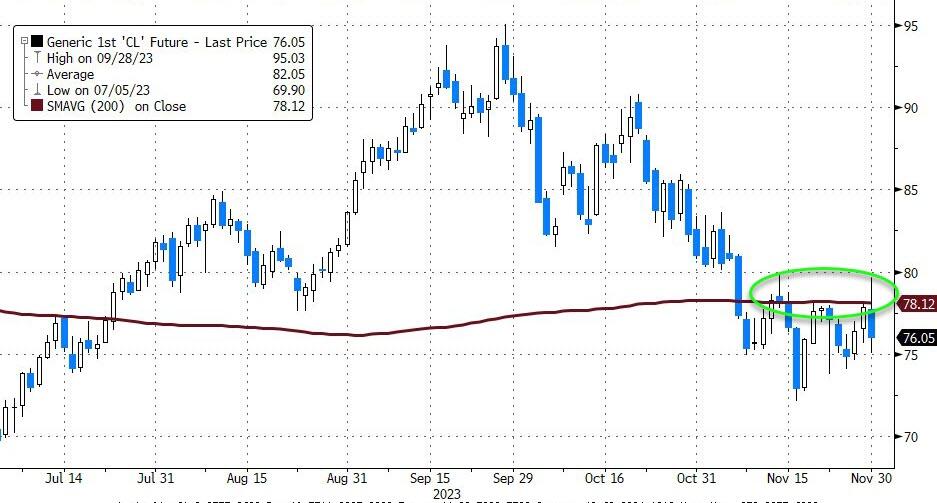
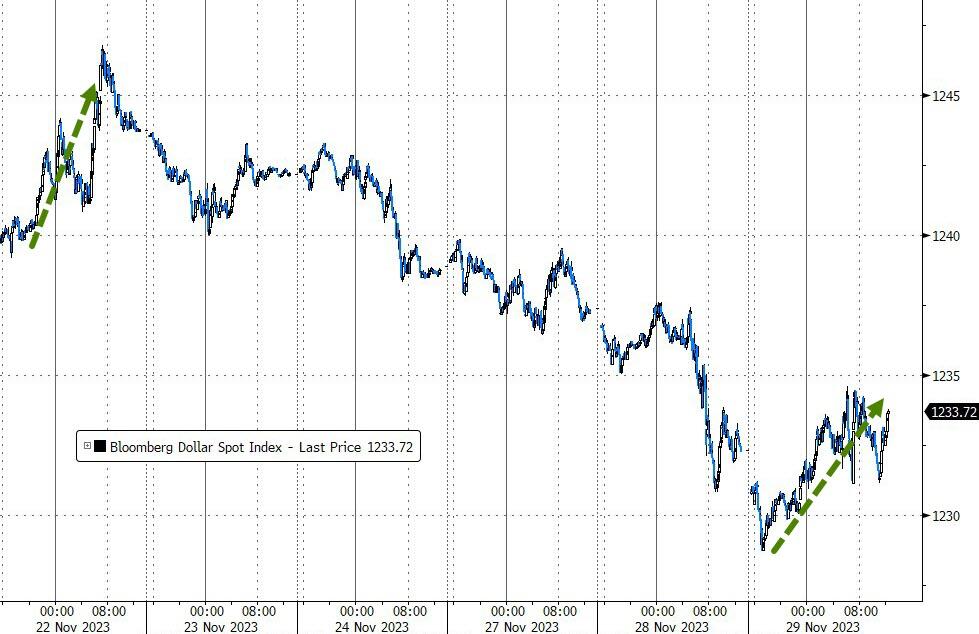
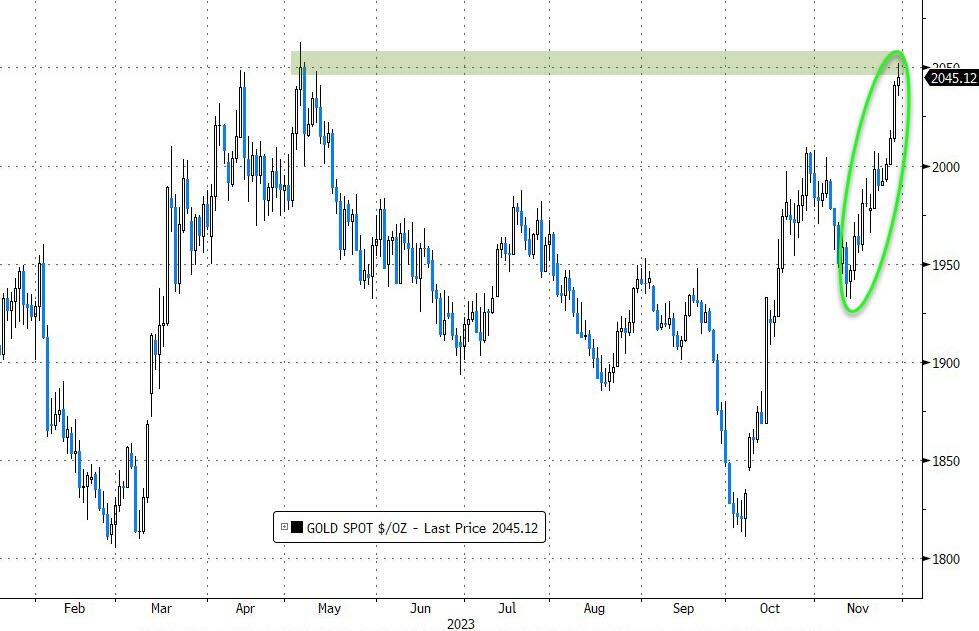
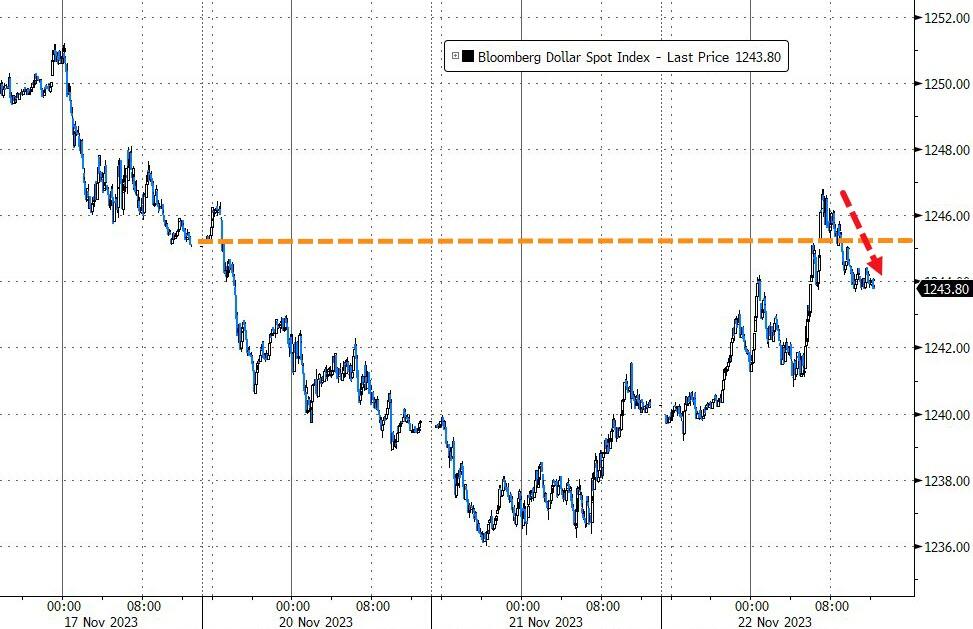
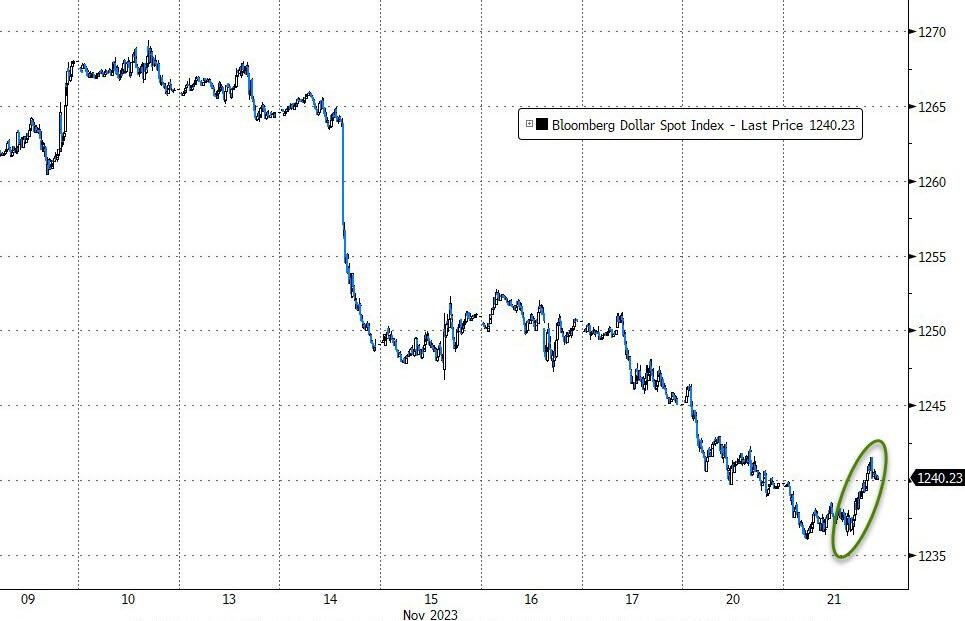
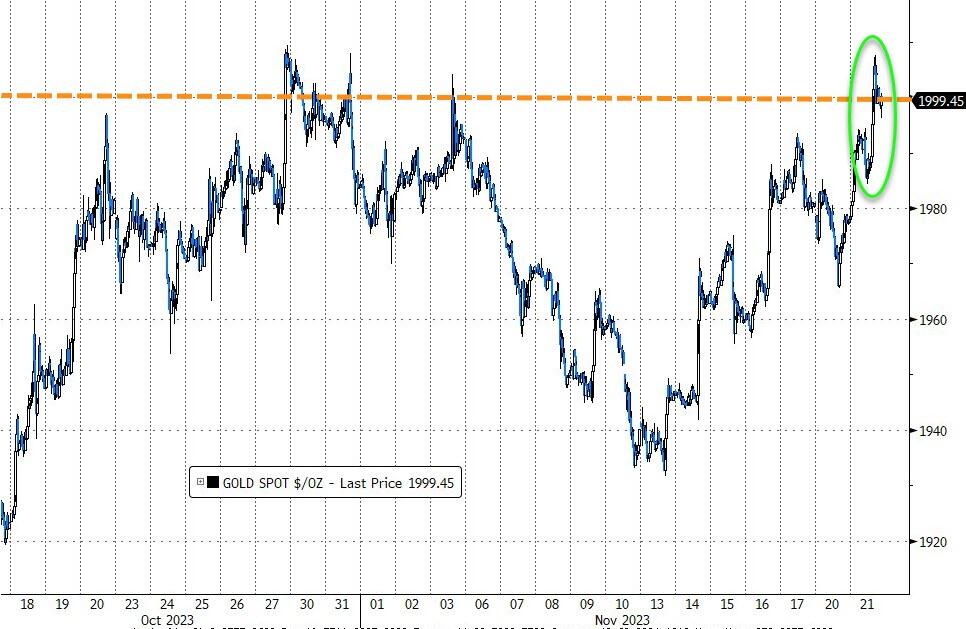
The dollar had a rough month, falling 3% in November. This was its biggest monthly decline since November 2022. Gold shone for the second month in a row and was close to breaking its record high. Oil prices slipped for the second consecutive month.

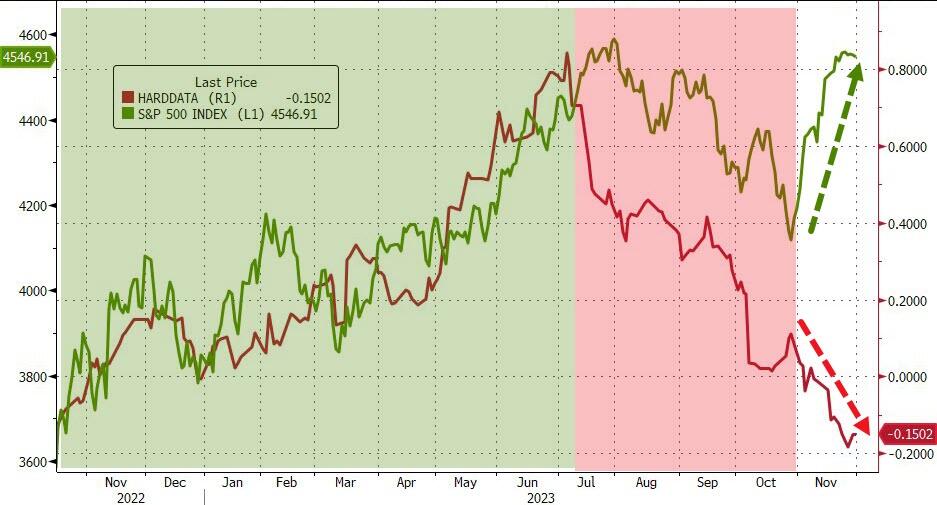
As ZeroHedge pointed out, November was truly a month of “bad news” being “good news” for stocks, as “hard data” hit a 14-month low, while stocks surged back near record highs.

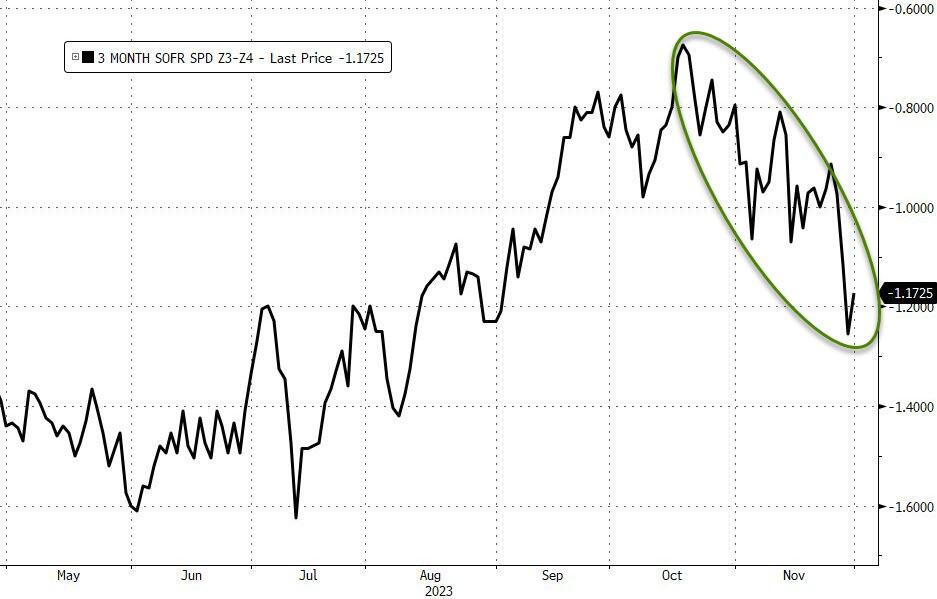
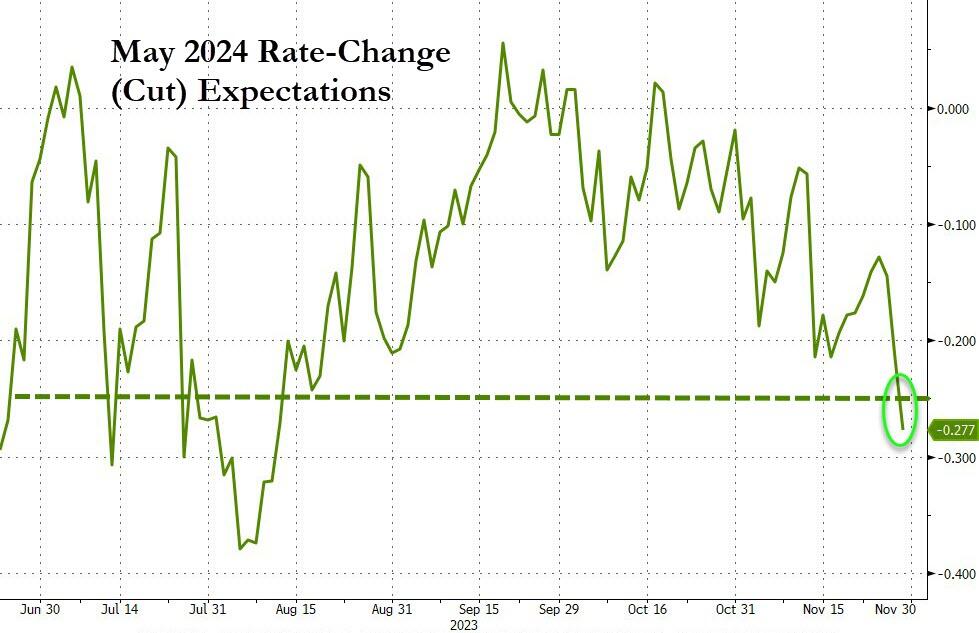
Traders are elated that inflation has been coming down, and at the same time it hasn’t been unduly affecting growth. But be careful what you wish for. After all, if financial conditions loosen much more, the Fed will be forced to jawbone some reality back into the market, as November saw the biggest increase in rate-cut expectations for 2024 since Nov 2022.

Will the markets be able to handle any dose of reality?

Read More
Market Swings Between Hope And Fear As Fed Sends Mixed Signals

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

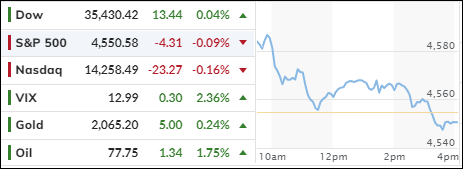
The stock market had a wild ride today, as investors were torn between hope and fear. On one hand, they hoped that the Fed was done hiking rates, and that the economy would be growing faster than expected. On the other hand, they feared that inflation was still a threat and that the Fed might change its mind and raise rates again.

The hope came from the latest GDP data, which showed that the economy grew at a 5.2% annual rate in the third quarter, thanks to more government spending and business investment. It also came from the comments of Fed Governor Waller, who said that the current policy was tight enough to bring inflation down to the Fed’s 2% target.

The fear came from the remarks of Richmond Fed President Barkin, who said that the Fed could still hike rates if inflation did not cool down. It also came from the uncertainty about the Fed’s plans. Will they start to signal rate cuts for next year, as the market expects? Or will the Fed surprise the market with a hawkish stance, as inflation might rebound and prove to be more than transitory?

The market did not know how to react to these mixed signals. The major indexes swung back and forth, ending the day with modest losses. The bond market, however, had a clear reaction. Bond yields fell sharply, as investors priced in more rate cuts for next year. The 10-year and 30-year yields dropped by 65 basis points this month, the biggest monthly decline since 2008.

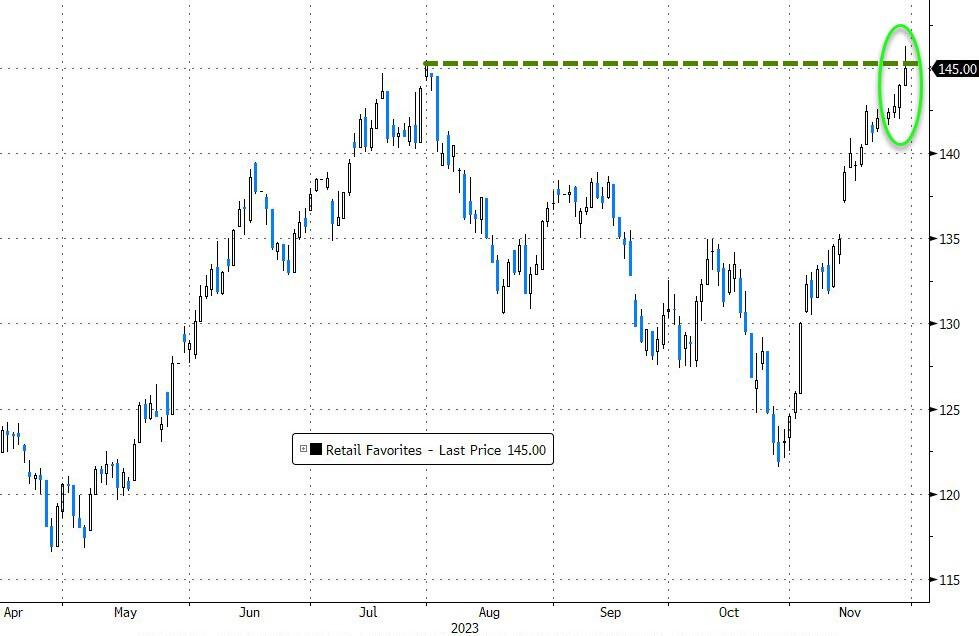
The lower yields boosted the stock market, especially the meme stocks that are popular among retail investors. Goldman Sachs’ index of retail favorites hit a new high this month. The dollar also bounced back, while gold continued to soar towards new records. Oil prices were volatile, as traders awaited the outcome of the OPEC+ meeting on production quotas.

This market summary ends with a question that captures the main dilemma facing investors:

Will the Fed cut or hike rates next year? This question invites you to think about the implications of the Fed’s actions for the economy and the markets.

Read More

Fed Official Boosts Market With Dovish Comments, Gold Nears Record High

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

The stock market edged up slightly today, continuing its November comeback, after a Fed official hinted that interest rates may not go up any further. Christopher Waller, a Fed governor, said he was confident that the current policy was enough to cool down the economy and bring inflation back to the 2% target. He spoke ahead of the next Fed meeting on December 12-13.

The slight gain today came after a strong month of trading, which will end on Thursday. The S&P 500 is set to end the month with an 8.4% increase, more than making up for the 7.1% drop in September and October. But this also shows that the November rally was not as impressive as it seemed.

The market is now in a wait-and-see mode, as investors look for clues from holiday spending trends. The bulls and the bears are still in a stalemate. And that means that the market may be more choppy than smooth.

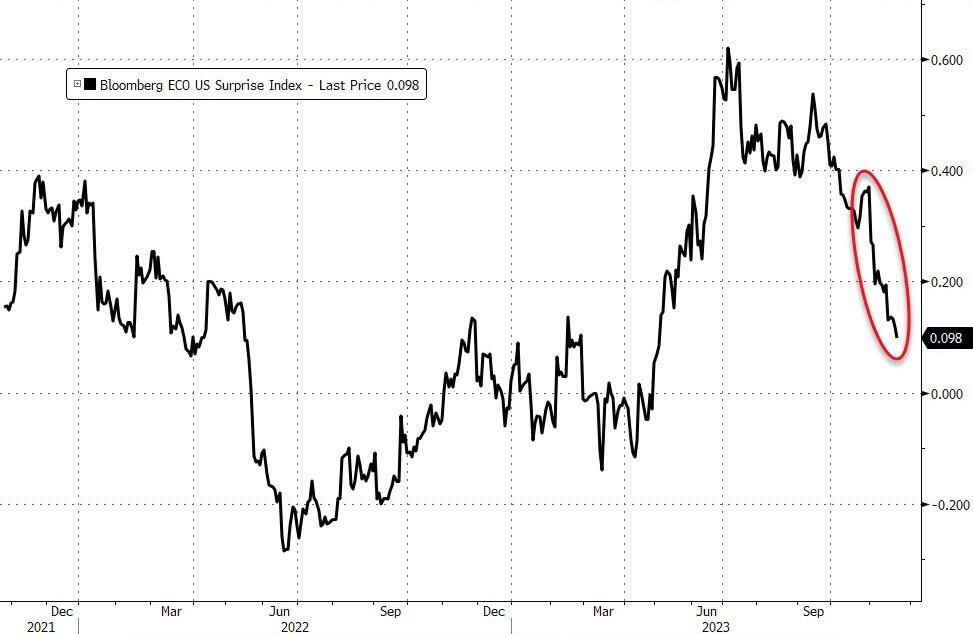
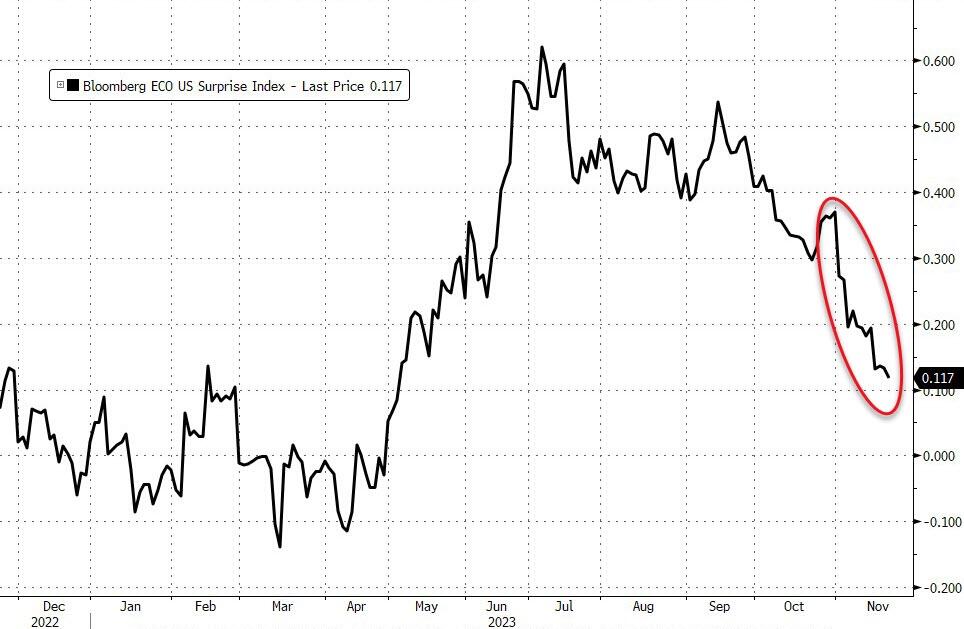
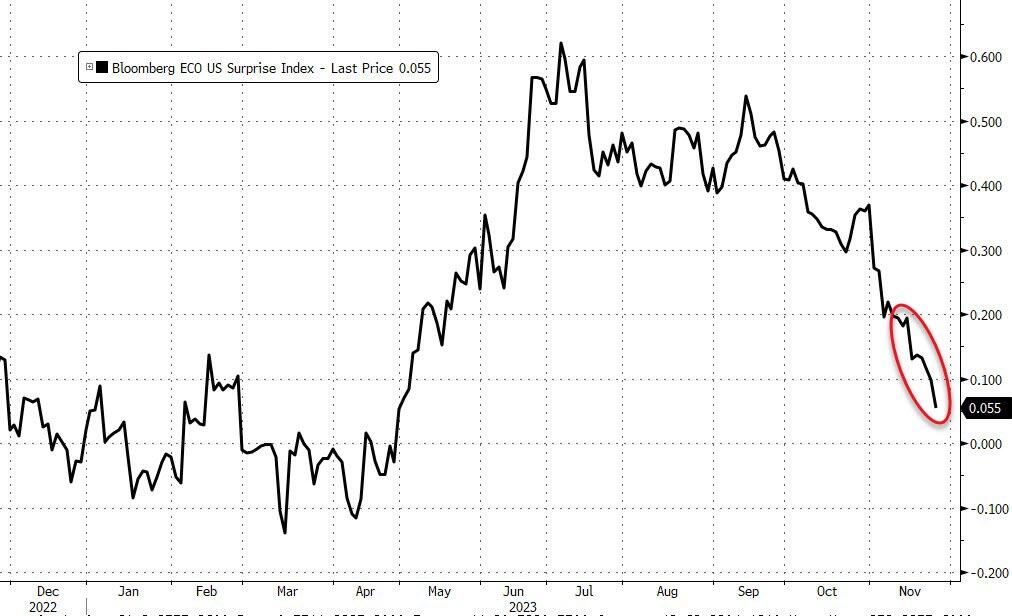
The economic data today was not very encouraging, as it showed signs of a slowing economy. Home prices, consumer confidence, and manufacturing all came in below expectations. The economic surprise index took a hit, as the effects of the government stimulus faded.

The Fed governor also warned that the recent easing of financial conditions may not last, and that policymakers should not rely on them to do their job. He said that many factors can affect financial conditions, and that they should be careful.

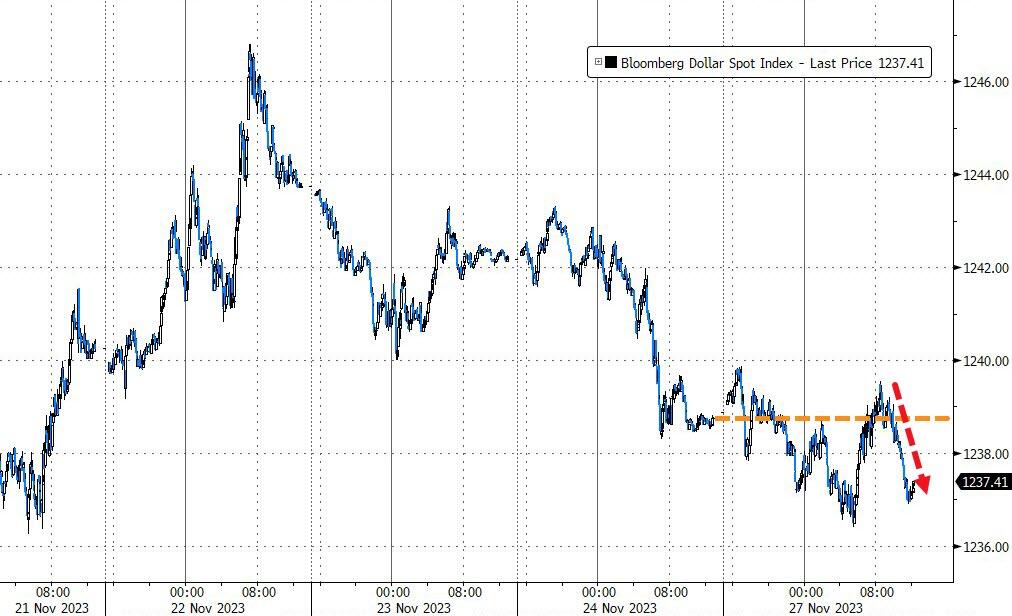
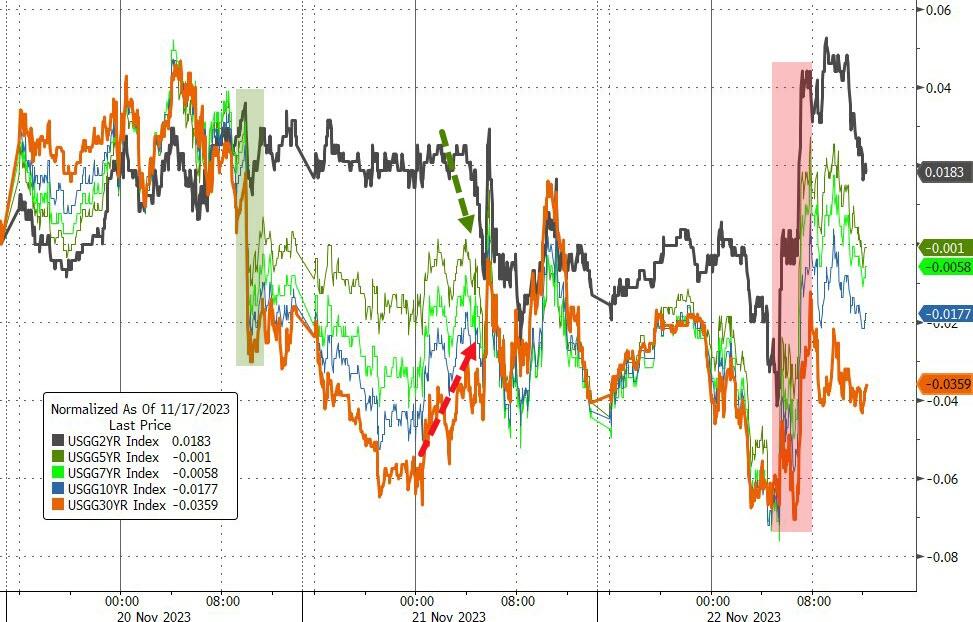
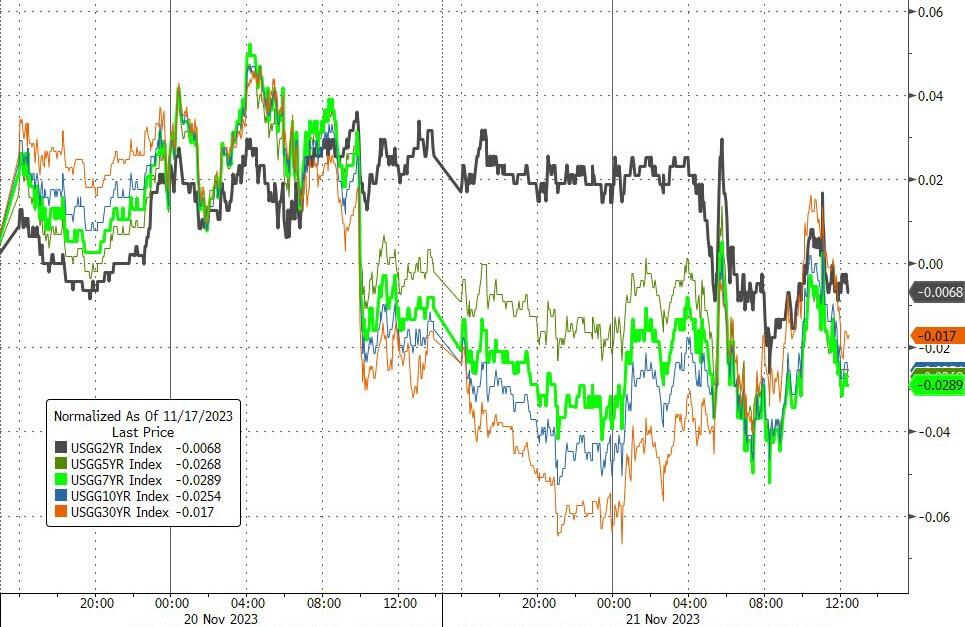
The market moved sideways for most of the day but managed to squeeze out some small gains thanks to a short squeeze. Bond yields and the dollar both fell, helping the stock market. The 10-year yield dropped to a nearly 4-month low, and the dollar hit another low.

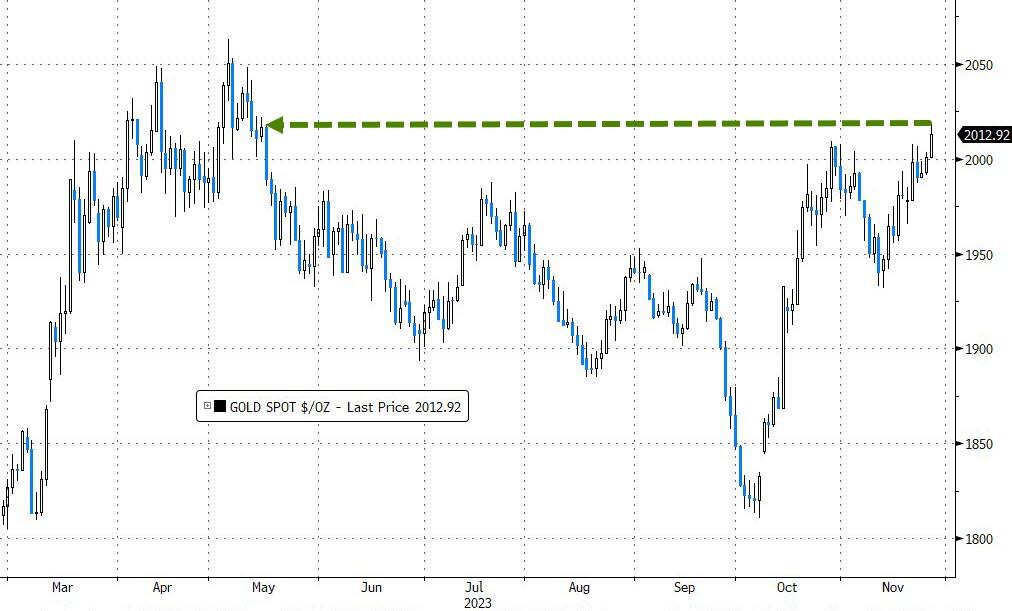
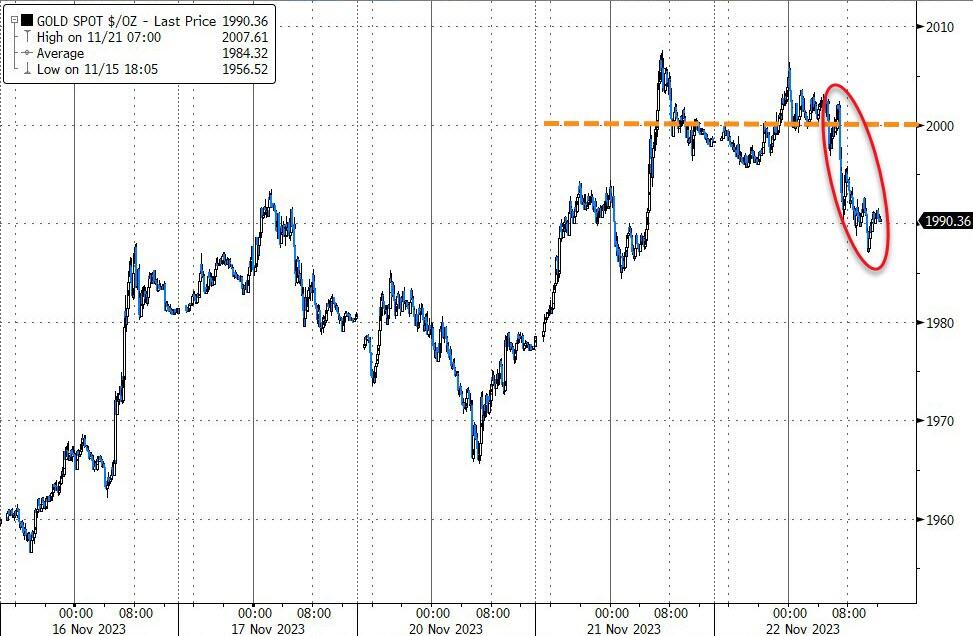
Gold benefited from the weak dollar, and rose to $2,042, close to its record high. Will it break that level this quarter?

Read More
The Fed, The Economy, And The Stock Market: A Tale Of Divergence

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

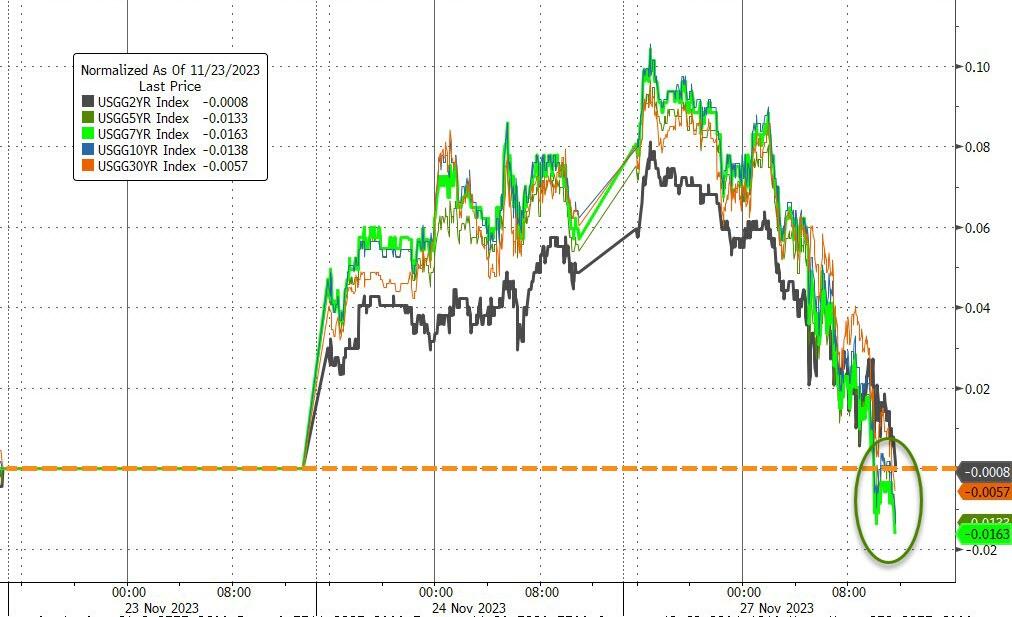
The stock market took a break from its recent rally on Monday, as investors digested the mixed signals from the economy and the Fed. The major indexes fell, ending a four-week winning streak, as the 10-year Treasury yield dropped below 5% after briefly touching that level in late October.

The market shrugged off the warnings from some U.S. retailers that consumer spending is slowing down, even though online sales on Black Friday rose 7.5% year-over-year. Perhaps the weak spending data is a sign that the Fed’s rate hikes are finally having an impact on the economy. Some traders are betting that the Fed is done with raising rates and may even start cutting them in 2024.

The 10-year Treasury yield will be a key factor for the market, especially after this week’s Fed comments and the data on consumer confidence and inflation, which are due on Thursday.

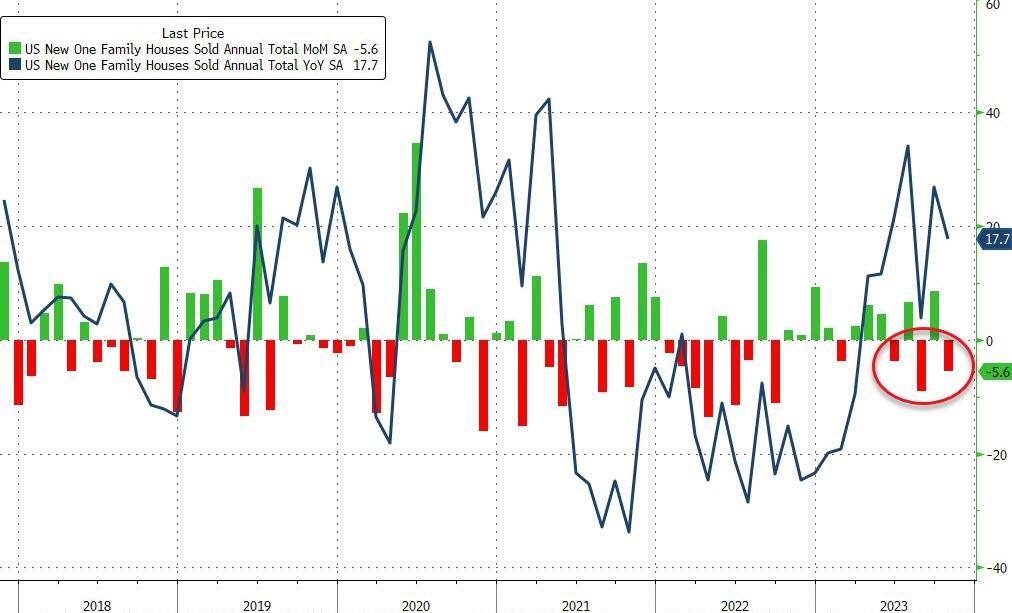
The housing market also showed signs of weakness, as new home sales fell 5.6% month-over-month in October, worse than expected. The September figure was also revised down from 12.3% to 8.6%. Ouch! The dismal home sales, along with the contraction in Texas manufacturing, dragged down the U.S. macro data.

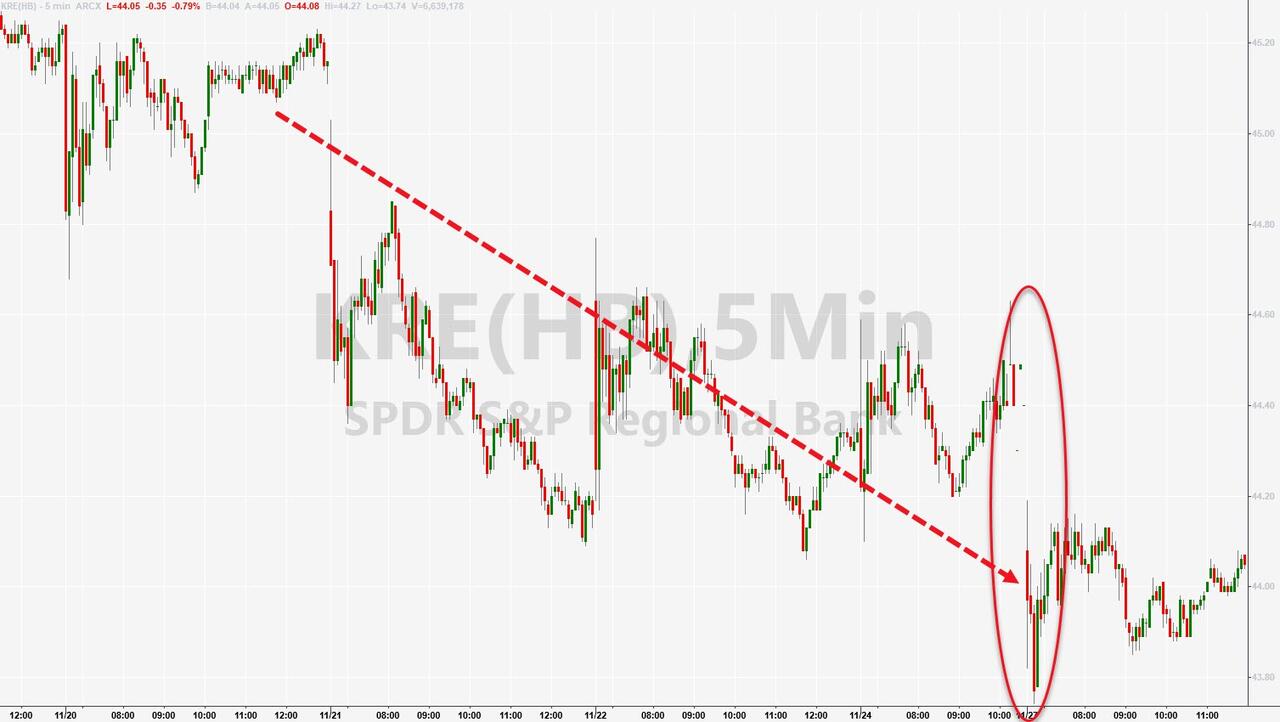
The bond market reacted to the gloomy news, as did the homebuilders and the banks. The dollar continued its slide, which boosted gold to its highest level since May.

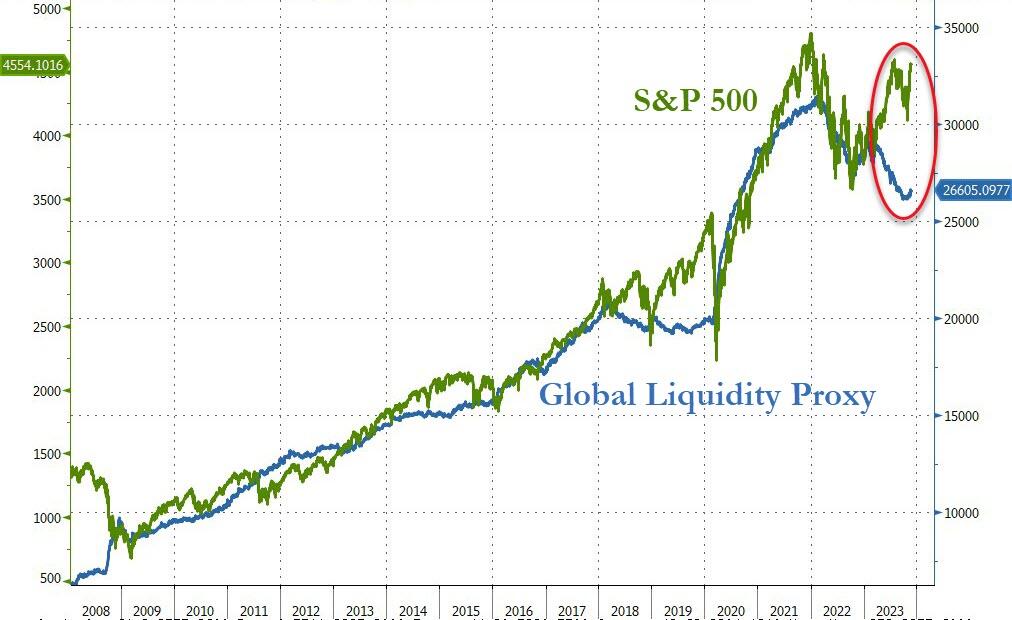
As ZeroHedge pointed out in this chart, the S&P 500 is trading way above its fair value based on global liquidity. We know that such divergences don’t last forever, but which way will they resolve? Will the S&P 500 come down to earth, or will the global liquidity catch up?

History suggests that the S&P 500 may have to eat some humble pie—sooner or later.

Read More
Market Bulls Feast On Stocks, Ignore Economic Data And Fed Minutes

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

The market bulls were in a festive mood today, as stocks climbed higher despite some gloomy economic data and a delay in OPEC’s decision on oil production. The bond market, however, was not so cheerful, as the 10-year Treasury yield briefly dipped to its lowest level in two months before bouncing back.

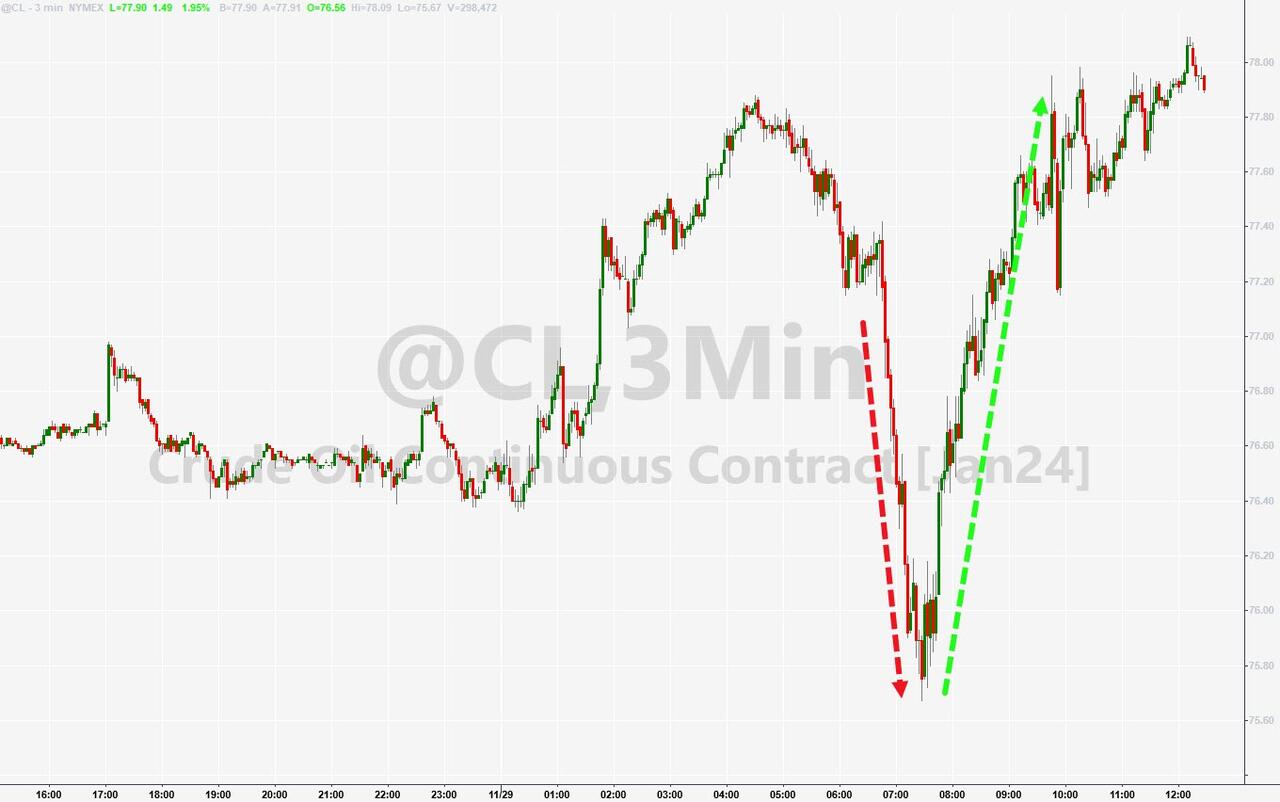
The rally was broad-based, with more than half of the stocks on both the NYSE and the Nasdaq advancing. The tech sector was especially strong, as investors shrugged off Nvidia’s disappointing guidance and focused on its solid earnings beat. The chipmaker’s shares dropped 2.5%, but still outperformed the energy sector, which fell 1% after crude oil plunged over 4.5% before recovering some of its losses.

The Fed’s latest minutes did not offer much hope for the rate-cut enthusiasts, as the central bank reiterated its hawkish stance and showed no signs of easing its monetary policy anytime soon. But the market seemed to ignore the Fed’s words and instead priced in a low probability of a rate hike in December.

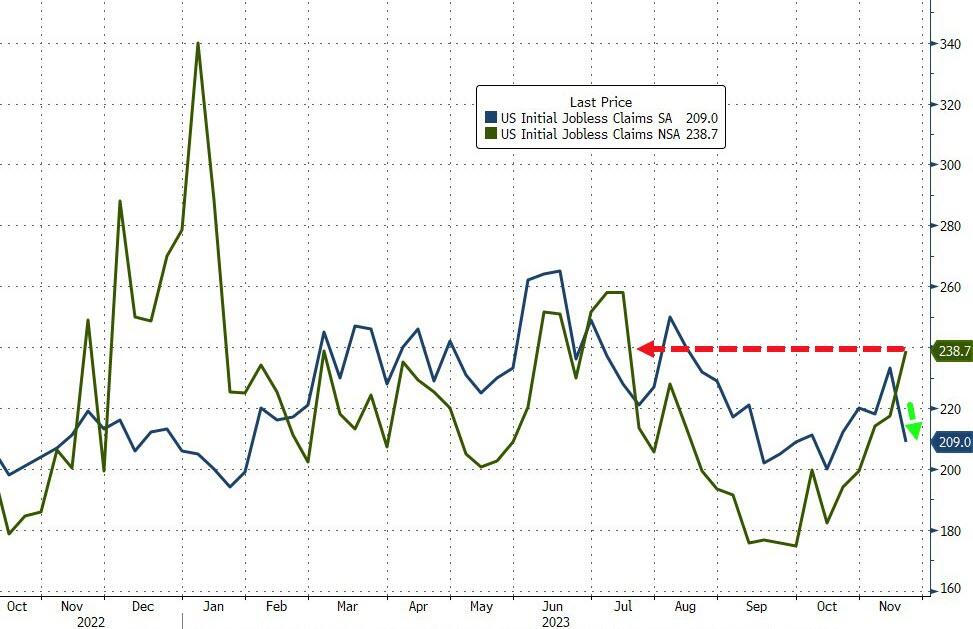
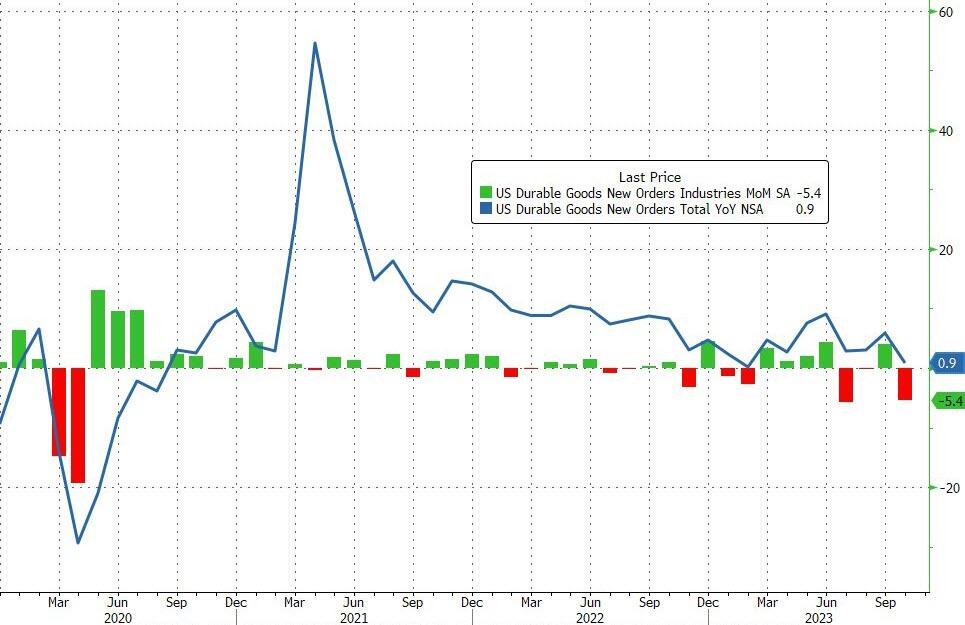
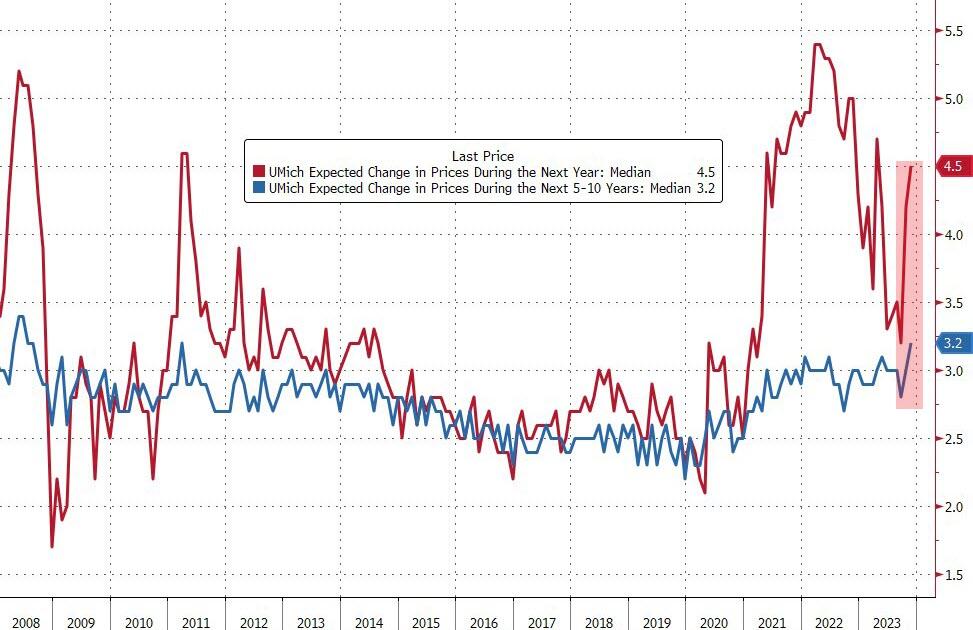
The economic data was not very encouraging, as jobless claims surged, durable goods orders slumped, consumer sentiment dipped, and inflation expectations rose. These indicators suggested that the US economy was losing steam and facing the risk of a hard landing.

The dollar tried to rally on the back of the Fed’s minutes, but failed to sustain its momentum and ended the day lower. Gold also struggled to hold on to its $2k level, as investors preferred riskier assets.

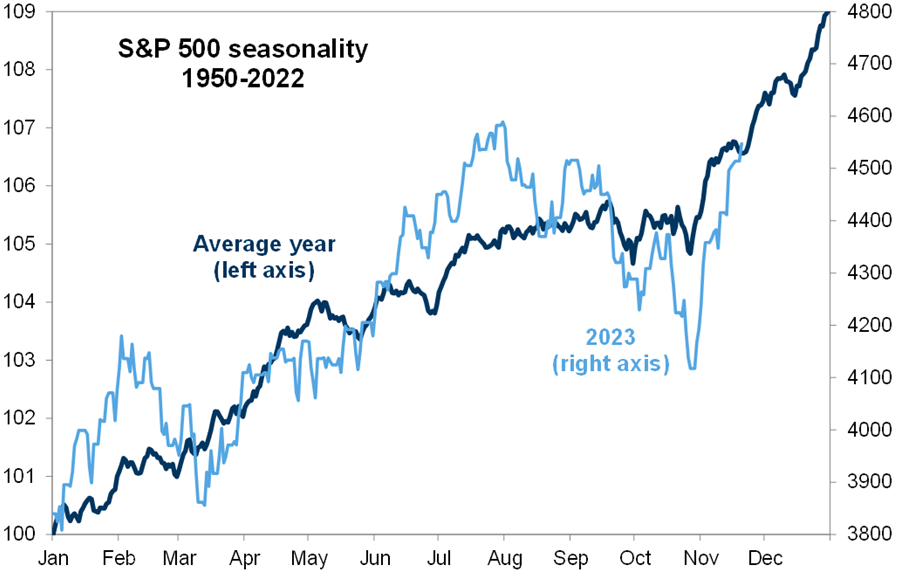
The S&P 500 followed its seasonal pattern and rebounded from its October lows, catching up with its historical average. The index is now within striking distance of its all-time high, as it heads into the Thanksgiving holiday.

I will be taking a break from writing these summaries until next Monday, so I hope you enjoy your turkey and cranberry sauce.

Read More

Fed Stays Firm On Rates, Markets Stay Hopeful For Cuts

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the markets 

The Fed dashed the hopes of traders who were looking for some hints of interest rate cuts in the latest meeting minutes. Instead, the central bank said it would keep its policy “restrictive” to tame inflation, which could rise further. The Fed kept the interest rate unchanged at 5.25% to 5.5% in its meeting on Oct. 31-Nov. 1.

“Participants continued to judge that it was critical that the stance of monetary policy be kept sufficiently restrictive to return inflation to the Committee’s 2 percent objective over time,” the minutes said.

That sounds pretty hawkish, but the market is still betting on rate cuts starting from May next year. Is that wishful thinking or realistic expectation? History suggests that the Fed usually waits for about 11 months after the last rate hike before cutting rates again. And the last rate hike was in December 2022.
Meanwhile, the economy is showing signs of slowing down, as some major retailers lowered their sales outlooks and missed revenue expectations. Lowe’s stock price fell more than 2%, Best Buy dropped 2.7%, and American Eagle plunged 17.3%. Ouch.
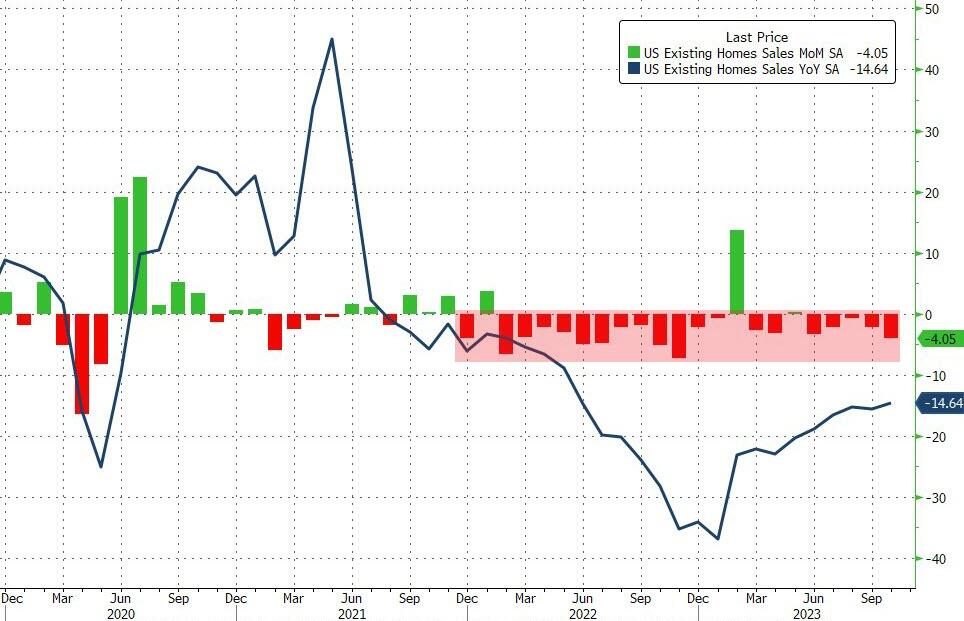
The housing market is also cooling off, as existing home sales hit their lowest level since 2010 and reached a record low in the West. This dragged down the US Economic Surprise index and the Financial Conditions index, which measure how the economy is performing relative to expectations and how easy it is to borrow money.

The stock market retreated, as the short squeeze that lifted the market yesterday ran out of steam and the big tech stocks gave up some of their recent gains. The bond market was mixed, the dollar bounced back, but gold shone brightly and reclaimed its $2k level.

All eyes are now on Nvidia’s earnings report tonight, which could be a make-or-break moment for the chipmaker. Will it follow the footsteps of its rivals AMD and Intel, which reported disappointing results amid the global chip shortage? Or will it surprise the market with strong growth driven by its gaming and data center segments?

Read More