Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 01/03/2013

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, January 3, 2013

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 10/25/2011

The domestic TTI broke through its long-term trend line generating a Sell for this area effective 8/9/2011. Over the recent past, we’ve seen the TTI hovering slightly below and above this dividing line between bullish and bearish territory. The clear break to the upside occurred on 10/24/11 and, effective 10/25/11, a new Buy signal for domestic equities went into effect.

As of today, our Trend Tracking Index (TTI—green line in above chart) has bounced off its long term trend line (red) by +2.35% after recently having dipped slightly below it.

To avoid a potential whip-saw, a Sell signal to move out of all domestic equity positions will be generated once we have clearly pierced the line to the downside. Be sure to tune into my blog for the latest updates.
Read More

Fed Minutes End Euphoric Rally; Europe Rises

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

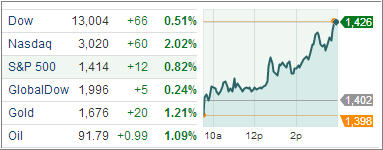
US equities slipped slightly following the S&P 500 index’s biggest rally in a year as minutes from the Fed’s December meeting showed some policy makers were mulling whether to wrap-up its $85 billion monthly bond purchase program before the end of this year.

What that means is that QE punch bowl addicted crowd may no longer have the Fed to support the relentless and economically disconnected rise of the major market indexes.

Plans were announced to expand the stimulus program in mid-December until the unemployment rate fell below 6.5 percent or inflation exceeded 2.5 percent. Minutes from the latest Federal Open Market Committee showed policy makers are likely to end their monthly bond purchase program sometime in 2013.

Read More

Cliff Deal Reached—But Where’s The Meat?

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

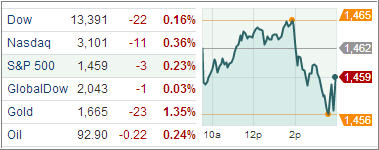
Sure, the much feared slide down the fiscal cliff was avoided at the last minute, but the euphoric relief rally in the markets will likely be temporary in nature. Last time the S&P 500 gained some 60 points in 2 trading days, over 70% of it was given back within the next week.

Upon closer inspection of the last minute deal, and as was to be expected, the serious issues like budget cuts, were simply ignored. This watered down bare bones agreement will raise taxes for some 70% of the population and benefit maybe 20% of them.

In other words, the insanity continues, as we’re now heading towards the debt ceiling talks, which will have to be finalized by sometime in March, since we already have pierced the ceiling on the last day of 2012. The $15 billion or so allocated to debt reduction is nothing more than a joke when considering the fact that we are spending $1 trillion a year more than we are taking in.

As a consequence, that cliff deal had no meat anywhere and, absent serious reconsideration, the next generation(s) will be chewing on a bare bone attempting to pay off insurmountable debt.

Read More

7 ETF Model Portfolios You Can Use – Updated through 12/31/2012

Ulli Model ETF Portfolios Contact

A roller coaster ride best describes the market activity of the past week, during which the S&P 500 gave back 4 points as the fiscal cliff ‘on-and-off’ negotiations pushed the benchmark index all over the chart.

In the end, it was a year during which equities came out ahead while balanced portfolios lagged behind. Our best model ETF portfolio performer turned out to be #5 with a solid +12.33%.

Since we are still in a buy mode, according to my Trend Tracking Indexes (TTIs), all models will be rebalanced as of 12/31/12 and the first update for 2013 will be Wednesday, January 9.

The Ivy portfolio (#6) will be discontinued and be replaced by a bond portfolio, which many readers had requested. If a bond portfolio is of interest to you, be sure to tune in on 1/9/13.

Here’s the last update for 2012:

Read More

Postponing The Inevitable

Ulli Market Commentary Contact

As I pointed out yesterday, the hard decisions in regards to the fiscal cliff negotiations have not been made and who knows, how and if they ever will be addressed once we step into 2013.

For some food for thought on this topic, Mark Grant, author of Out of the Box, had some worthwhile comments in “Postponed:”

“Postponed” is the official stamp across the world. This is the operative word of governmental policy. Whether Europe or America, whether capitalist or socialist government; this is the credo, the banner, the flag waving in the wind for dealing with economic problems.

Throw more money at it and barrels of it, have the central banks print and defer any pain much less any tough decisions. We live in a state of postponement, defer and delay which cancels the consequences of the moment but places more severe consequences, greater pain and tougher choices but moments out into our future.

Make no mistake; the world has become a more dangerous place either haunted by the specter of rampant inflation or haunted by valuations of debt and currencies that could turn the financial markets into a swirl of dislocation where a plunge into a freezing sea of disarray awaits as capital goes to gold, senior debt regardless of yields and nations deemed to be safe havens.

Grant’s first ten Rules, “Preservation of Capital” may exceed their present definition as they become all that is important and not just one of the considerations for making investments. Look about you, consider with care, what has been fixed and the honest answer, the truthful answer is Nothing. Greece is no better, Spain is no better, Portugal is no better and America is worse. Nothing has been fixed! Nothing!

Read More

Going Off The Cliff, But…

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

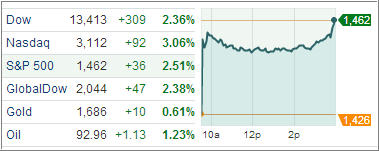
It was another day marked by confusion, last minute agreements that a fiscal cliff deal had been reached only to be followed by announcements that nothing had been finalized, but talks were still going on, etc., etc. It was insanity at its finest…

In the end, hope prevailed that a deal is still possible, which pushed the major indexes higher into the close. But, we are going off the fiscal cliff anyway at the end of this day when 2012 ends.

However, there is always that chance that some kind of agreement could be still emerging in early January and, if all parties agree, made retroactive to 1/1/13. I won’t hold my breath for that one, but market behavior tells us that this will be so. Given that, what could possibly go wrong?

Read More