Precious Metals Pop As Middle East Tensions Stir Safe-Haven Demand

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the market

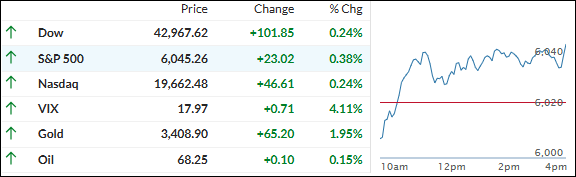
Stocks started the day in the red but quickly turned things around, climbing out of the early dip and finishing solidly in the green. The major indexes all pushed above their breakeven lines, riding a wave of renewed optimism.

Fueling that positive vibe was the May Producer Price Index (PPI), which came in cooler than expected—up just 0.1% after a 0.2% drop in April. Economists were bracing for a 0.2% rise, so this softer number gave investors a bit of relief on the inflation front.

Still, Wall Street isn’t breathing easy just yet. Trade tensions between the U.S. and China remain front and center. President Trump hinted at flexibility on the July 8 deadline for new tariffs, not just with China but with other trading partners too. That’s keeping markets on edge.

Looking ahead, the big question is whether we’ll see a breakthrough on tariffs. A resolution could be the spark that sends markets to new highs—especially if it aligns with budget talks and the Fed’s next move. Without it, we might just drift sideways in a fog of uncertainty.

Adding to the mixed signals, Trump said the U.S. is “fairly close” to a deal with Iran—then followed it up with a cryptic comment about “something possibly happening soon in the Middle East.” Not exactly reassuring.

Despite all that, the Dow and S&P 500 managed to close at their intraday highs. The 10-year Treasury yield hit session lows, and Bitcoin also dipped—though without any clear reason.

Meanwhile, precious metals had a strong day, with gold bouncing back from recent losses and silver rebounding after slipping below $36.

With geopolitical tensions simmering, especially in the Middle East, could gold and silver be the safe havens investors turn to next?

Read More
From Calm To Chaos: Inflation Eases, But Markets Can’t Catch A Break

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the market

Early gains came after cooler-than-expected inflation data and news of a preliminary trade deal between the U.S. and China. The Consumer Price Index (CPI) rose just 0.1% in May—below the 0.2% forecast—and core CPI (excluding food and energy) matched that soft reading.

This suggests tariffs haven’t had a major immediate impact yet. Companies may still be working through existing inventory or hesitating to raise prices amid shaky demand.

With a 90-day pause on new tariffs, traders are shifting their focus to inflation and jobs data. If inflation stays tame—or if the job market starts to weaken—hopes for a rate cut could gain traction.

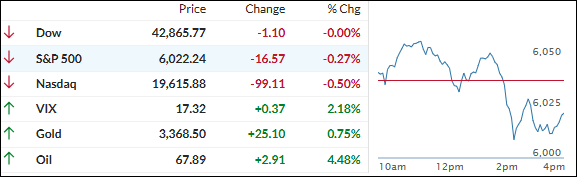
But the optimism didn’t last. Midday, markets reversed course after Treasury Secretary Bessent hinted at extending the tariff deadline, and tensions in Iraq flared up again. By the close, only the Dow managed to break even.

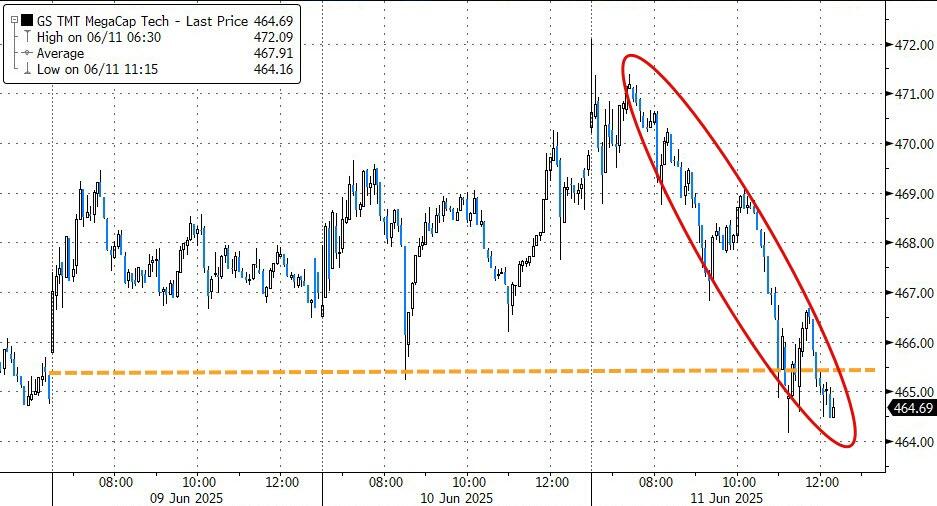
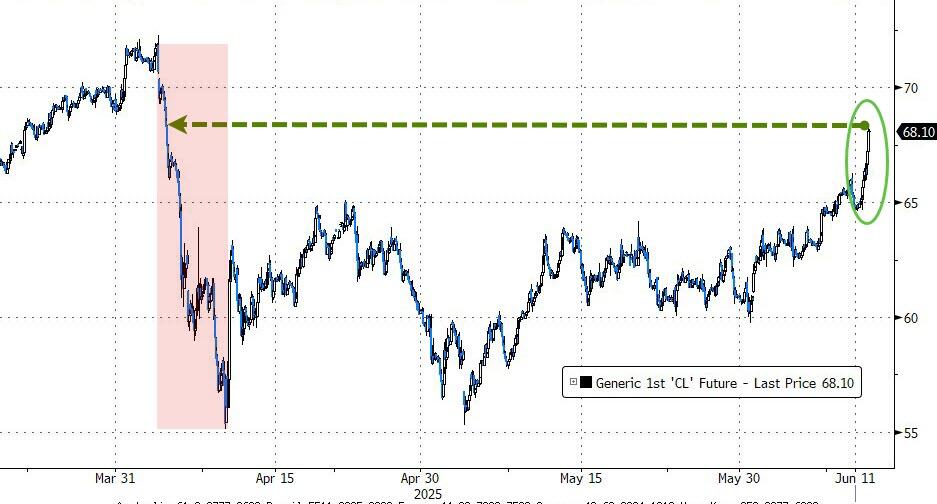
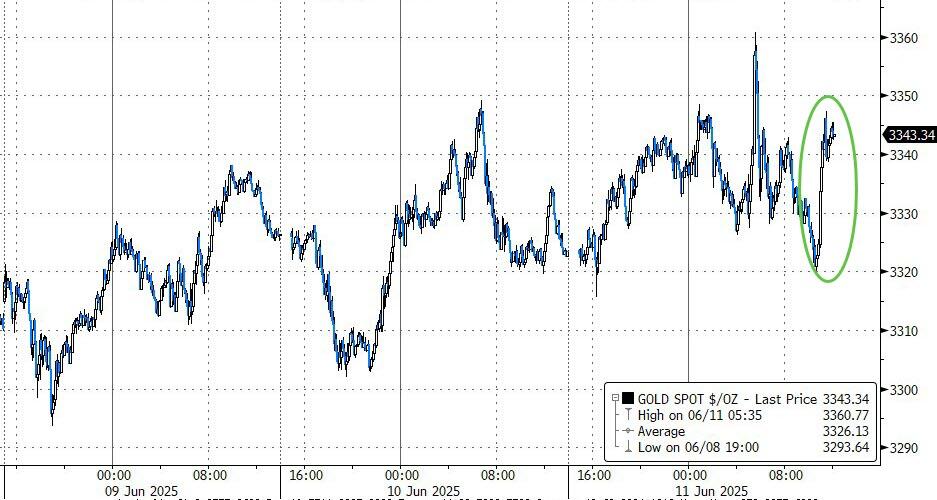
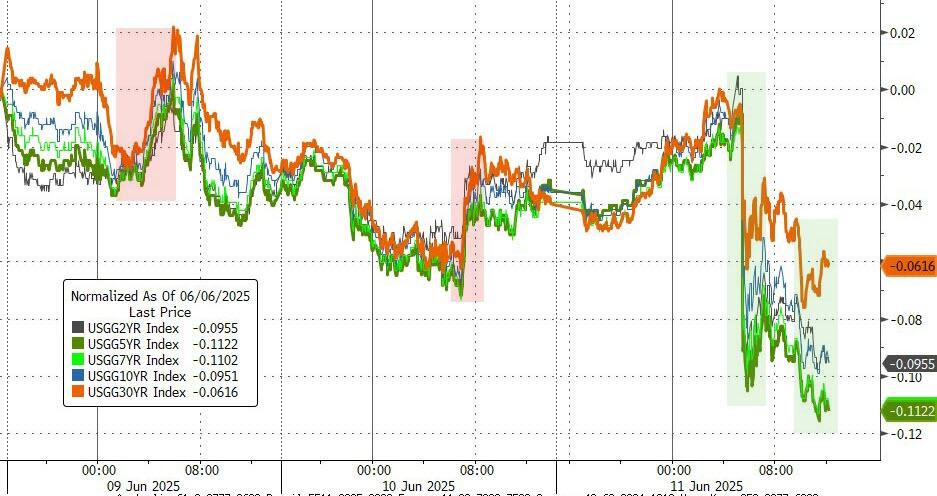
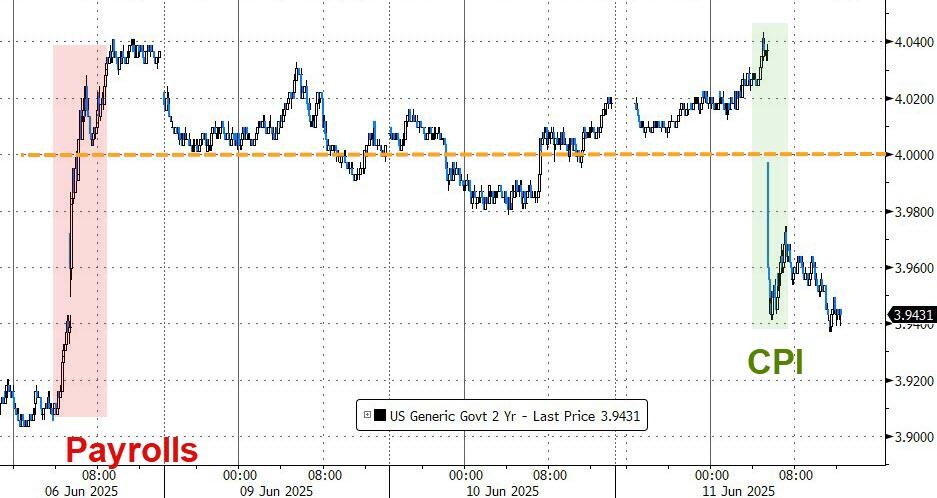
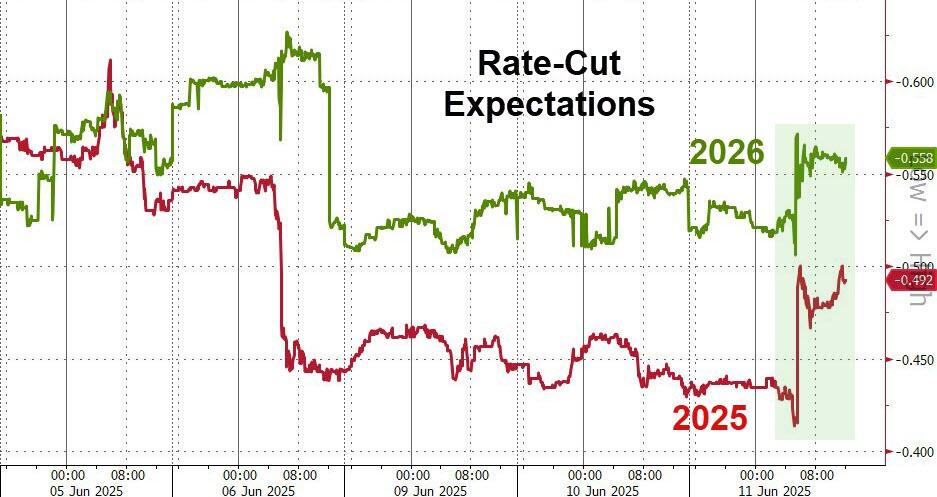
Mega-cap tech stocks slipped into the red for the week. Crude oil surged on renewed Middle East worries, gold jumped, and bond yields dropped as investors sought safety. The 2-year yield fell below 4%, boosting rate-cut expectations.

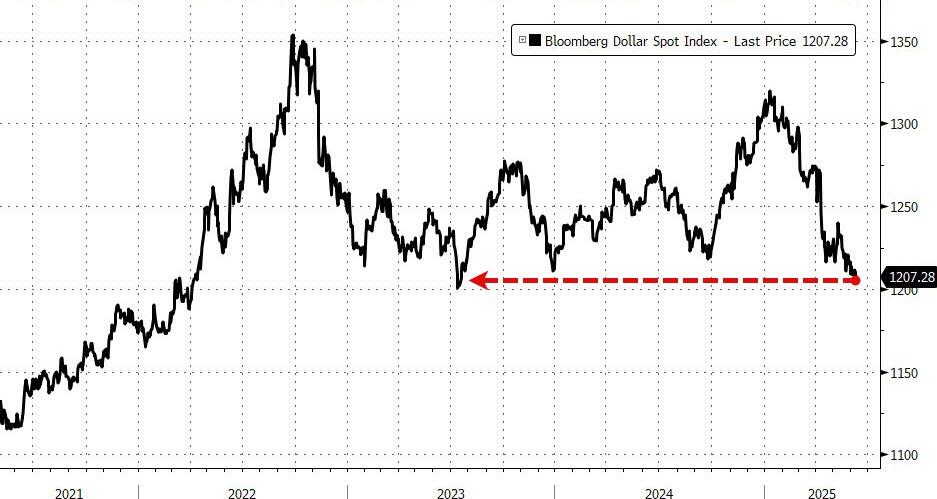
Meanwhile, the dollar took a hit, falling to its lowest level since July 2023.

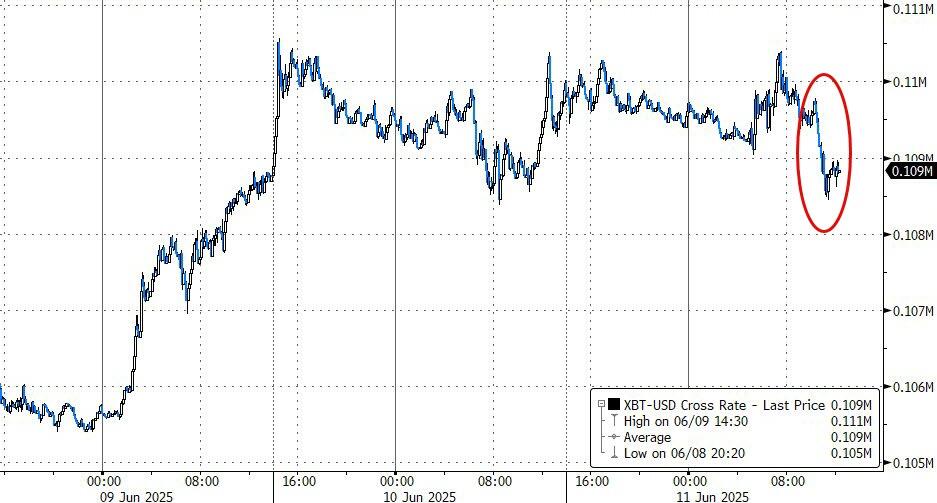
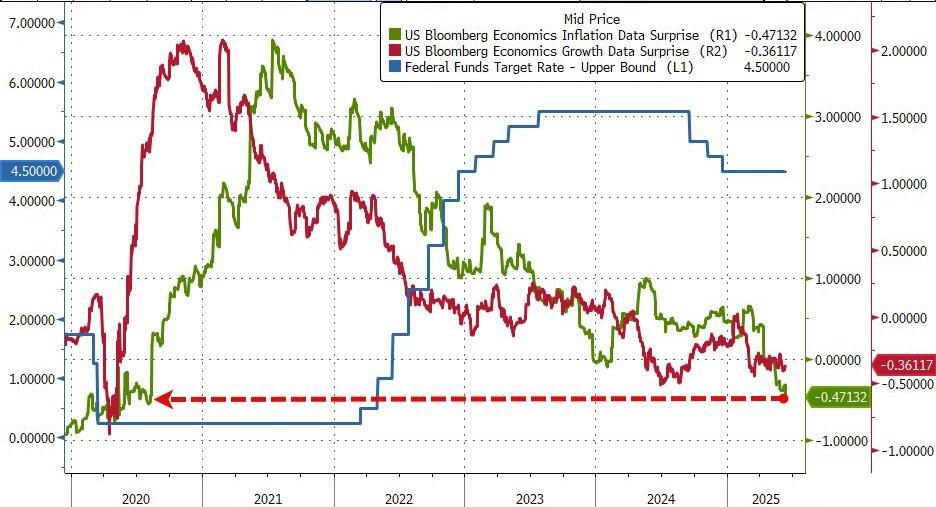
Bitcoin dipped but found support around $109K. And with the soft CPI print, the U.S. inflation surprise index hit its lowest level since August 2020.

So, with inflation cooling and markets on edge—what’s the Fed waiting for?

Read More

Short Squeeze Lifts Stocks, But CPI Looms Large

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the market

The markets opened slightly higher again today, echoing yesterday’s start, but didn’t show much follow-through as traders stayed cautious, waiting for more clarity on U.S.-China trade talks.

The discussions in London rolled into a second day, with Commerce Secretary Lutnik sounding optimistic, saying things are “going very well” and that both sides are spending a lot of time together.

Still, traders are hoping for more than just friendly chatter—they want to see real progress, especially around reducing tariffs, not just pausing them like last month.

For now, it seems like some dialogue is better than none, but whether it’s moving the needle is still up in the air.

Trading stayed mostly rangebound, with the S&P 500 and Nasdaq bouncing around but leaning higher into the close, helped by another short squeeze.

Midday, the 10-year yield spiked briefly after Trump warned that Iran is becoming “much more aggressive” in nuclear talks, but yields, the dollar, and gold all ended the day pretty much flat.

Gold managed a tiny gain, while Bitcoin made a late-day surge toward the $110K mark, and Ethereum climbed to its highest level since mid-February.

Now, all eyes are on tomorrow’s CPI report.

Will inflation come in cooler than expected—and give the market something real to rally on?

Read More

Silver Surges, Apple Slips, And Crypto Comes Alive

Ulli Market Commentary Contact

[Chart courtesy of MarketWatch.com]

  1. Moving the market

The markets kicked off the day on a mixed note as U.S. and Chinese officials met in London, hoping to make headway on their ongoing trade disputes.

The talks stemmed from a lengthy phone call between Trump and Xi last week, with both sides aiming to avoid a full-blown trade war. As a goodwill gesture, both countries agreed to temporary tariff cuts last month while negotiations continue.

Investors are also keeping a close eye on inflation this week. The Consumer Price Index (CPI) drops Wednesday, followed by the Producer Price Index (PPI) on Friday, and a fresh read on Consumer Sentiment.

Midday optimism didn’t last long—stocks lost steam by the close, with only the Nasdaq managing a modest gain. Apple shares slipped after its much-anticipated developer conference failed to impress.

The dollar didn’t budge, but crypto made a move. Bitcoin surged over 4%, climbing toward $109K and pulling Ether up with it.

In the bond market, 10-year yields stayed flat after last week’s surge. Gold inched up slightly, but silver stole the spotlight, jumping to nearly $37—its highest level since 2011.

As ZeroHedge noted, if silver clears that level, the path to its all-time high of $50 might be wide open.

So, here’s the big question: 

Is silver finally ready to shine after all these years?

Continue reading…

2. Current domestic “Buy” Cycle (effective 5/20/2025); International “Buy” Cycle (effective 5/8/25)

Our domestic bullish cycle that began on November 21, 2023, concluded on April 3, 2025, following a market downturn triggered by President Trump’s tariff policy announcement.

This development caused significant declines across major indexes and broader market indices. However, markets subsequently rebounded, culminating in a new domestic “Buy” signal taking effect May 20, 2025.

Concurrently, our International Trend Tracking Index (TTI) experienced parallel volatility. On April 4, 2025, it breached critical thresholds, prompting a “Sell” recommendation. This position reversed as global markets recovered, with the International TTI regaining sufficient momentum to issue a new “Buy” signal effective May 8, 2025.

3. Trend Tracking Indexes (TTIs)

With no real progress on a U.S.-China trade deal, the markets drifted through the day without much direction. By the close, there wasn’t a whole lot to show—no big gains, no major losses.

Our TTIs bounced around a bit too, but in the end, the changes were pretty minor and didn’t really move the needle.

This is how we closed 06/09/2025:

Domestic TTI: +1.56% above its M/A (prior close +1.55%)—Buy signal effective 5/20/25.

International TTI: +6.66% above its M/A (prior close +6.87%)—Buy signal effective 5/8/25.

All linked charts above are courtesy of Bloomberg via ZeroHedge.

———————————————————-

WOULD YOU LIKE TO HAVE YOUR INVESTMENTS PROFESSIONALLY MANAGED?

Do you have the time to follow our investment plans yourself? If you are a busy professional who would like to have his portfolio managed using our methodology, please contact me directly to get more details.

ETFs On The Cutline – Updated Through 06/06/2025

Ulli ETFs on the Cutline Contact

Do you want to know which ETFs are hot and which ones are not? Then you need my High-Volume ETF Cutline report. It tells you how close or far each of the 311 ETFs I follow is from its long-term trend line (39-week SMA). These are the ETFs that trade more than $5 million a day, so they are not some obscure funds that nobody cares about.

The report is split into two parts: The winners that are above their trend line (%M/A), and the losers that are below it. The yellow line is the line of shame that separates them. You can see how many ETFs are in each group and how they have changed since the last report (181 vs. 186 current).

Take a peek:

The HV ETF Master Cutline Report

If you are confused by some of the terms we use, don’t panic. I have a helpful Glossary of Terms for you.

If you want to learn more about the Cutline method and how it can make you rich (or at least less poor), read my original post here.

ETF Tracker Newsletter For June 6, 2025

Ulli ETF Tracker Contact

ETF Tracker StatSheet          

You can view the latest version here.

GOLDILOCKS JOBS REPORT LIFTS MARKETS—BUT INFLATION CLOUDS LOOM

[Chart courtesy of MarketWatch.com]

  1. Moving the market

The much-anticipated May jobs report landed with a bit of a surprise—U.S. payrolls rose by 139,000, beating expectations of 125,000.

While that’s a step down from April’s revised 147,000, it wasn’t enough to push the Fed into action. Unemployment held steady, and the labor market still looks pretty balanced.

Markets loved it. The S&P 500 broke back above the 6,000 mark for the first time since February, and the Dow finally clawed its way out of the red for 2025.

Tesla helped fuel the rally, bouncing nearly 4% after Thursday’s 14% nosedive. Big tech names like Nvidia, Meta, and Apple also chipped in with modest gains.

Earlier in the week, some data hinted at a possible economic slowdown, raising questions about how ongoing tariff talks and the Fed’s next move (June 17–18) might play out. For now, rate-cut hopes have cooled. Trump called for a full-point cut, but traders aren’t buying it.

A short squeeze added extra juice to the rally, especially for the Mag7 stocks, which continued to outpace the rest of the S&P 500. Small caps and the Nasdaq led the charge for the week.

Bond yields jumped on the strong jobs data, lifting across the board. The dollar, despite Friday’s bounce, logged its weakest weekly close since July 2023. Gold pulled back slightly at the close but still managed a small weekly gain.

Bitcoin dipped a bit over the past five sessions, briefly testing $101K before rebounding toward $105K.

One thing that stood out: a growing divergence between global liquidity and the S&P 500.

Some analysts, including those at ZeroHedge, see this as a sign of potential central bank reflation. Translation? More inflation could be on the way.

So, here’s the big question: Are you positioned for a world where inflation might be making a comeback? Got gold, silver, or crypto in your corner?

Read More