1. Moving the Markets
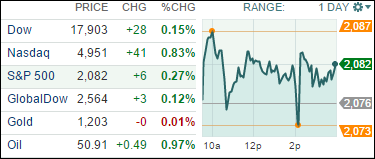
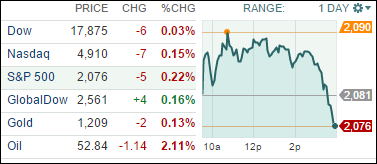
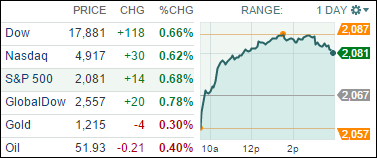
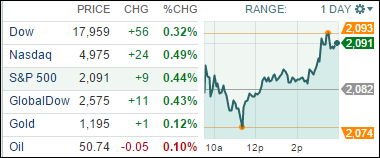
Gains were led mostly by energy stocks as oil prices rebounded slightly after Wednesday’s steep decline. U.S. benchmark crude rose 0.7% to $50.84 a barrel after plunging 6% the previous day on a larger-than-expected inventory build-up.
In tech, shares of Altera (ALTR) rose and Intel (INTC) fell on reports that Intel has ended talks to buy the semiconductor company. In auto news, we heard today that General Motors (GM) is halting production of the Chevy Volt extended-range electric car, because they need to clear out an unsold backlog. Volt sales the first quarter this year are just less than half what they were a year earlier.
The sale of these electric toys, of course, relates directly to the price of gas. With gas prices low so far this year, there has been a large financial disincentive to buy alternative-power vehicles.
And finally, a fun bit of buzz on the street today is that private equity firm Blackstone Group and Wells Fargo are close to a deal buy a real-estate portfolio valued at a whopping $30 billion from General Electric (GE). This has not been confirmed as of yet, but if the transaction did go through, it would be one of the largest real estate deals since pre-financial crisis of 2007.
7 of our 10 ETFs in the Spotlight inched higher while 3 of them dropped. Leading the charge to the upside was Healthcare (XLV) with +0.75%, while SPLV ruled the downside with a slight loss of -0.24%.