1. Moving the Markets
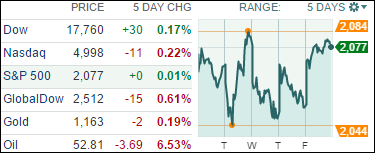
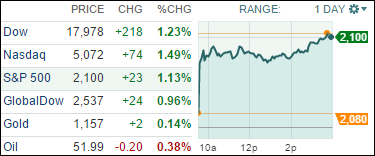
The bulls had their way as the rally continued for the third straight day with the S&P 500 reclaiming the 2,100 level. The driver was a new agreement, where Greece ended up in total capitulation by giving up much sovereignity in turn for a third bailout program.
This type of deal came as a total surprise but before in can be finalized it must be approved by the national parliaments, which is expected to happen by the end of the week. Optimism persists that Greece will accept all conditions and thereby remain in the Eurozone. As a consequence, the markets are back in “risk on” mode.
Domestically, earnings will be on the menu for the next few weeks, and so far there have been no surprise announcements that companies may disappoint. If that holds, equities could be finding more support.
All of our 10 ETFs in the Spotlight participated in this rally and closed solidly higher. The leader for the day was Consumer Discretionaries (XLY), which gained 1.44%. On the laggard side, but still gainging nicely, was the Dividend ETF (DVY), which captured 0.69%.