1. Moving the Markets
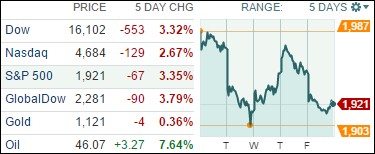
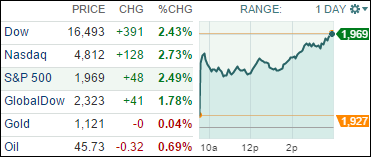
The sharp swings on Wall Street continued Tuesday, with stocks surging as traders returned from the 3-day holiday weekend and sent the Dow up 390 points. The gains came after last week’s volatile downturn that saw all the major indexes drop more than 3%, capped off by the Dow’s 272-point drop on Friday after a mixed jobs data report did little to clarify what the Federal Reserve will do on interest rates at its September meeting. The S&P 500 is now back to where we started this month.
China has been at the forefront of most market volatility of late. Well, today U.S. stocks rallied despite more disappointing economic data from China, because the news sparked hopes that the country’s central bank would take more action to stimulate the economy. The report today showed that China’s imports shrank far more than expected in August, falling for the 10th straight month. This may seem sour on the surface, but in reality it could lead to further policy easing from the Chinese government in coming months. The Chinese government has already intervened to keep their domestic stock markets afloat recently and this could be another time when we see them flex their fiscal muscle if import and export data continues to waver.
In uplifting news today, shares of the beloved U.S. powerhouse General Electric (GE) gained 4% today after the company won European and federal approvals for its $9.5 billion deal to buy French multinational Alstom’s power business. GE initially anticipated the value of the deal to be $13.5 billion; however, the closing purchase price is expected to be around $9.5 billion.
I am curious to see if today turns into another dead cat bounce or if a resumption of the bullish trend is in the making.
Today’s rebound pushed all of our 10 ETFs in the Spotlight higher by a solid margin. The leader of the day was Healthcare (XLV) with +2.80% while Consumer Staples (XLP) lagged a bit but added +2.09%.