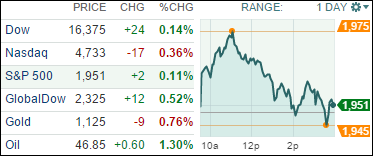
1. Moving the Markets
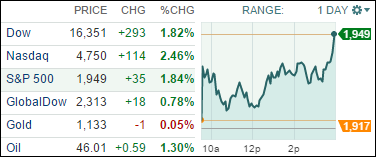
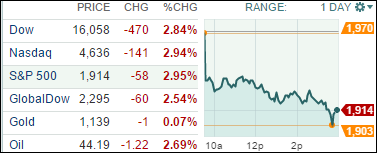
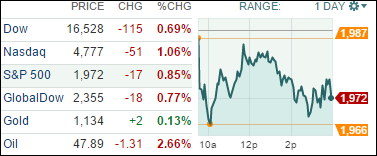
Equities closed mixed today as an early rally on Wall Street slowly faded and gave back strong gains. Stocks jumped early in the trading session after yesterday’s big rebound, as Wall Street digested favorable data on the services sector of the U.S. economy and reassuring comments from the European Central Bank. It seems though that investors are remaining cautious in anticipation of a key reading on U.S. employment that will be released tomorrow.
A lot is riding on this employment report, as a very strong report could give the Fed further ammunition to raise short-term interest rates for the first time in nearly a decade. Despite warnings from the IMF that the Fed should hold off on hiking rates, a continuation of good economic data in the U.S. will make the Fed’s decision that much more difficult.
In the tech world, Apple (AAPL) fans and investors both are gearing up for an Apple product unveiling next week. Most speculate that the unveiling will entail a new iPhone model, possible the 6S and 6S Plus. According to FactSet, analysts expect Apple will sell about 235 million iPhones in its upcoming fiscal year, which starts in October, up from 231 million in the prior year.
As you know, according to my Trend Tracking Indicators (TTIs), we are stuck in bear market territory and therefore positioned safely on the the sidelines. There are a variety of ways to determine a bear market and, one of my favorite writers, David Stockman, makes a case that “This Is Not A Retest—It’s A Live Bear!” It’s a great read.
9 of our 10 ETFs in the Spotlight were able to post gains in light of this roller coaster day. Taking top billing was Consumer Staples (XLP) with +0.68% while Healthcare (XLV) lagged with -0.71%.