1. Moving the Markets
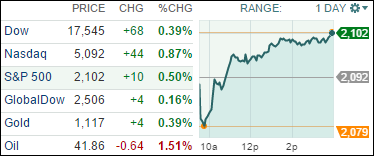
The major indexes overcame an early drop, with the S&P 500 visiting the 2,079 level, at which point the bulls took over and managed to push the index back above the 2,100 mark.
Homebuilders were the leaders, although volume was extremely light with anxiety being present about the intentions of the Fed as to their stance on interest rates. We continue to be stuck in a tight trading range and need some sort of driver to provide new upside momentum.
Concerns about China have eased somewhat so the focus has been on the economy and what the Fed might or might not do. If they decide to become more transparent in their intentions, we most likely will see an immediate market reaction. Should the Fed indicate that a rate hike for September is unlikely, whatever obscure language they might use to come to that conclusion, we could see the top of the trading range (around 2,130 for the S&P 500) being taken out with the next target being the 2,050 level.
All of our 10 ETFs in the Spotlight managed to close up with Healthcare (XLV) taking the lead by gaining +1.01%. Lagging today was Consumer Staples (XLP), which eked out a meager +0.10%.