One Man’s Opinion: Will Consumer Discretionaries Lead In Earnings Growth In Q3?

Ulli Market Review Contact

ManThe S&P 500, according to Estimize, is likely to see a negative earnings growth of 2-1/2 percent and revenues growth of negative 1.7 percent. In the last quarter, earnings growth expectations were 3.5 percent, but it ended up with about 1 percent. The peak-rate currently stands at about 66 percent for about 22 companies that have reported third-quarter results and companies do tend to beat expectations with going into the season.

But until now, all commodity-related stocks have slumped with energy EPS sliding 66 percent and materials losing about 5 percent. Globally, China is likely to remain a worry with the bursting of equity bubbles there and the effects are likely to be stronger than in the second quarter, she noted.

Asked which sectors are likely to perform well, Christine said consumer discretionary will be a winner since lower oil does benefit some sectors. Estimize expects the discretionary sector to record a 13.5 percent growth this quarter with a special focus on automobiles.

Read More

New ETFs On The Block: Vanguard Tax-Exempt Bond Index Fund (VTEB)

Ulli Municipal ETFs Contact

InvestingGoing by recent trends, about 200 new exchange-traded funds are launched in an average year. Vanguard, the second largest US ETF issuer after Blackrock’s iShares, however, remains conspicuously absent at most times despite managing $3.3 trillion in global assets.

Not any more after the Penn-based asset manager decided to break its long hiatus of more than two years with the launch of its first municipal bond index fund. That may sound a little strange since its competitors like iShares and State Street Global Advisors launched their muni-bond portfolios way back in 2009 and now offers a suite of products with billions in assets.

The newly-launched Vanguard Tax-exempt Bond Index Fund (VTEB) tracks the S&P National AMT-Free Municipal Bond Index, and is the asset manager’s first passive, index-tracking product. Vanguard has a suite of more than 15 active muni funds and its tax-exempt bond fund portfolio has nearly $120 billion in assets.

Read More

ETF/No Load Fund Tracker Newsletter For October 9, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/10/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-10082015/

————————————————————

Market Commentary

MARKETS FULL STEAM AHEAD TO ROUND OUT RALLY
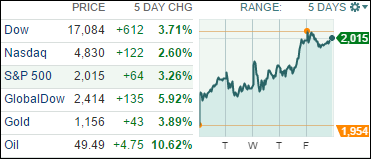
Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The Dow extended its recent rally to six sessions as stocks keep heading higher following the release of minutes of the Fed’s meeting last month that lowered investor expectations for an interest rate hike this year. It was all about the Dow this week as the index posted its best weekly advance since a nearly 660-point, 3.8%-run in early February. The S&P 500 also posted its largest weekly gain of 2015.

U.S.-produced crude was also higher, at one point climbing above the key $50 a barrel level and settling at a close of $49.51 a barrel.

Economic data was fairly light this week, so investors were able to key in on two major releases that included the international trade figures and the Federal Reserve Open Market Committee’s (FOMC) September meeting minutes. While international trade figures came in as expected, the release of the FOMC meeting minutes struck the market as dovish, implying that the Fed will continue to wait to raise interest rates.

Next week we have a full menu of economic data, which includes small business optimism figures on Tuesday, retail sales on Wednesday, inflation data on Thursday and industrial production and sentiment figures on Friday.

As for big earnings reports coming up next week, we will hear from four of the major financials, with JP Morgan (JPM), Wells Fargo (WFC), Citigroup (C) and Bank of America (BAML). Analysts say these groups will probably set a much better picture of what the rest of the earnings season can look like. We will also hear from Netflix (NFLX).

Remember going into next week that analysts’ expectations for the Q3 earnings season are low, expecting profits of S&P 500 companies to contract about 4%. But the low bar can potentially be a bullish development, as it makes it easier for companies to top analysts’ ridiculous expectations.

It was a mixed day with 5 of our 10 ETFs in the Spotlight rallying and 5 of them declining. The leader turned out to be Healthcare (XLV) with +0.46% while on the losing side the Financials (IYF) ended down with -0.48%.

Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 10/08/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, October 8, 2015

TOC 090315

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


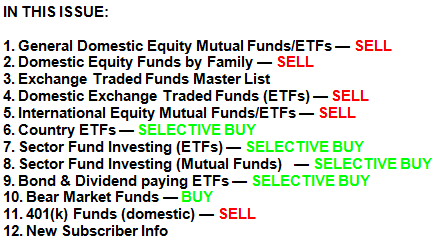
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: SELL — since 8/24/2015

TTI

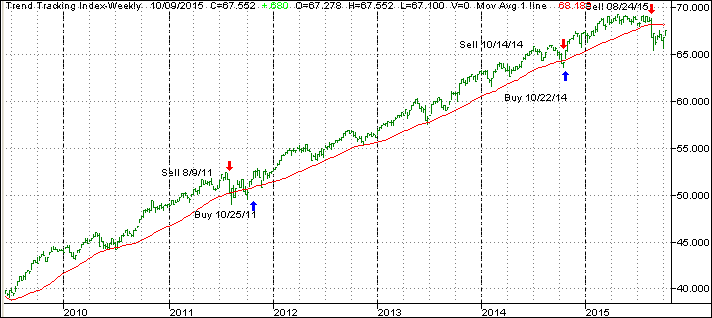
Our main directional indicator, the Domestic Trend Tracking Index (TTI), broke through its long-term trend line generating a “Sell” for this arena effective 10/14/2014, which was followed by a violent break back above the line on 10/22/14 generating a new “Buy.” It was a classic whipsaw signal, and you can read more on my blog as to the events as they were unfolding.

As of today, our TTI (green line in above chart) is positioned below its long term trend line (red) by -0.91% after having generated a “Sell” signal as of 8/24/2015, which applies to all “broadly diversified domestic equity ETFs/Mutual Funds.”

Read More

Rally Continues On Wall Street; Alcoa Disappoints

Ulli Market Commentary Contact

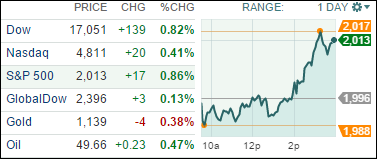
Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

The stock rally on Wall Street picked up steam Thursday as investors focused on the Federal Reserve’s continued worries about low inflation after the release of minutes from the Fed’s latest policy meeting.

The Dow and S&P 500 had earlier flirted above and below the break-even marks of 17,000 and 2,000. But after reviewing the Fed minutes, in which the central bank said it was still worried about low inflation readings, stocks rallied as the odds for an interest rate hike this year seemed to shrink some more.

We have all been waiting for the earnings season to get underway. Today, Alcoa (AA) released its Q3 numbers not long after the closing bell. The results were disappointing. The company reported adjusted earnings per share of $0.07 ($0.13 estimated) and revenues of $5.6 billion ($5.64 billion expected), down 11% year-on-year. Alcoa is seen as a gauge for global manufacturing and as a big player in commodities. Its performance, comments on the markets and on China’s economy are telling.

All of our 10 ETFs in the Spotlight joined the party and closed up with the Mid-Cap Value being the winner with +1.25%. Lagging behind was Healthcare again (XLV) with +0.37%.

Read More

Stocks Close Higher Despite Morning Slide

Ulli Market Commentary Contact

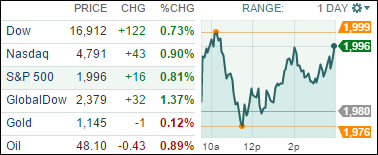
Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

After nosing into the red in late-morning trading, all three major benchmarks climbed back into the black to close the day. Analysts are eyeing the key 2000 level on the S&P 500 index, as that level now is viewed as a ceiling of sorts for stocks as they look to rebound further. A break above 2000 would boost hopes that the uptrend that began Friday has legs and that the market is regaining its bullish stance.

Today, traders were also bracing for the unofficial start of the third-quarter earnings season, which kicks off with very low expectations Thursday when aluminum maker Alcoa (AA) reports. For the third straight month, the profit-reporting season begins with Wall Street analysts predicting a contraction in earnings.

A possible market-moving event occurs Thursday, when the Fed releases the minutes of its September meeting. Stocks, of course, have been hurt by uncertainty surrounding the start of rate hikes, but have recently gotten a boost after Friday’s weak jobs report resulted in Wall Street pushing out the so-called Fed “lift-off” into early 2016.

It was a wild ride, but all of our 10 ETFs in the Spotlight participated in the reboud and closed higher. The leader of the day was Healthcare (XLV), which added +1.53%. Lagging the group was Consumer Discretionaries (XLY) with +0.31%.

Read More