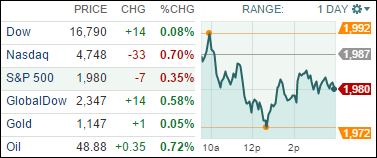
1. Moving the Markets
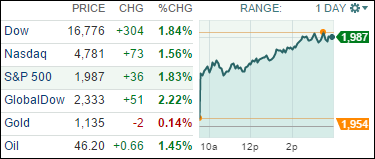
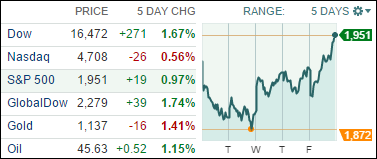
After a strong five-day rally that lifted the major U.S. stock indexes well off their lows hit in August, equities ended mixed as Wall Street reassessed the outlook for stocks for the rest of 2015.
Healthcare stocks led the decline in the S&P, while a rally in Dupont’s stock (DD) helped keep the Dow in positive territory. Healthcare stocks have had a tough year that is mostly due to the widespread scrutiny over high prices for pharmaceuticals.
Investors are still anxious in waiting for the earnings season to kick off later this week. At present, expectations are low, but many analysts think that this could actually be beneficial for the indexes if stocks outperform. It is a critical time to see how the markets will react to earnings reports, especially since the S&P 500 keeps flirting with the 10% correction status.
And in economic news, we heard today that the U.S. trade deficit jumped sharply in August as exports fell to the lowest level in nearly three years while imports increased, led by a surge in shipments of cellphones from China. The deficit increased 15.6% to $48.3 billion, the biggest since March, the Commerce Department reported Tuesday.
Only 2 of our 10 ETFs in the Spotlight managed to eke out a gain with the Global 100 (IOO) taking the top spot by adding +0.42%. The loser of the day turned out to be Healthcare (XLV) which got clobbered at the tune of -2.35%. Ouch.