ETF/No Load Fund Tracker Newsletter For December 4, 2015

Ulli ETF Tracker Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

THE LINK TO OUR CURRENT ETF/MUTUAL FUND STATSHEET IS:

https://theetfbully.com/2015/12/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-12032015/

————————————————————

Market Commentary

MARKETS PLOW HIGHER HEADING INTO SECOND WEEK OF DECEMBER
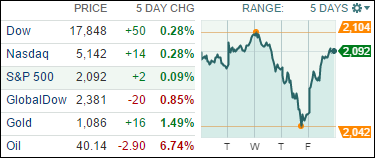
Fri pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

This week ended with a huge gain across the board. All major indexes gained more than 2% Friday to round out a very volatile week as the chart shows. December has traditionally been a favorable month for the stock market, and today’s gains show signs that the present could align with the past.

Earlier this week, I mentioned that investors would be awaiting Friday’s jobs report. Well, the numbers came in for November and they were impressive to say the least. The economy added 211,000 jobs in November, topping expectations of 200,000 and reaffirming the strength of the U.S. labor market and the economy. Also, the nation’s unemployment rate remained unchanged at 5%, which was in line with expectations.

The strong jobs growth adds even more reaffirmation that the Fed will hike interest rates later this month. But, one can never be certain in regards to how or when they will make a move.

There was no major news in the world of M&A today, apart from the fact that there is still speculation that Yahoo (YHOO) may be bought out sometime in 2016.

The price of U.S. Crude Oil fell slightly, but remains around $40 a barrel and there is no imminent sign that it will increase before 2016.

All of our 10 ETFs in the Spotlight participated in today’s snap rebound and closed higher. Sporting the best gain was Healthcare (XLV) with +2.35% while the Mid-Cap Value (IWS) lagged with +1.37%.
Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 12/03/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, December 3, 2015

TOC 111915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


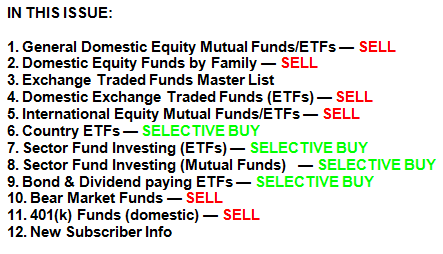
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: SELL — since 11/13/2015

TTI

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in above chart) has recently crawled above its long term trend line (red) and finally generated a new “Buy” signal effective 11/3/15. The market subsequently dropped, and we exited again on 11/13/15. As of today, the TTI remains below its trend line by -0.26%, which means we are in cash on the sidelines.

Read More

Markets Melt On ECB Results; Renminbi Now Elite; Domestic TTI Goes Negative

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

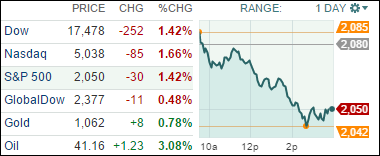
1. Moving the Markets

The S&P 500 index dropped back into the red for 2015, and the Dow ended down 252 points at 17,478 today after the ECB announced fresh stimulus efforts that didn’t meet the lofty expectations of investors.

It was all about Europe today, as ECB President Mario Draghi failed to deliver on the market’s hopes for a steep interest rate cut. The failure to give the EU market the amount of stimulus it hoped for caused the euro to spike against the dollar, a development that hinders the ECB’s ability to jump-start growth and boost “dangerously” low inflation. Let us not forget that a stronger euro makes European exports more expensive and less competitive.

On to China. China’s government praised this week’s decision by the IMF to add the yuan to the world’s elite reserve currencies, saying it was recognition of the government’s decades-long effort to reform its economy. The move by the IMF on Monday comes as China is at economic and financial crossroads. Slowing growth has pushed the ruling communist party to jettison the state-led development model and to advocate for a more market-driven, less interventionist system. The yuan will join the reserve currencies on Oct. 1, 2016, bringing the total number of currencies to five, along with the Japanese yen, U.S. dollar, British pound and euro.

Wall Street on Friday is poised for the November employment report. If the U.S. economy continued to create jobs at a solid pace last month, after producing a better-than-expected 271,000 jobs in October, it will likely cement a Fed rate hike on Dec. 16, barring any shocks between now and then.

To no surprise, all of our 10 ETFs in the Spotlight slipped with the indexes and closed lower. Healthcare (XLV) took top billing with -2.19% while Consumer Staples (XLP) showed the most stability by surrendering only -0.52%.

Read More

Stocks Sink Despite Solid Jobs Numbers

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

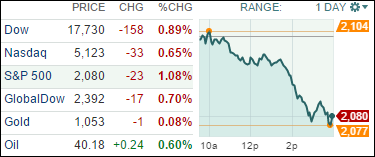
1. Moving the Markets

U.S. stocks were mixed most of the day, but then all three major benchmarks sank and finished down as news spread of a reported mass shooting in California. A standout amid the downturn was Yahoo (YHOO) as shares gained 5.8% on speculation the embattled tech icon may be acquired by an unspecified buyer.

In a midday Washington speech, Federal Reserve chair Yellen signaled that the Fed is all but certain to raise interest rates this month for the first time in nearly a decade, saying that gains in the economy and labor market have met the central bank’s goals.

Wall Street is still trying to discern if the health of the U.S. economy is vibrant enough to cope with rising rates, especially after yesterday’s reading on U.S. manufacturing in November, which contracted for the first time since the end of 2012. On the other side, in Europe, ECB chief Draghi is going the opposite direction by jawboning about another QE (Quantitative Easing) program for the region, which is surprising in that central banks usually coordinate and streamline their efforts.

Also, Wall Street also got the November reading on job creation in the private sector. The ADP report topped expectations, with private employers adding 217,000 jobs last month, which is above the 192,000 that had analysts had forecast.

Oil continues to stay at depressed prices. U.S. Crude Oil slid more than 4% to back to $40 a barrel, as inventories climbed.

In a reversal from yesterday’s session, all of our 10 ETFs in the Spotlight headed south as any follow through momentum to the upside was absent. Topping the list of losers was the Select Dividend ETF (DVY) with -1.54%. Resisting this sell-off the most were the Consumer Staples (XLP) with -0.50%.

Read More

Markets Kick Off December In A Jolly Mood

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

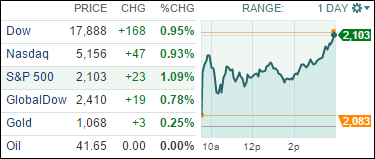
1. Moving the Markets

The all too familiar mantra pushed indexes higher with the S&P conquering the 2,100 level again. Equities rallied because economic outlook is fragile, bond yields are dropping, US manufacturing is extremely weak and suddenly the odds for a December rate hike are heading south. In other words, the markets rallied in the face of poor macro data. It almost seemed as if Wall Street expects another QE announcement by the Fed and not a rate hike. Go figure…

On the other hand, maybe markets just got into the Christmas spirit as all 3 major indexes gained about 1%. Historically, December has been a profitable month for stocks. In the past 100 years, December has ranked No. 1 in performance, posting an average gain of 1.46%, although gains have downsized to 1.37% in the past 20 years, according to Cap IQ.

Investors today seemed pleased with the results of Cyber Monday, which Adobe says is stacking up to be the “largest online sales day in history.” Adobe estimates that online sales yesterday totaled roughly $2.98 billion, a 12% increase over 2014 Cyber Monday sales.

The big event this December, of course, comes on Dec. 16, when the Federal Reserve breaks from its final meeting of the year and is expected to hike interest rates for the first time in nearly a decade. Wall Street is expecting short-term rates, currently pegged near 0%, to be increased by a quarter of a percentage point.

All of our 10 ETFs in the Spotlight followed the major indexes higher as Healthcare (XLV) took the lead by gaining +1.69%. Lagging the group was the Select Dividend ETF (DVY) with +0.74%.

Read More

Stocks Fail To Impress Post-Thanksgiving Holiday

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

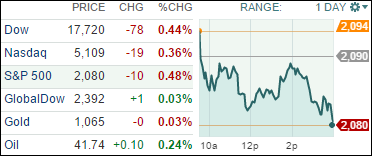
1. Moving the Markets

U.S. stocks traded modestly lower Monday as Wall Street kicked off a big week with investors eyeing Cyber Monday sales, a key bankers meeting in Europe Thursday that could result in more stimulus efforts and the monthly U.S. jobs report on Friday.

Heading into today’s trading session, which marks the final day of November, the broad S&P 500 stock index is up just 1.5% for the year and still down about 2% from its late May record close of 2130.82.

Black Friday and Cyber Monday sales will get their fair share of coverage this week, but so will a big batch of economic data, ranging from fresh readings on housing, manufacturing, vehicle sales, and factory orders. Perhaps the most anticipated piece of data will come on Friday, when we will hear the latest jobs report.

Many analysts are saying that if the U.S. economy, which generated a much-better-than-expected 271,000 jobs in October, can deliver another strong month of job gains, it will all but cement a Fed interest rate increase at the U.S. central bank’s last meeting of the year on Dec. 15-16.

All of our 10 ETFs in the Spotlight succumbed to today’s downward momentum and closed loser. Giving back the most was Healthcare (XLV) with -1.36%; holding up the best was the Mid-Cap Value (IWS) with -0.13%.

Read More