New ETFs On The Block: SPDR S&P 500 High Dividend ETF (BITE)

Ulli Dividend ETFs Contact

Investing

Domestic consumption and US consumer spending is likely to remain the dominant investment theme for 2016 as employee wages start to pick up and the wider economic recovery gains traction.

Moreover, cheap fuel and improving consumer confidence would likely lead to greater levels of disposable incomes, making the consumer discretionary sector a compelling proposition to stay invested in.

The restaurant industry – part of the consumer discretionary sector, has been the best performing segment in 2015 due to solid fundamentals, despite some headwinds. Research shows the Average American household spends more than $2,600 every year and eats at a restaurant more than five times a week. Needless to say, it was just a matter of time before some body spotted an opportunity in this oft overlooked but lucrative space.

Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 12/31/2015

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, December 31, 2015

TOC 111915

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


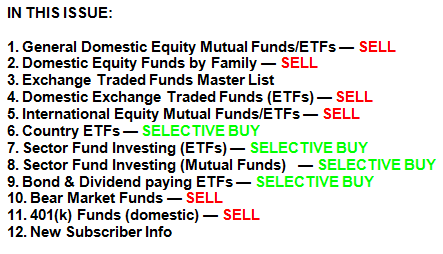
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: SELL — since 11/13/2015

TTI-12-31-15

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in above chart) has recently crawled above its long term trend line (red) and finally generated a new “Buy” signal effective 11/3/15. The market subsequently dropped, and we exited again on 11/13/15. As of today, the TTI remains below its trend line by -0.70%, which means we are in cash on the sidelines.

Read More

2015 Ends With An Ugly Close

Ulli Market Commentary Contact

Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

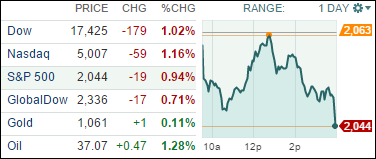
U.S. stocks closed out the final trading day of 2015 with both the Dow and S&P 500 suffering their first year of negative returns since 2008 when the financial crisis was in full swing. Both benchmarks were on the verge of a positive year at the start of today’s trading session, with the Dow needing a sizable, 219-point gain to hit break even. However, it wasn’t meant to be today, as all three major indexes fell about 1% or more and closed at their lows. The Nasdaq reigned supreme for 2015, posting final annual gains of 5.7%, while the S&P 500 and Dow ended the year down about 1%. Oil was by far the biggest loser this year, with the price of U.S. Crude dropping a whopping 30.5%.

It’s been an up and down year on Wall Street. After hitting record highs in May, the stock market suffered its first correction, or drop of 10% or more, back in August. And while the market has rebounded from its summer lows, all three of the major U.S. indexes are still around 3% to 4% off their peaks.

Stocks have been held back throughout the year by uncertainty surrounding interest rate policy, as the Federal Reserve hiked borrowing costs earlier this month for the first time in nearly a decade. Stocks have also been hurt by slowing growth in China, the negative fallout on sales and earnings of U.S. multinationals due to a stronger dollar and the steep losses in the energy sector, which have sent the energy sector of the S&P 500 down almost 24% this year.

Geopolitical threats around the globe and resurgence in terror attacks in the later stages of 2015 have also weighed on investor sentiment. Stock valuations are also above historical averages following the stock market’s more than tripling in value off of the lows back in March 2009.

All of our 10 ETFs in the Spotlight joined the last hour sell-off and closed lower. Leading the charge to the downside was Consumer Staples (XLP) with -1.12% while the Mid-Cap Value (IWS) held up best with -0.72%.

Read More

Volatility Remains The Word Of 2015

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

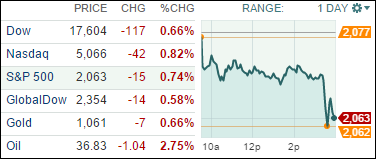
Stocks fell Wednesday, with losses accelerating towards the closing bell. This is the next-to-last day of trading in 2015, which has turned out to be a disappointing year for investors that have seen stocks trade sideways and post flat return for the most part. After today’s trading session, the S&P 500 is up just 0.2% for the year and the Dow is negative 1.2%. The shining light has been the Nasdaq, which is up nearly 8% for 2015.

What hurt stocks today is the same thing that has plagued the markets all year: falling oil prices due to oversupply. U.S.-produced crude dropped about 2.8% and closed at $36.81 a barrel. The reason being there was a report that showed another rise in U.S. inventory counts, according to the Energy Information Administration.

If you didn’t know, Intel (INTC) finally closed the $16.7 billion deal to buy chip maker Altera on Monday, which is Intel’s largest acquisition to date. The stock traded well yesterday, but took a hit today alongside the majority of the market. In a press release today, a spokesperson for Intel said the company estimates that Altera will contribute about $1.76 billion revenue to Intel’s Data Center Group segment in 2016.

All of our 10 ETFs in the Spotlight reversed and headed lower as oil’s jump yesterday proved to be a dead cat bounce. The Global 100 (IOO) led to the downside with a loss of -0.94%, while Consumer Staples (XLP) held up best by giving back only -0.35%.

Read More

Stocks Bounce Back As Oil Rallies

Ulli Market Commentary Contact

Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks skyrocketed as traders remain hopeful that a year-end ‘Santa Claus rally’ will finally push the major indexes back into positive territory for the year and avoid Wall Street’s first down year since 2008. Investors remain cautious though, as the so-called rally from Saint Nick, may not have yet completely taken flight.

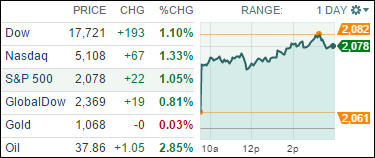
Of course, as we’ve seen in the recent past, equities are tied to the fortunes of oil, which rallied today and pulled the indexes higher. Not much has been gained over the past 2 months despite the S&P closing at 2078 today, which is still 2 points below the price it ended November and 1 point below the price we closed at in October. In other words, the market is just making up previous losses.

Nevertheless, Wall Street is hoping that a year-end rally holds, because if it doesn’t, there’s a good chance that both the Dow and S&P 500 could suffer their first calendar year decline since 2008 when stocks fell more than 30%.

We heard some positive news in the housing market today for investors, but maybe not for future home buyers. U.S. home prices rose 5.2% in October, compared to a year earlier. The housing market appears to be maintaining momentum, according to a key benchmark released Tuesday. The major markets that stood out on rising prices were Denver, Portland and San Francisco. At the bottom of the totem pole was Chicago, Washington D.C. and Cleveland.

And finally, energy stocks bounced back today, led by Chesapeake Energy Corp (CHK) and Consol Energy Inc (CNX).

All of our 10 ETFs in the Spotlight joined the party, with the leader being Healthcare (XLV) with +1.22%, while the Select Dividend ETF (DVY) lagged with +0.61%.

Read More

Markets Fail To Impress; Bulls Still Hoping For ‘Santa Claus Rally’ To End The Year

Ulli Market Commentary Contact

Mon pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

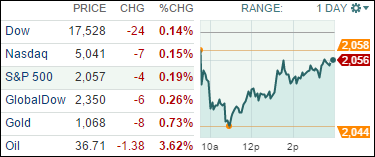
Stocks fell and oil prices took a tumble Monday, as the S&P 500 index kicked off the final week of the year by slipping back into the red in a volatile year that has made it tough for U.S. stocks to make much headway. Energy stocks led the declines as the recent uptick in oil prices also faltered. U.S. benchmark crude fell 3.3% to $36.85 a barrel.

We heard some positive news on the economic front today though. Holiday shoppers spent 7.9% more this year than they did in 2014, but they were expected to gravitate more toward online sellers, and brick-and-mortar retailers could feel the impact once the final numbers come out in early 2016.

As I said, it has been a challenging year for U.S. stocks. Domestic equities have been hurt by questions regarding the timing of the Federal Reserve’s first interest rate hike in nearly a decade (the Fed did in fact raise rates a quarter-point in mid-December), plunging oil prices, the negative impact of a strong dollar on sales and earnings of U.S. multinationals, and fears related to the slowdown in China’s economy, which is the world’s second-largest.

Wall Street is still hoping that the normal late-year rally, dubbed the Santa Claus Rally, will kick in this week. This time of year has historically been a seasonally strong period for stocks, as the market benefits from holiday-infused optimism and the benefit of a fresh influx of cash into the stock market as Americans put year-end bonuses to work.

2 of our 10 ETFs in the Spotlight managed to inch higher, led by the Low Volatility ETF (SPLV) with +0.31%. On the downside, we had a tie as Healthcare (XLV) and the Equal Weight S&P (RSP) each gave back -0.47%.

Read More