New ETFs On The Block: REX VolMaxx Long VIX Weekly Futures Strategies ETF (VMAX)

Ulli Volatility ETFs Contact

95551488REX Shares, the fairly new entrant in the exchange-traded funds space promoted by industry veteran Greg King, recently launched two products that focus on volatility of the broad-based large-cap US equity market.

The REX VolMAXX Long Weekly Futures Strategies ETF (VMAX) aims to provide exposure to the implied volatility of the broader large-cap US equities by investing in VIX futures-contracts with less than 30-day to expiry.

The actively-managed VMAX offers exposure to short-term futures contracts on the CBOE Volatility Index or SPX VIX, also known as the fear index. VIX is a reference for implied volatility of options on the S&P 500 with an expiry of 30 days and is calculated from a wide range of call and puts. An index value of 20 indicates the implied volatility of 30-day options on the S&P 500 is estimated as 20 percent.
Read More

ETF/No Load Fund Tracker Newsletter For May 27, 2016

Ulli ETF Tracker, Uncategorized Contact

ETF/No Load Fund Tracker StatSheet

————————————————————-

https://theetfbully.com/2016/05/weekly-statsheet-for-the-etfno-load-fund-tracker-newsletter-updated-through-05262016/

————————————————————

Market Commentary

STOCKS POST SOLID GAINS FOR THE WEEK; ARE THE BULLS BACK?

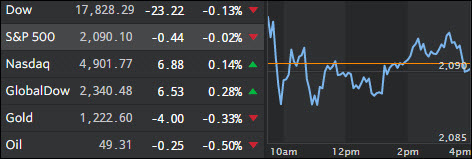
Fri pic

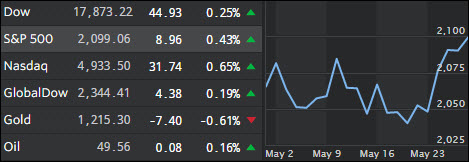
[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Markets posted modest gains today, but it was just enough to push the major indexes above water to a weekly gain and snap a 3-week losing streak.

As I mentioned yesterday, the Friday before Memorial Day is notoriously slow and was so today, despite a market-moving announcement from Janet Yellen in Massachusetts.

In her speech, she noted that it is “appropriate” for the Fed to “gradually and cautiously” increase interest rates “in the coming months” if the economy and labor markets continue to show improvement. Her comments fell in line with the lingering rhetoric over the past month that a rate hike is coming, perhaps in early June. That should have been a negative for the indexes but wasn’t. Does that mean the bulls are back? It’s a possibility, but in the absence of volume supporting such a rally, it may only be a bounce from an oversold position.

Another way to look at it is that the markets have not made a new high within the last year. History suggests that when that happens, the odds are 77% in favor of a bear market. This means you should be not only conservative when setting up new positions but always use my recommended sell stop discipline in case this turns into a bull trap. The indexes are still disconnected from reality as this chart from ZH makes abundantly clear:

Read More

Weekly StatSheet For The ETF/No Load Fund Tracker Newsletter – Updated Through 05/26/2016

Ulli ETF StatSheet Contact

ETF/Mutual Fund Data updated through Thursday, May 26, 2016

TOC040716

If you are not familiar with some of the terminology used, please see the Glossary of Terms.


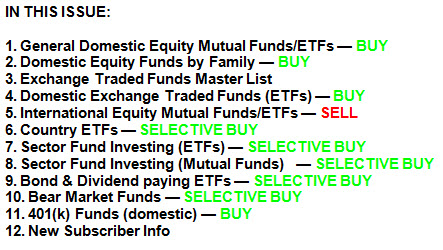
1. DOMESTIC EQUITY MUTUAL FUNDS/ETFs: BUY — since 4/4/2016

TTI

Our main directional indicator, the Domestic Trend Tracking Index (TTI-green line in above chart) remains above its long term trend line (red) by +1.76% after having generated a new Domestic Buy signal effective 4/4/2016 as posted.

Read More

No Upside Follow Through On Low Volume Day

Ulli Market Commentary Contact

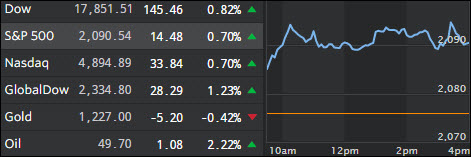
Thur pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Stocks went nowhere and held steady as most assets decoupled and closed lower. ZH reports that USDYPY headed south as did oil, high yield bonds and Treasury yields while the major stock indexes stubbornly remained in nosebleed territory closing around the unchanged line. Volume was atrocious.

Banks were a drag on the markets with equities taking a breather after their best 2-day advance in about 2 months as the S&P 500 attempted, but failed, to regain its 2,100 level, a milestone that it lost back on April 20th.

While the Friday before Memorial Weekend is a notoriously slow day on Wall Street, this may not be the case tomorrow as Fed chief Yellen is scheduled to speak at an event in Massachusetts that may shed some light on the future path of interest rates. She’s set to talk 45 minutes before the markets shut down for 3 days.

Read More

The Short Squeeze Continues

Ulli Market Commentary Contact

Wed pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

Markets are on a 3-day run heading into the end of May and it seems that a ‘Rally Cry’ is on the tip of everyone’s tongue despite China devaluing their currency to the lowest in 5 years and the U.S. services industry tanking. So, what is driving markets higher this week? A continued rise in oil prices and a flexing of strength in the housing market. Both of these signal that the economy and the market overall can allegedly withstand a (tentative) rate hike.

U.S. crude oil gained substantially today closing up 2.18% at $49.68 a barrel. Many analysts are saying that if the commodity pushes above $50 a barrel, that the bulls can once again blow some steam out their nose and start kicking the dirt. So, let’s keep an eye on oil prices heading into the summer.

As investors are watching the Fed and their deliberations over hiking rates, one other commodity has been hit hard. That commodity is gold. The precious fine metal is at a seven-week low, now priced at $1,222.85 per ounce and U.S. gold futures have fallen accordingly. Adding to the downtrend of Gold has been the continued rise in the USD, which still stands near a two-month high against a basket of major currencies.

Read More

Markets Storm Back With Force But No Volume

Ulli Market Commentary Contact

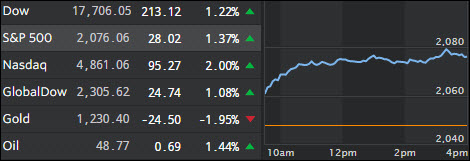
Tue pic

[Chart courtesy of MarketWatch.com]

1. Moving the Markets

After an uneventful start to the week, markets here in the U.S. sprang back into action and posted their largest gains since early May. All three major indexes gained at least 1.20% on the day but with volume being downright atrocious, this move is suspect.

The year has been volatile thus far to say the least. A big reason for this volatility has been the Federal Reserve’s on-again, off-again plan to normalize interest rates. However, markets always tend to react well to solid economic data, and it was good news on the housing front that pushed markets higher today.

The Commerce Department reported that sales of new single-family homes jumped almost 17% to an annualized pace of 619,000 in April. That is the highest level since January 2008 and well above the 523,000 new home sales that economists were expecting in April. Of course, extreme numbers like this are likely to be revised sharply, which we will find out next month.

Also providing a lift for stocks Tuesday was a reversal to the upside for U.S. crude, which traded lower in the day, but mounted a strong comeback by the closing bell. A barrel of U.S. crude gained 1.48% on the day to close at $48.78.

And in M&A news, I mentioned yesterday that Monsanto (MON) was being courted for an acquisition by Bayer AG (BAYRY). Well, news stories today were quite clear in stating that Monsanto has officially turned down the $62 billion offer as being “financially inadequate”. A spokesperson from the company did say that they would entertain future offers from Bayer AG though.

Read More