1. Moving the Markets
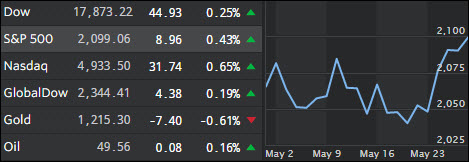
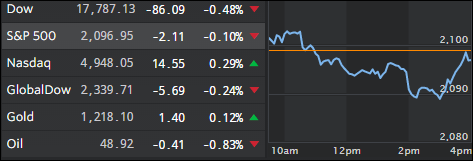
Although markets did little to impress in the first day of trading after the holiday weekend, the gains from last week were enough to maintain a positive month overall for May. This marks the third straight month of gains for the S&P 500 for a grand total of +1.8%.
Today, we heard mixed news on consumer health here in the U.S. April income rose 0.4% and spending jumped 1%, which was more than analysts’ had forecast. However, consumer confidence in May disappointed. The Conference Board reported that the May confidence reading came in at 92.6, below April’s 94.7 level and below the May estimate of 96.1. Manufacturing contracted and Chicago PMI came in below expectations; nothing but weak data that might not give the Fed the warm fuzzies when considering a rate hike later this month.
During May, stocks got a hearty lift from oil surging above $50 per barrel for the first time since October. The $50 per barrel target price is something to keep an eye on as we head towards the summer months unless, of course, oil prices collapse again like they did last summer.
Later this week, Wall Street will be closely watching a key monetary policy meeting of the ECB and an OPEC gathering, although analysts don’t expect any announcement on oil production cuts in the imminent future.
 It looks like the SEC is finally ready to put a stop to accounting shenanigans.
 REX Shares, the fairly new entrant in the exchange-traded funds space promoted by industry veteran Greg King, recently launched two products that focus on volatility of the broad-based large-cap US equity market.