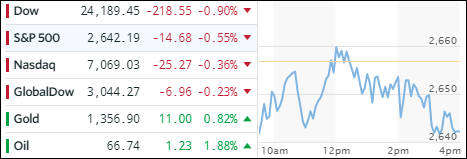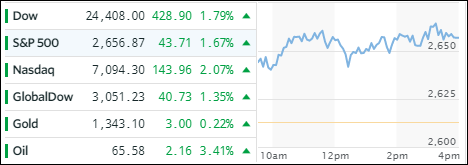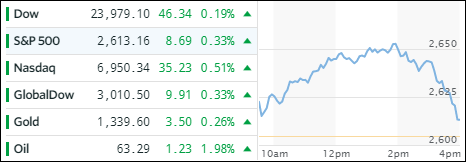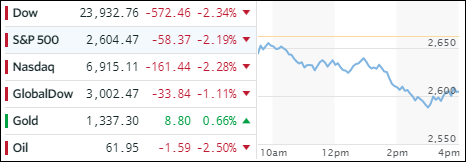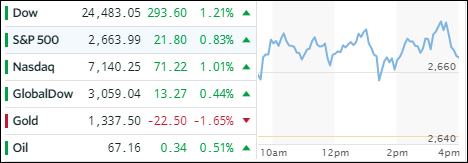
- Moving the markets
The tug-of-war continued today as talk, that a strike on Syria may not be immediately in the cards, de-escalated tensions and giving a bullish assist to equities. The 3 major indexes scored solid gains after yesterday’s losses.
Six out of the eleven primary S&P sectors gained led by Financials (XLF +1.75%) with Semiconductors (SMH +1.66%) taking second place.
While geopolitical concerns took center stage, Trump’s rhetoric softened from Wednesday’s “get ready Russia,” to Thursday’s “never said when an attack on Syria would take place. Could be very soon or not so soon at all!” In other words, he said absolutely nothing.
Besides the war mongering atmosphere, the markets still have trade sanctions with China to deal with and the upcoming earnings season, which is expected to be strong. In the meantime, the S&P has been dancing around its 200-day M/A successfully so far but has been trending sideways in a broad range.
In other words, we have some positives, negatives and a bunch of uncertainty, either of which will be able to affect market direction on any given day, hence the roller coaster environment. Should the negative factors overwhelm the positive ones, we may very well see our Trend Tracking Indexes (TTI) head south again, but it remains to be seen whether that downside momentum strengthens to a point where all-out “Sell” signals are being generated.
Stay tuned!